Virtual CTO for FinTech Startups: Architecting Banking API Integrations With Zero Downtime
Fintech founders face a tough puzzle. You must launch fast, stay secure, and never let payments fail. Yet many startups cannot afford a full-time chief technology officer. Therefore, a virtual CTO for fintech startups can be a smart answer. This expert guides your technology plan on a flexible basis. One of the hardest tasks is connecting to banks through APIs without any downtime. This guide explains how a virtual CTO approaches that job. You will also learn the design habits that keep money moving.
What Is a Virtual CTO for FinTech Startups?
A virtual CTO is a senior technology leader who works with you part time or on contract. Some people call this role a fractional CTO. The person sets your tech strategy, guides your engineers, and reviews key choices. You pay only for the time you need. That makes the model a smart fit for early-stage teams.
Fintech adds special pressure to this role. Your product handles real money and sensitive data. Regulators watch closely, and customers lose trust fast after an outage. A virtual CTO who knows fintech understands these risks. They bring experience from many projects, so you avoid common traps.
Typical duties are broad. They pick the tech stack and design the system architecture. They set security standards and plan for compliance rules such as PCI DSS. Hiring and coaching developers is part of the job too. Most of all, they connect tech choices to business goals.
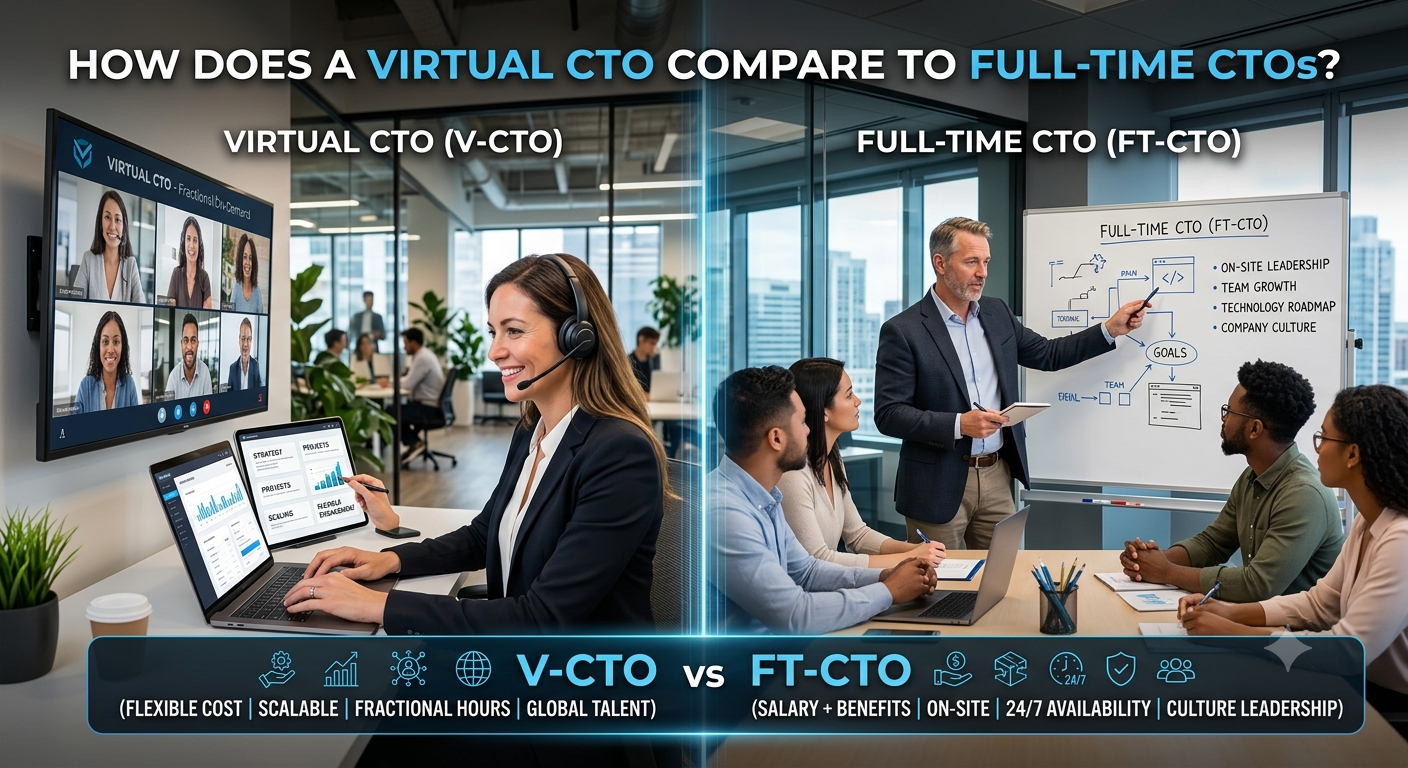
Compare this with a full-time CTO. A full-time hire costs more and may take months to find. A virtual CTO can start within weeks. As your company grows, you can move to a full-time leader with a clean plan already in place.
Consider a small payments startup with five engineers. The team knows how to build features but lacks bank experience. A virtual CTO reviews the plan, spots weak points, and sets clear standards. Developers gain confidence, and the founder gains a trusted adviser. Moreover, investors like to see this level of technical care.
Why Banking API Integrations Are Hard
Banking APIs let your app talk to banks and payment networks. They power account checks, payments, and balance data. Open banking rules in many regions make these APIs more common. However, each bank works differently. Formats, limits, and rules vary widely.
Banks also change systems without much warning. An API may slow down, return odd errors, or go offline for maintenance. Your product must handle all of this smoothly. A single weak link can freeze payments for thousands of users.
Security adds more weight. You must protect tokens, keys, and customer data at every step. Rules require strong authentication and careful logging. Mistakes can lead to fines and lost trust.
For these reasons, integration cannot be an afterthought. It needs a clear architecture from day one. That is exactly where a virtual CTO adds value.
Cost is another factor. Every hour of downtime can mean failed payments and angry customers. Support tickets rise, and partners start to worry. Additionally, repeated outages may put your bank relationship at risk. Prevention is always cheaper than recovery, and it keeps your team calm.
How a Virtual CTO Designs for Zero Downtime
Zero downtime means your service stays available even when parts fail or change. No system is perfect, but good design gets very close. Here are the core ideas a virtual CTO uses.
Build a Clean API Gateway Layer
A gateway sits between your app and every bank API. Your core product talks only to the gateway. The gateway handles each bank’s format, rules, and quirks. If a bank changes something, you fix one place instead of many. This also makes adding new banks much faster.
Use Retries, Timeouts, and Circuit Breakers
Networks fail often, so plan for that. Smart retries try again after a short pause. Timeouts stop your system from waiting forever. A circuit breaker cuts off a failing service for a moment so it cannot drag everything down. Together, these tools keep small problems small.
Make Payments Safe to Repeat
However, retries can cause double payments if you are careless. The fix is called idempotency. Each payment request carries a unique key. If the same request arrives twice, the system processes it only once. This protects customers and your reputation.
Add Backup Routes and Queues
Never depend on one bank connection for critical flows. A backup provider can take over when the main one fails. Message queues store requests safely during a slowdown. As a result, work continues once the service recovers. Customers see a short delay instead of an error.
Data consistency deserves attention too. When a payment moves between systems, every record must match. Reconciliation jobs compare your ledger with bank statements each day. Any gap triggers an alert. This habit catches quiet errors before customers notice them.
Release Without Stopping the Service
Deployments often cause outages. Blue-green deployment avoids this. You run the new version next to the old one and switch traffic only after tests pass. If something breaks, you switch back in seconds. Feature flags let you turn new code on for a few users first.
Testing, Monitoring, and Compliance
However, design alone is not enough. Teams must test and watch the system all the time. A virtual CTO builds these habits into your culture.
Start with sandbox testing. For example, most banks offer test environments. Run real scenarios there, including failures and slow responses. Load tests show how your system behaves at peak traffic. Chaos tests, which break parts on purpose, reveal hidden weak spots.
Monitoring comes next. Track response times, error rates, and payment success rates. Set alerts that reach the right person quickly, day or night. Dashboards should show the health of every bank connection at a glance. Clear logs help your team find causes in minutes, not hours.
Meanwhile, compliance needs equal care. Encrypt data in transit and at rest. Limit access with roles and strong authentication. Keep audit trails for every payment action. Plan regular security reviews and penetration tests. These steps satisfy regulators and calm nervous partners.
Finally, prepare for incidents. Write a simple runbook that explains who does what during an outage. Practice it with your team. After each incident, hold a blameless review and fix the root cause. Over time, your platform becomes tougher and easier to trust.
How to Work With a Virtual CTO for FinTech Startups
Set clear goals before you start. Do you need an architecture plan, a team review, or a compliance roadmap? Agree on deliverables and a schedule. Decide how you will measure success after three months. Ask for regular reports in plain language.
Look for real fintech experience. Ask about past banking API projects and how they handled outages. Check references and past results. Ask to see sample architecture notes or reports. A good virtual CTO explains complex ideas simply and listens to your business needs.
Treat the relationship as a partnership. Give access to your team, your data, and your roadmap. Involve your developers in decisions so knowledge stays in-house. Review progress each month. The best outcome is a stronger internal team that can run without constant outside help.
Conclusion: Keep Payments Running With the Right Tech Leadership
A virtual CTO for fintech startups gives you expert leadership without the cost of a full-time hire. Clean gateways, safe retries, backup routes, and careful releases help banking API integrations run with zero downtime. Strong testing, monitoring, and compliance make the system even more reliable. If your startup is growing fast, now is a great time to get expert guidance. Solid technology today protects your customers and your future. Take the first step by reviewing where your current integrations might fail.
Frequently Asked Questions
What does a virtual CTO for fintech startups do?
A virtual CTO sets technology strategy, designs architecture, and guides engineers on a part-time basis. In fintech, they also focus on security, compliance, and banking API integration.
How is a virtual CTO different from a full-time CTO?
A virtual CTO works flexibly and costs less. A full-time CTO is embedded daily in your company. Many startups begin with virtual leadership and hire full-time later.
How can banking API integrations have zero downtime?
Use a gateway layer, retries, circuit breakers, backup providers, and blue-green releases. Add strong monitoring so problems are caught early.
When should a fintech startup hire a virtual CTO?
Hire one when you plan your first product build, prepare for a bank partnership, or face scaling problems. Early guidance prevents costly rework.
What is idempotency in payment APIs?
Idempotency means the same request gives the same result, even if sent twice. It stops duplicate charges when a retry happens.
Also Read:
How Do You Implement AI Dynamic Pricing Today? Ultimate Guide