How Should Businesses Reprice Their Products After UPI MDR Changes?
For years, UPI payments cost merchants nothing. The UPI MDR changes will alter that. From 15 October 2026, a new merchant discount rate, or MDR, applies to some UPI payments. Many owners now ask a fair question. Should we raise prices, absorb the fee, or find a smarter path? This guide answers that question in plain words.
The rules are new, so details may shift. Check your bank or payment provider for the latest terms. Talk to your chartered accountant before you change any price. The steps below are general guidance, not financial advice. They give you a clear starting point for your own numbers.
What the UPI MDR Changes Mean for Your Business
MDR is a fee that a merchant pays to process a digital payment. It is usually collected by banks and payment providers. Under the new framework, a 0.4% MDR applies to eligible person-to-merchant UPI payments above Rs 2,000. Reports say the fee is capped at Rs 300 per transaction. Payments up to Rs 2,000 remain free, and so do person-to-person transfers.
Some sectors get a flat, lower charge. Reports list railways, telecom, insurance, fuel, and farm inputs in this group. The flat fee in those cases is Rs 5. Small merchants are said to stay exempt. Furthermore, customers do not pay the fee. The merchant does.
Here is a simple example. A customer pays Rs 3,000 for an order. The fee at 0.4% is Rs 12. You receive Rs 2,988 in your account. For a single sale, that sounds small. However, the total adds up when you sell hundreds of orders each month.
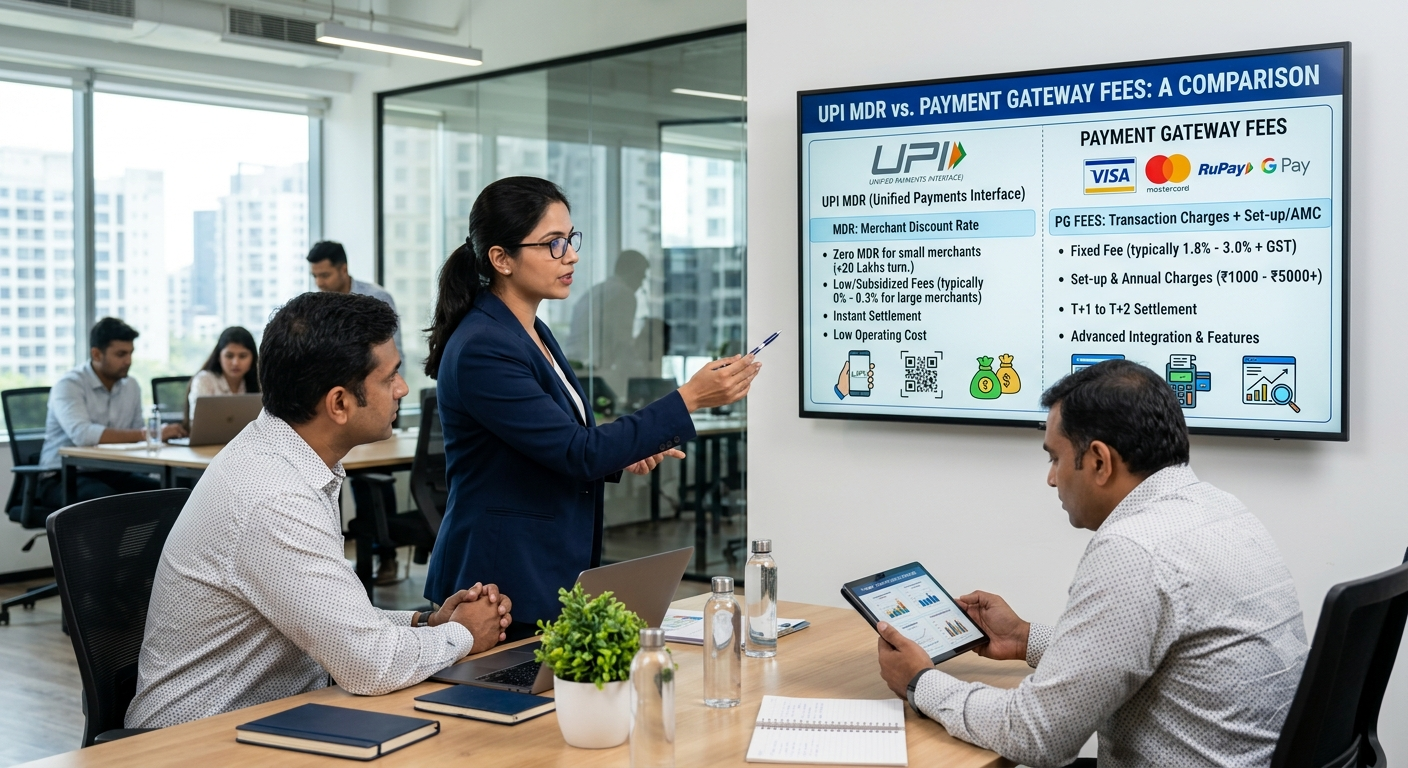
Meanwhile, cards already carry a fee for merchants. UPI at 0.4% is lighter than most card costs. Therefore, shifting customers away from UPI may not save you money. In short, think of this as one more line in your cost sheet. Treat it with math, not panic.
Who Feels the Change Most?
High-ticket sellers will feel it first. Think of electronics, furniture, jewellery, and B2B supplies. Online stores with large baskets see more orders above Rs 2,000. Low-ticket shops feel far less impact. Food stalls and small grocers mostly stay below the limit.
Sector matters too. Fuel, telecom, insurance, and rail payments are reported to carry a flat Rs 5 fee. Those businesses may see almost no change. Marketplaces and platforms may handle the fee differently, so contracts should be read closely. Fees are often deducted before settlement. Settlement reports should be checked line by line.
How to Measure the Real Cost to Your Margins in UPI MDR
Start with your own data. Pull the last three months of UPI sales. Count only the payments above Rs 2,000. Multiply that total by 0.4%. Note that the Rs 300 cap and any flat fees may change the final number.
Next, compare the fee with your margin, not your price. This is the step most owners miss. Say your gross margin is 20% on a Rs 3,000 sale. Your margin is Rs 600, and the fee takes Rs 12. That is 2% of your margin. Now say your margin is only 3%. The margin is Rs 90, and the fee takes 13% of it.
This view shows who needs to act. Healthy margins can often absorb the change. In contrast, thin margins cannot. As a result, a fixed price rise across all products is rarely the best move. Look at each product line on its own.
A simple sheet makes this easy. List each product, its price, and its margin. Add the expected fee for orders above Rs 2,000. Sort the list by fee share of margin. Products at the top are the ones to fix first. Decisions are guided by data, not guesswork.
Also check where else payments leak profit. Look at refunds, chargebacks, delivery costs, and gateway fees. Sometimes a small fix there saves more than the new MDR costs. For example, better address checks can cut returns. Lower returns protect margin quietly.
Consider timing as well. The new rules start on 15 October 2026, so plan your changes before then. Festive sales often begin around this time. Price boards and websites should be updated ahead of launch. Old quotes must be honored if you promised them. Contracts with large clients should be reviewed early.
Smart Ways to Reprice Products After UPI MDR Changes
You have four main options. Each one suits a different type of business. You can mix them. Test any change on a small group first.
Option 1: Absorb the Cost
Absorbing the fee keeps prices stable. It works when margins are healthy and competition is tight. It builds goodwill with loyal customers. However, you must track the cost closely. Review it every quarter so it does not grow unnoticed.
Option 2: Build the Fee Into the Price
Next, add a small amount to the base price of affected items. The math is simple. To protect your net price, divide it by 0.996. A Rs 3,000 item sells near Rs 3,012. Most buyers will not notice a change this small. Round to a clean number like Rs 3,015 for a smooth look.
Round prices with care. Prices ending in 9 or 5 are trusted by many shoppers. New prices should be tested on a few products first. Results are compared with the old prices after two weeks. Rollback plans are prepared in advance.
Be careful with separate payment charges. Rules on extra fees for UPI can be strict. Check with your bank and legal advisor first. Many merchants prefer a blended price for this reason. It is easier to explain.
Option 3: Use Tiered Pricing and Order Thresholds
Some businesses add a free-delivery bar or a bundle deal. This lifts basket size and spreads the fee over more profit. Others offer small discounts for prepaid orders on cheaper payment modes. Use these carefully and keep offers fair. Never split one payment into two just to dodge the fee, since that may break rules.
Option 4: Improve Your Product Mix
Push higher-margin items. Trim products that barely earn a profit. Renegotiate supplier rates where you can. Small gains here can cover the MDR many times over. Thus, repricing is only one lever among several.
Similarly, supplier deals matter too. Volume discounts are often available when orders are planned early. Payment terms can be stretched to ease cash flow.
How to Tell Customers About Price Changes Without Losing Them
Clear words build trust. Explain changes in one or two short lines. Instead, focus on value, not on the fee. Avoid blaming banks or the government. Customers care about what they get.
First, give notice before you change prices. A week or two works well for most stores. Update your website, invoices, and social pages together. Train your support team on simple answers. Consistent replies stop confusion.
Sales teams need a short script. Questions are asked most often at checkout, so support staff must be ready. Answers should be kept short and friendly. Internal notes are shared with every channel, from chat to phone.
Watch your data after the change. Track conversion rate, cart size, and refund rate. Compare them with the weeks before. If sales drop sharply, review your move. You can roll back a change in a single day.
Keep your finance and tech teams aligned. Your payment gateway reports show fees per order. Match them with your books each month. Automate this if you can. Clean reports make every later decision easier.
Final Thoughts: Reprice With Data, Not Fear
The UPI MDR changes are real, yet they are modest for most sellers. The 0.4% rate is small, and many payments stay free. What matters is your margin, your product mix, and your customer mix. Measure the true cost first. Pick the mix of options that fits your brand.
Start this week. Pull your UPI data, run the margin math, and pick one product line to test. Review results after a month. Small, careful changes protect profit and trust together.
Costs are tracked, prices are tested, and customers are informed. That is the whole plan in one line.
Frequently Asked Questions
What are the UPI MDR changes for merchants?
From 15 October 2026, a 0.4% MDR applies to eligible person-to-merchant UPI payments above Rs 2,000. Smaller payments remain free. Check your provider for exact terms.
Do customers pay the UPI merchant discount rate?
No. The merchant pays the fee. Customers pay only the price you set.
Should I raise all my prices after UPI MDR changes?
Not always. Check margins for each product first. Thin-margin items may need a change, while others can absorb the cost.
Is it legal to add a UPI surcharge?
Rules on extra payment charges can be strict. Ask your bank and legal advisor before you add any separate fee. A blended price is often simpler.
How can I calculate the UPI MDR cost for my business?
Total your UPI sales above Rs 2,000 and multiply by 0.4%. Compare that fee with your gross margin. Remember the cap and any flat fees.
Also Read:
How Do UPI MDR and Payment Gateway Fees Compare?
How Do You Handle CTO Transitions Without Friction? Ultimate Guide