How Do Smart Businesses Use Voice Payments

How Do Smart Businesses Use Voice Payments? Complete Guide

Voice-Activated Payments: Use Cases and Adoption Challenges

Introduction

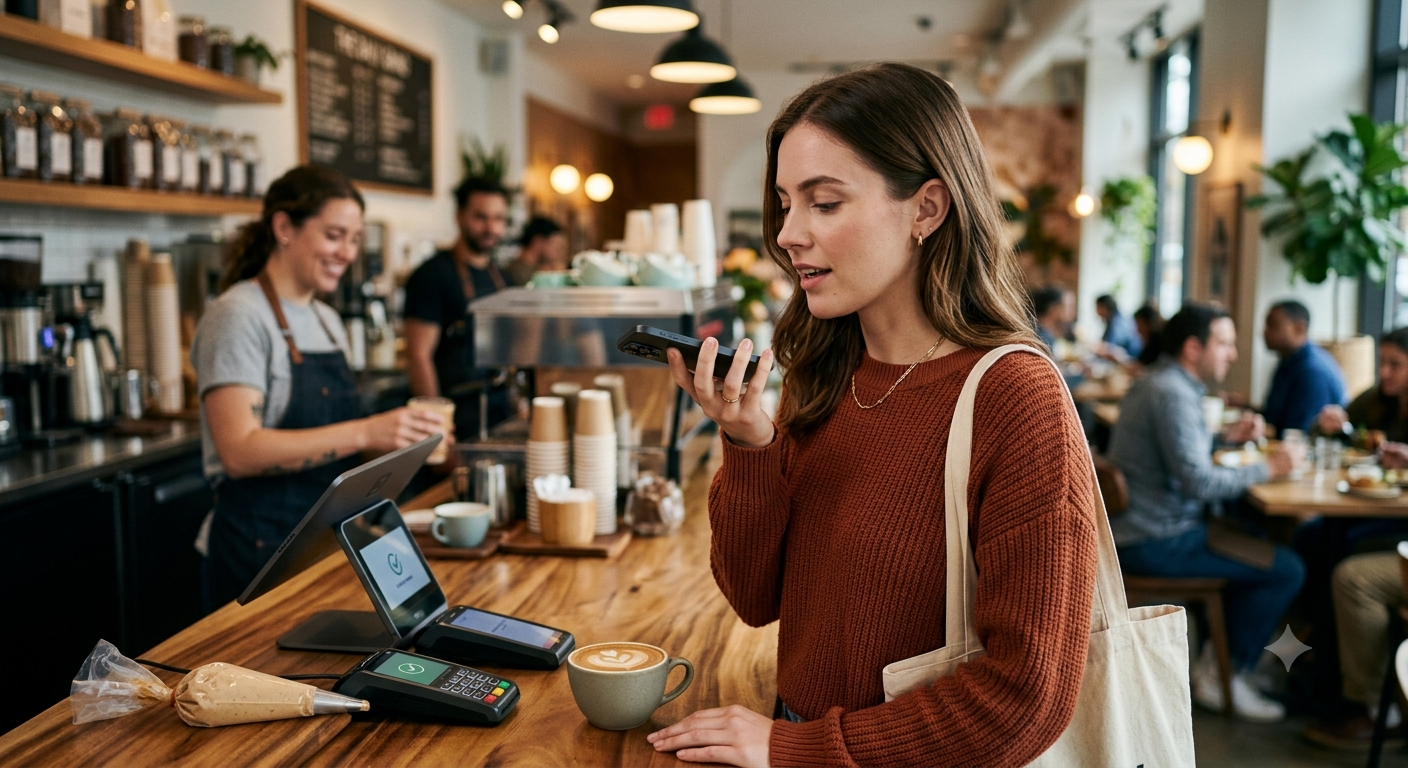
Voice-activated payments let people pay using only their voice. No typing, no swiping, and no tapping a screen. This technology is growing fast as smart speakers and voice assistants become common in homes and cars.

Business owners and developers want to know how this trend works in real life. This guide covers the top use cases, the benefits, and the challenges that come with adoption. Let’s explore how voice payments are shaping the future of commerce.

Consumers increasingly expect fast, effortless checkout experiences. Voice technology answers that demand directly. Understanding both the opportunities and the risks helps businesses plan a smarter rollout strategy.

What Are Voice-Activated Payments

Voice-activated payments use speech recognition to complete a transaction. A user simply speaks a command, such as asking a smart speaker to reorder groceries. The system verifies the request and processes the payment.

This technology relies on voice assistants like Alexa, Google Assistant, and Siri. These assistants connect to banking apps or payment platforms in the background. As a result, users complete purchases without touching a device.

Voice payments also use security layers like voice recognition and PIN confirmation. This helps prevent unauthorized transactions. Consequently, the system balances convenience with safety for everyday users.

The technology has grown alongside smart speakers and voice-enabled apps. Millions of households already own a device that supports voice commands. As a result, the audience for voice payments keeps expanding every year.

Businesses find this appealing because it removes friction from checkout. A shorter, simpler payment process often leads to higher completion rates. Similarly, customers enjoy the speed and ease of a hands-free experience.

Developers build these systems using natural language processing and secure payment APIs. The two technologies work together behind the scenes. This combination turns a spoken sentence into a completed, verified transaction.

Tokenization also protects sensitive card details during a voice transaction. Instead of storing raw numbers, the system uses secure tokens. This reduces the impact of any potential data breach significantly.

Multi-factor confirmation is becoming standard practice too. Combining a voice print with a device check adds another safety net. This layered approach reduces fraud without slowing the customer down too much.

Top Use Cases for Voice-Activated Payments

Voice payments show up in many everyday situations. Retail is one of the biggest areas. Shoppers can reorder favorite products just by speaking to a smart speaker at home.

Banking is another strong use case. Customers can check balances or transfer money using voice commands through their bank’s app. This saves time compared to logging in manually.

Food delivery services also use voice payments. Users can order meals hands-free while cooking or driving. Similarly, ride-sharing apps let users book and pay for rides through voice assistants.

In the automotive industry, connected cars allow drivers to pay for fuel or parking without leaving the vehicle. This use case is growing quickly as more cars include built-in voice assistants.

Healthcare providers are testing voice payments as well. Patients can pay medical bills or copays through voice-enabled portals. This makes billing easier for people with limited mobility or busy schedules.

Utility companies increasingly offer voice-based bill pay options too. Customers simply confirm the amount by voice, and the system handles the rest. This reduces late payments and improves customer satisfaction.

Voice Payments in Smart Homes

Smart home devices make voice payments even more useful. Homeowners can pay utility bills or subscribe to services just by speaking. This hands-free approach fits busy daily routines perfectly.

Subscription boxes and grocery refills also work well with this setup. A quick voice command restocks household items without opening an app. This convenience keeps customers coming back for repeat purchases.

Key Adoption Challenges Businesses Face

Despite its promise, voice-activated payment adoption faces real hurdles. Security remains the top concern. Voices can sometimes be mimicked or recorded, which creates fraud risks.

Therefore, companies must use multiple layers of verification. This might include voice biometrics combined with a spoken PIN. However, adding steps can reduce the convenience that makes voice payments attractive in the first place.

Another challenge is accuracy. Background noise or accents can confuse voice recognition systems. This leads to failed transactions and frustrated users. Developers must keep improving speech recognition models to reduce these errors.

Trust is also a barrier. Many people feel uneasy about speaking financial details out loud. Privacy concerns grow when payments happen in shared spaces, like a living room with guests present.

Finally, technical integration is complex. Businesses need to connect voice assistants with existing payment systems securely. This requires strong developer support and ongoing testing to avoid glitches.

Regulatory compliance adds another layer of difficulty. Payment rules differ across regions and industries. Businesses must ensure their voice payment system meets local financial regulations before launching publicly.

User experience design is often overlooked too. A confusing voice flow frustrates customers quickly. Clear prompts and short confirmation steps make the process feel natural instead of clunky.

Language and accessibility gaps also matter. Not every customer speaks the same language or dialect supported by the system. Businesses that ignore this risk excluding large groups of potential users.

How Businesses Can Prepare for Voice Payment Growth

Businesses ready to adopt voice payments should start with a clear strategy. First, identify where voice commands add real value, such as reorders or bill payments. Not every transaction needs a voice option.

Next, invest in strong security protocols. Use voice biometrics along with backup verification methods. This builds customer trust while reducing fraud risk. Meanwhile, always give users an alternative way to pay if voice fails.

Testing matters too. Run pilot programs before a full launch. Gather user feedback and fix issues early. This approach saves money and prevents a poor first impression.

Finally, educate customers about how the system works. Clear instructions reduce confusion and build confidence. As adoption grows, businesses that prepare early will gain a strong competitive advantage.

It also pays to monitor industry trends closely. Payment technology changes fast, and new standards appear often. Staying updated helps businesses avoid falling behind competitors who adapt quickly.

Partnering with experienced payment providers can shorten the learning curve. These partners understand compliance, security, and integration challenges already. This support reduces risk during the early stages of adoption.

Measuring Success After Launch

Once voice payments go live, track key metrics closely. Watch completion rates, failed transactions, and customer feedback scores. These numbers reveal whether the system truly helps customers.

Adjust prompts and verification steps based on real usage data. Small changes often fix common friction points quickly. As a result, the experience keeps improving after the initial launch.

Compare performance against traditional payment methods too. This comparison shows whether voice payments actually save time or reduce errors. Consistent measurement keeps the strategy honest and effective.

Share results with your team regularly. Transparency around wins and setbacks builds momentum for future improvements. Over time, this data-driven approach turns a pilot project into a trusted, long-term system.
How Do Smart Businesses Use Voice Payments

Conclusion

Voice-activated payments offer real convenience for both businesses and customers. Use cases span retail, banking, food delivery, and connected cars. However, adoption challenges like security, accuracy, and trust still need attention.

Companies that address these challenges thoughtfully will lead this growing market. Voice commerce is not just a trend. It is becoming part of daily life for many consumers.

Businesses that invest early in secure, well-tested voice payment systems will build stronger customer loyalty. Patience and careful testing today lead to smoother, more trusted experiences tomorrow.

Looking ahead, expect voice recognition accuracy to keep improving. As it does, more industries will explore fresh use cases beyond the ones covered in this guide.

Ready to lead in this space with confidence? Build your authority with Digital Payment Guru and stay ahead of the voice payment revolution.

Frequently Asked Questions

1. What are voice-activated payments?

Voice-activated payments let users complete transactions by speaking to a device, such as a smart speaker or voice assistant, instead of typing or tapping.

2. Are voice-activated payments secure?

They can be secure when combined with voice biometrics and extra verification steps like a spoken PIN. Businesses should always add layered security.

3. Which industries use voice payments the most?

Retail, banking, food delivery, and the automotive industry use voice payments heavily. Smart home services also rely on this technology often.

4. Why do some businesses hesitate to adopt voice payments?

Businesses worry about fraud risks, accuracy issues, and customer trust. These challenges require careful planning and strong security measures.

5. How can a business start using voice payments? Start with a small pilot program, add strong security, and gather customer feedback. This helps identify problems before a full rollout. A trusted payment partner can also speed up the process.

Also Read:

How Do Modern Brands Manage B2B Payments? Ultimate Guide

How Do Split Payments Boost Seller Retention? Ultimate Guide
How India’s Financial Regulations Are Shaping Fintech Innovation

How Financial Regulations in India Shape Fintech Growth?

How India’s Financial Regulations Are Shaping Fintech Innovation

Introduction

India’s fintech sector is growing at a remarkable pace. Millions of people now use digital payments, lending apps, and online banking every day. Behind this growth sits a strong framework of financial regulations in India. These rules shape how fintech companies build products and reach customers.

This article explores how India’s financial regulations are shaping fintech innovation. You will learn which rules matter most, how they affect startups, and what founders should expect next. Business owners, technical managers, and digital marketers will find practical insight here. Additionally, this guide explains complex rules in simple terms.

India now has one of the largest digital payment markets in the world. This scale did not happen without careful oversight. Regulators and innovators have worked together, sometimes with friction, to build a system that millions trust every day.

The Regulatory Foundation Behind India’s Fintech Boom

India’s fintech growth did not happen by accident. The Reserve Bank of India, or RBI, built a strong foundation for digital finance. This foundation includes the Unified Payments Interface, known as UPI, which now processes billions of transactions each month.

The RBI also created clear licensing rules for payment banks and non-banking financial companies. These rules give fintech startups a path to operate legally. As a result, entrepreneurs know what steps to follow before launching a product. This clarity reduces risk for investors too.

Data protection has become a growing focus for regulators. The Digital Personal Data Protection Act sets rules for how companies collect and store user data. Fintech companies must follow these rules carefully. Consequently, product teams now build privacy into their apps from day one, not as an afterthought.

Regulatory sandboxes have also played a key role. The RBI allows selected startups to test new products in a controlled environment. This helps regulators understand new technology before writing formal rules. Meanwhile, startups get real feedback without facing the full weight of compliance too early.

The Securities and Exchange Board of India, or SEBI, also shapes fintech through rules for investment platforms and wealth-tech apps. Together, these bodies form a layered system of oversight. Each layer targets a different part of the financial ecosystem, from payments to lending to investing.

The Insurance Regulatory and Development Authority of India, known as IRDAI, plays a similar role for insurtech startups. This layered approach means fintech founders must understand more than one regulator, depending on which financial services they offer.

How Compliance Rules Push Financial Regulation Forward

Many founders assume regulation slows down innovation. In India’s fintech space, the opposite has often proven true. Clear rules create trust, and trust drives adoption among cautious users.

Know Your Customer, or KYC, requirements are a good example. These rules force fintech apps to verify user identity before opening an account. This process once took days using paper documents. Today, video KYC and Hadar-based verification make on-boarding fast and secure. Therefore, compliance rules pushed companies to build better technology.

Similarly, RBI guidelines on data localization require companies to store Indian payment data within the country. This rule pushed fintech firms to invest in local cloud infrastructure. In turn, this investment supported the growth of India’s broader technology ecosystem.

Payment aggregator and payment gateway rules also raised the bar for security. Companies must now meet strict standards before processing transactions. This has reduced fraud and increased consumer confidence in digital payments. In contrast, markets with weaker rules often see slower adoption due to trust issues.

Lending regulations have reshaped how digital lenders operate too. The RBI’s digital lending guidelines require clear disclosure of interest rates and fees. This protects consumers from hidden charges. Fintech lenders that comply well often see stronger customer loyalty as a direct result.

Similarly, rules around recovery practices have pushed lenders to build more respectful collection processes. Aggressive tactics that once damaged brand reputation are now restricted by law. This shift has encouraged fintech lenders to invest in better customer support systems instead.

Challenges Fintech Startups Face Under Current Financial Regulations

Regulation is not without its challenges for fintech startups. Compliance costs can be high, especially for early-stage companies. Building systems for KYC, data protection, and reporting requires time and money that small teams may not have.

Frequent regulatory updates also create uncertainty. The RBI and other bodies update guidelines regularly to keep pace with new technology. Startups must stay alert and adjust their products quickly. Otherwise, they risk falling out of compliance without realizing it.

Cross-border payment rules add another layer of complexity. Fintech companies working with international partners must navigate both Indian rules and foreign regulations. This dual compliance burden can slow product launches significantly.

Despite these challenges, most founders agree that strong regulation ultimately builds a healthier market. It filters out weak players and rewards companies that invest in proper systems. Thus, long-term winners in India’s fintech space tend to be those who treat compliance as a strategic advantage, not a burden.

Smaller startups often partner with compliance experts to manage this load. This allows founders to focus on product and growth while specialists handle regulatory details. This approach has become common across the industry.

Talent shortages also add pressure. Skilled compliance officers who understand both finance and technology are hard to find. Fintech companies often compete with banks and larger financial institutions for the same limited pool of experts. This drives up hiring costs for early-stage teams.

Investor expectations have shifted as a result of these challenges. Venture capital firms now look closely at a startup’s compliance readiness before writing a check. A strong regulatory foundation has become just as important as a strong product in fundraising conversations.

What’s Next for Financial Regulations in India

India’s regulators continue to refine the rules around emerging technology. Central Bank Digital Currency, or CBDC, pilots are already underway. The digital rupee could reshape how payments work across the country in the coming years.

Artificial intelligence in lending and credit scoring is also drawing regulatory attention. The RBI has signaled interest in setting clear guidelines for AI-driven financial decisions. This will likely shape how fintech companies build credit models going forward.

Open banking frameworks are expanding as well. Account aggregator systems now let users share financial data securely across institutions. This creates new opportunities for personalized financial products. However, it also raises fresh questions about consent and data security that regulators must address.

Fintech founders who track these changes closely will be better positioned to adapt. Building flexible systems that can adjust to new rules quickly will become a real competitive advantage. Staying engaged with industry bodies and regulatory updates is no longer optional for serious players.

Cybersecurity requirements are also likely to tighten. As digital transactions grow, regulators want stronger protection against fraud and cyberattacks. Fintech companies that invest early in robust security systems will avoid costly disruptions later.

How India’s Financial Regulations Are Shaping Fintech Innovation

Conclusion

India’s financial regulations continue to shape fintech innovation in powerful ways. Strong rules around KYC, data protection, and lending have built trust with millions of users. While compliance brings real challenges, it also creates a stronger, more sustainable market for everyone involved.

This balance between oversight and innovation is rare globally, and India has managed it better than most large economies. Founders who study this model closely can apply the same principles even beyond India’s borders.

Founders and business leaders who understand this regulatory landscape gain a real edge. They can build products that scale with confidence instead of facing surprises later. Treating compliance as a growth strategy, rather than a checkbox, sets strong fintech brands apart from the rest.

Build your authority with Digital Payment Guru, and position your fintech brand as a trusted name in this fast-moving industry. The founders who understand regulation today will shape the fintech products India relies on tomorrow.

Frequently Asked Questions About Financial Regulations

1. How do financial regulations in India affect fintech startups?

Financial regulations in India set clear rules for licensing, KYC, and data protection. These rules help fintech startups build trust and scale responsibly.

2. What role does the RBI play in fintech innovation?

The RBI creates guidelines for payments, lending, and data storage. This regulatory framework supports fintech innovation while protecting consumers from fraud and hidden fees.

3. Why is data localization important for fintech companies in India?

Data localization rules require companies to store Indian payment data locally. This builds trust and strengthens the country’s digital infrastructure over time.

4. What is a regulatory sandbox in fintech?

A regulatory sandbox lets startups test new financial products under RBI supervision. This helps companies innovate safely before facing full compliance requirements.

5. How will future regulations shape India’s fintech industry?

Future rules will likely address AI-driven lending, CBDC adoption, and open banking. Companies that adapt early will gain a strong competitive advantage.

Also Read:

Why Shoppers Abandon Mobile Carts, and How to Fix It

How to Handle Real-Time Payment Rules? Complete Guide


The Rise of Real-Time Payment Regulations Across the World

How to Handle Real-Time Payment Rules? Complete Guide

The Rise of Real-Time Payment Regulations Across the World

Money now moves faster than ever. A payment that once took days can settle in seconds. This speed has changed how people shop, pay bills, and run businesses.

Governments have taken notice. As instant payments grow, so does the need for rules to protect them. This has led to a wave of real-time payment regulations across the world.

This blog explains why these regulations exist. It also covers how they affect banks, businesses, and consumers. By the end, you will understand this fast-moving area of financial law.

Financial leaders cannot afford to ignore these changes. Whether you run a bank, a fin-tech startup, or a business that accepts payments, new rules will likely touch your operations soon.

Why Real-Time Payments Needed New Rules

Traditional payment systems had built-in delays. These delays gave banks time to catch fraud or reverse mistakes. Real-time payments remove that safety net.

Once money moves, it usually cannot be recalled. This creates new risks for fraud and error. Regulators stepped in to close these gaps and protect users.

Additionally, real-time systems connect many players. Banks, fin-tech firms, and payment networks all work together. Without shared rules, this connection could create weak points. Clear regulations help keep the whole system secure.

Cybercriminals also adapt quickly to new technology. Instant payments give them a narrow window to strike before anyone notices. Regulators respond by requiring stronger identity checks and real-time fraud monitoring across payment networks.

Consumer trust also plays a role. People need confidence that instant payments are safe. Strong rules build that confidence and encourage wider adoption of digital payment tools.

Small businesses depend on this trust too. Many now rely on instant payments for daily cash flow. A single fraud incident without clear recourse could damage their operations severely. Regulation gives these businesses a safety net they can count on.

Regulators also aim to prevent systemic risk. If one part of a connected payment network fails, the effects could spread quickly. Clear rules help contain problems before they threaten the wider financial system.

Key Real-Time Payment Regulations Around the World

Different regions have taken different approaches. The European Union created the Instant Payments Regulation. This law requires banks to offer instant transfers at the same cost as regular transfers.

In the United States, the Federal Reserve launched FedNow. This system supports instant payments across banks. Regulators continue to build rules around fraud prevention and dispute handling for this network.

India has developed strong oversight for its Unified Payments Interface, known as UPI. The Reserve Bank of India monitors transaction limits, fraud controls, and data protection closely.

Meanwhile, countries like Brazil and Australia have introduced similar frameworks. Brazil’s Pix system and Australia’s New Payments Platform both operate under strict regulatory guidelines. These rules cover security, availability, and consumer protection.

As a result, a global pattern is forming. Regulators everywhere are focusing on similar goals: speed, safety, and fairness for users.

Africa is also emerging as a leader in this space. Kenya’s mobile money systems, closely watched by regulators, paved the way for instant payments long before many wealthier nations. Other African nations now study this model closely.

China offers another example worth noting. Its digital payment giants operate under strict government oversight. Regulators there focus heavily on data privacy and anti-money laundering controls within instant payment networks.

The United Kingdom continues refining its Faster Payments system as well. Regulators there recently introduced stricter rules around reimbursing victims of payment fraud, placing more responsibility on banks to protect customers.

Southeast Asian nations, including Singapore and Thailand, have linked their real-time payment systems together. This cross-border integration required careful regulatory coordination between multiple central banks and financial authorities.

How These Regulations Affect Businesses

Businesses that accept payments must follow these new rules closely. Non-compliance can lead to fines or loss of payment access. This makes regulatory awareness essential for finance teams.

Companies must also update their fraud detection systems. Real-time payments leave little room for manual review. Automated tools now need to catch suspicious activity within seconds, not hours.

Furthermore, businesses operating across borders face extra complexity. Each country may have different rules for instant payments. A company selling in multiple regions must track and follow each set of requirements.

On the positive side, compliance often improves trust with customers and partners. Businesses that follow real-time payment regulations well can process payments faster and more reliably. This can become a real competitive advantage.

Reporting requirements add another layer of responsibility. Many regulations require businesses to log transaction data and report suspicious activity within tight deadlines. Building systems that support this reporting takes time and investment.

Vendor selection also shifts under these rules. Businesses often choose payment processors based on their compliance track record. A provider with strong regulatory alignment can reduce a company’s own compliance burden significantly.

Challenges in Enforcing Real-Time Payment Regulations

Enforcement is not always simple. Real-time payments cross borders instantly, but laws are often written for single countries. This mismatch creates gaps that bad actors can exploit.

Regulators also struggle to keep pace with new technology. Payment methods evolve quickly, and rules can lag behind. This forces frequent updates to existing regulations.

Another challenge involves smaller financial institutions. Large banks often have resources to meet complex rules quickly. Smaller banks or fin-tech startups may find compliance costly and difficult to manage.

Despite these hurdles, cooperation between countries is improving. International bodies now share information and best practices. This collaboration helps close gaps and strengthen global payment security.

Legacy systems present a further obstacle. Some banks still run on decades-old infrastructure. Upgrading these systems to meet real-time regulatory standards can take years and significant financial investment.

Consumer education remains an ongoing challenge as well. Many users do not fully understand how instant payments work or what protections apply. Regulators and businesses must work together to close this knowledge gap.

Staffing shortages within regulatory bodies add further strain. Reviewing complex payment systems requires specialized expertise, and many agencies compete for the same limited talent pool of skilled examiners and analysts.

What the Future Holds for Payment Regulation

Experts expect real-time payment regulations to expand further. More countries are building instant payment systems, and rules will likely follow close behind.

Artificial intelligence will also play a bigger role. Regulators may require AI-based fraud detection for all real-time transactions. This could become a standard requirement within the next few years.

Cross-border cooperation is likely to grow too. Shared standards could make international real-time payments smoother and safer. This would benefit businesses that operate globally.

Consumers can expect more protection as well. Future rules may include stronger dispute resolution processes and clearer refund policies for instant payments.

Open banking is another trend likely to intersect with payment regulation. As more countries allow secure data sharing between banks and third parties, regulators will need rules that address both instant payments and open data access together.

Businesses that monitor these trends early will adapt more smoothly. Staying informed through industry groups and regulatory updates can help finance teams prepare well before new rules take effect.

The Rise of Real-Time Payment Regulations Across the World

Conclusion

The rise of real-time payment regulations across the world reflects a fast-changing financial landscape. Instant payments bring speed and convenience, but they also bring new risks.

Regulators have responded with rules focused on safety, fairness, and trust. Businesses must stay informed and compliant to avoid penalties and protect their customers.

Looking ahead, expect these regulations to grow stronger and more connected across borders. Staying prepared today will help businesses thrive in this fast-moving payment environment.

Finance leaders should treat regulatory tracking as an ongoing task, not a one-time project. Rules will keep evolving as instant payments become the default way people move money worldwide.

Frequently Asked Questions

1. What are real-time payment regulations? These are laws and rules that govern instant money transfers, covering fraud prevention, consumer protection, and system security.

2. Why are real-time payment regulations increasing globally? As instant payment systems grow worldwide, governments create rules to manage new risks and protect users from fraud and errors.

3. How do real-time payment regulations affect small businesses? Small businesses must follow compliance rules for fraud detection and data protection, which can require new tools or processes.

4. Which countries have strong real-time payment regulations? The European Union, United States, India, Brazil, and Australia all have well-developed real-time payment regulatory frameworks.

5. Will real-time payment regulations become more unified globally? Experts expect greater cooperation between countries, leading to more shared standards for real-time payment regulations over time.

Also Read:

Why Shoppers Abandon Mobile Carts, and How to Fix It

How Do vCTOs Drive Tech Strategy? A Complete Guide