How Do UPI MDR and Payment Gateway Fees Compare

How Do UPI MDR and Payment Gateway Fees Compare?

UPI MDR vs Payment Gateway Charges: What Will Actually Cost Your Business Less?

Every business that accepts digital payments faces the same question. Should you rely on UPI, a payment gateway, or both? The answer depends heavily on cost. Many business owners assume UPI is always free. Others assume payment gateways are too expensive to bother with. Neither assumption is fully correct.

This guide breaks down UPI MDR and payment gateway charges in simple terms. We will look at how each works, what they actually cost, and which option fits different business types. By the end, you will know exactly where your money goes with each payment method.

What Is UPI MDR and How Does It Work?

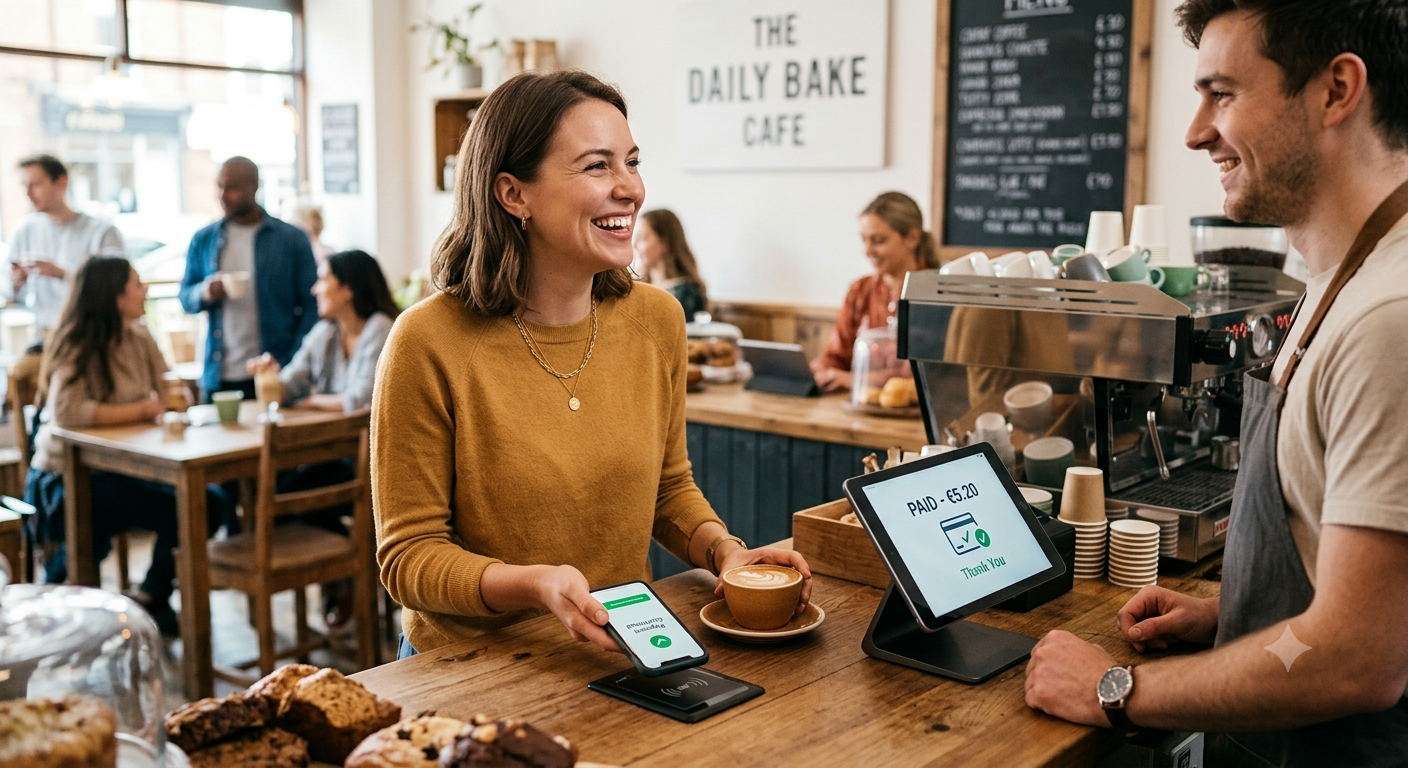
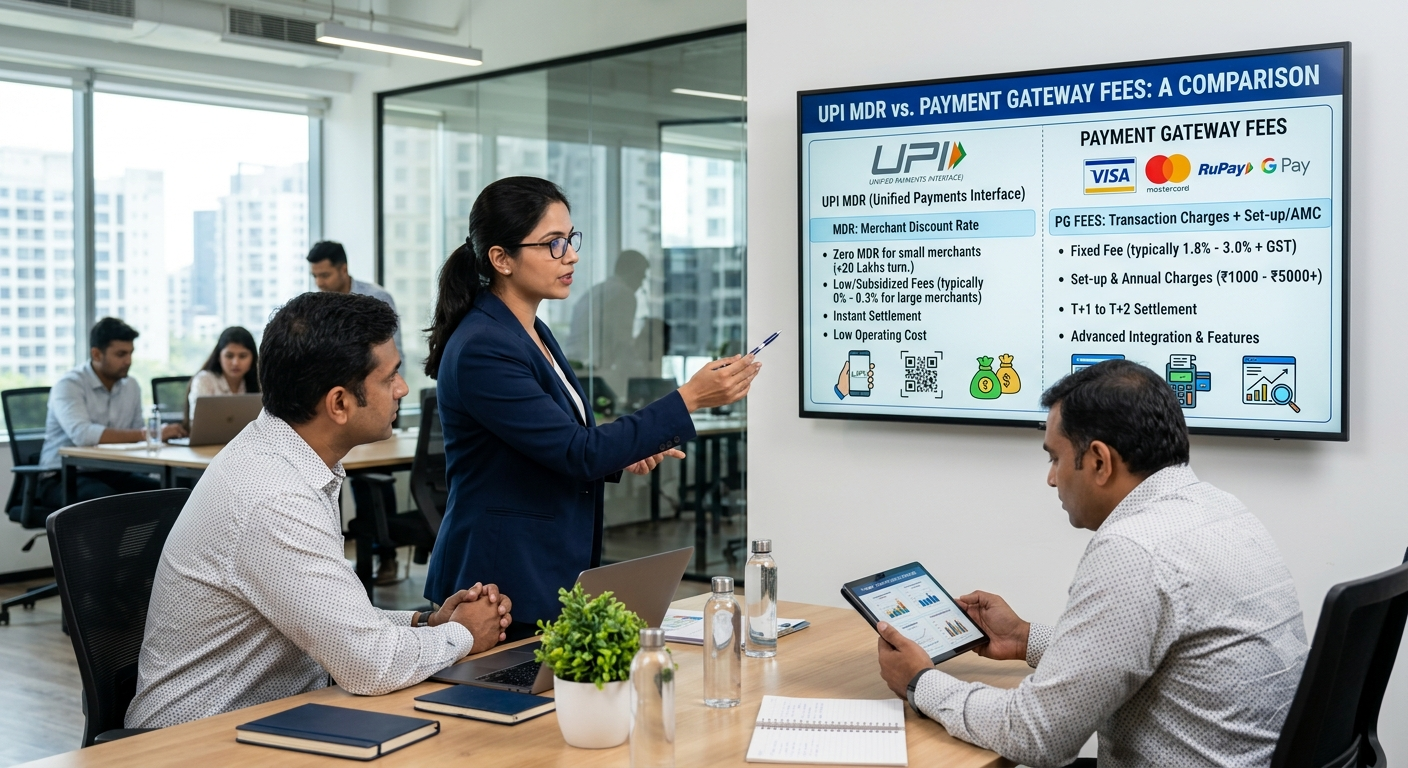
MDR stands for Merchant Discount Rate. It is the fee a merchant pays for accepting a digital payment. For UPI transactions, the Indian government removed MDR on person-to-merchant payments in most cases. This means many small businesses pay zero MDR on UPI transactions today.

However, this rule is not universal. Some UPI transactions above certain thresholds, or made through specific business categories, may still involve charges. Additionally, some payment aggregators add their own service fees even when the base UPI MDR is zero. Therefore, it is important to read your provider’s fee structure closely.

For most small businesses and D2C brands, UPI remains one of the cheapest ways to accept payments. This is especially true for shops, small online stores, and service providers with straightforward transaction volumes. As a result, UPI has become the default payment method for many Indian businesses.

What Are Payment Gateway Charges?

Payment gateways are third-party services that let businesses accept multiple payment types. This includes credit cards, debit cards, net banking, and wallets. Unlike UPI, payment gateways almost always charge a fee. This fee typically ranges from 1.5% to 3% per transaction, depending on the provider and payment method.

Gateway charges often include additional costs too. These can include setup fees, monthly maintenance charges, or fees for international transactions. Consequently, businesses that rely heavily on card payments may see higher overall costs compared to UPI-only setups.

However, payment gateways offer something UPI alone cannot: flexibility. They let customers pay using their preferred method, which can improve conversion rates. For enterprise businesses and online stores with diverse customer bases, this flexibility often justifies the extra cost.

Comparing the Real Costs for Different Business Types in payment gateway

Small businesses and startups with tight margins often benefit most from UPI’s low or zero MDR. If most of your customers already use UPI apps, there is little reason to pay extra gateway fees just for that channel. This keeps more revenue in your business.

In contrast, e-commerce businesses and SaaS companies with larger, more diverse customer bases may need payment gateways regardless of cost. Customers expect multiple payment options at checkout. Losing a sale because a preferred payment method is missing often costs more than the gateway fee itself.

Enterprise businesses typically use both. They accept UPI directly for cost savings on high-volume, low-friction transactions. Meanwhile, they use payment gateways to capture card payments, international customers, and subscription billing. This hybrid approach balances cost control with customer convenience.

It is also worth noting that some payment gateways now include UPI as one of their supported methods. In these cases, transaction costs may vary depending on whether the gateway charges its own fee on top of the UPI transaction. Comparing provider-specific pricing sheets remains essential before committing.

How to Choose the Right Setup for Your Business with right payment gateway

Start by reviewing your customer payment preferences. If most transactions already happen through UPI apps, prioritize direct UPI integration to minimize fees. This works well for local retail, service businesses, and small D2C brands.

Next, evaluate your growth plans. Businesses expecting international customers or subscription models will likely need a payment gateway regardless of UPI’s cost advantage. In this case, focus on comparing gateway providers based on transparent pricing rather than lowest advertised rates.

Finally, calculate your blended cost. Add up your transaction volume across payment types and estimate monthly fees under each setup. This number matters more than any single percentage rate. A gateway with slightly higher fees but better conversion rates might still save you money overall.

Marketing managers and finance teams should collaborate here. Marketing understands customer payment preferences. Finance understands the real cost impact. Together, they can choose a setup that supports both sales and margins.

Common Mistakes Businesses Make by payment gateway

Many businesses focus only on the headline fee percentage. However, hidden costs like settlement delays, chargebacks, and integration fees often matter more over time. Always request a full fee breakdown before signing with any provider.

Another common mistake is ignoring customer experience. A cheaper payment option that frustrates customers can cost more in lost sales than a slightly pricier, smoother checkout process. Balancing cost with usability leads to better long-term results.

Conclusion

UPI MDR and payment gateway charges each serve different business needs. UPI often costs less for straightforward, high-volume domestic transactions. Payment gateways offer flexibility that many growing businesses still need. The smartest approach usually combines both, based on your customer base and transaction patterns. Reviewing your actual costs regularly ensures you keep more of what you earn.
How Do UPI MDR and Payment Gateway Fees Compare

Frequently Asked Questions

1. Is UPI MDR always zero for merchants? For most person-to-merchant UPI transactions, MDR is currently zero, though some categories and aggregator fees may still apply.

2. Do payment gateways always charge more than UPI? Generally yes, since gateways support multiple payment types and typically charge between 1.5% and 3% per transaction.

3. Can a business use both UPI and a payment gateway together? Yes, many businesses combine both to reduce costs on UPI transactions while offering flexibility through gateway-supported methods.

4. What hidden costs should I check before choosing a gateway? Look for setup fees, monthly charges, chargeback fees, and international transaction surcharges beyond the base MDR.

5. Which option is better for a small business? Small businesses with mostly local, UPI-based customers usually save more by prioritizing direct UPI integration first.

Also Read:

How Do You Handle CTO Transitions Without Friction? Ultimate Guide

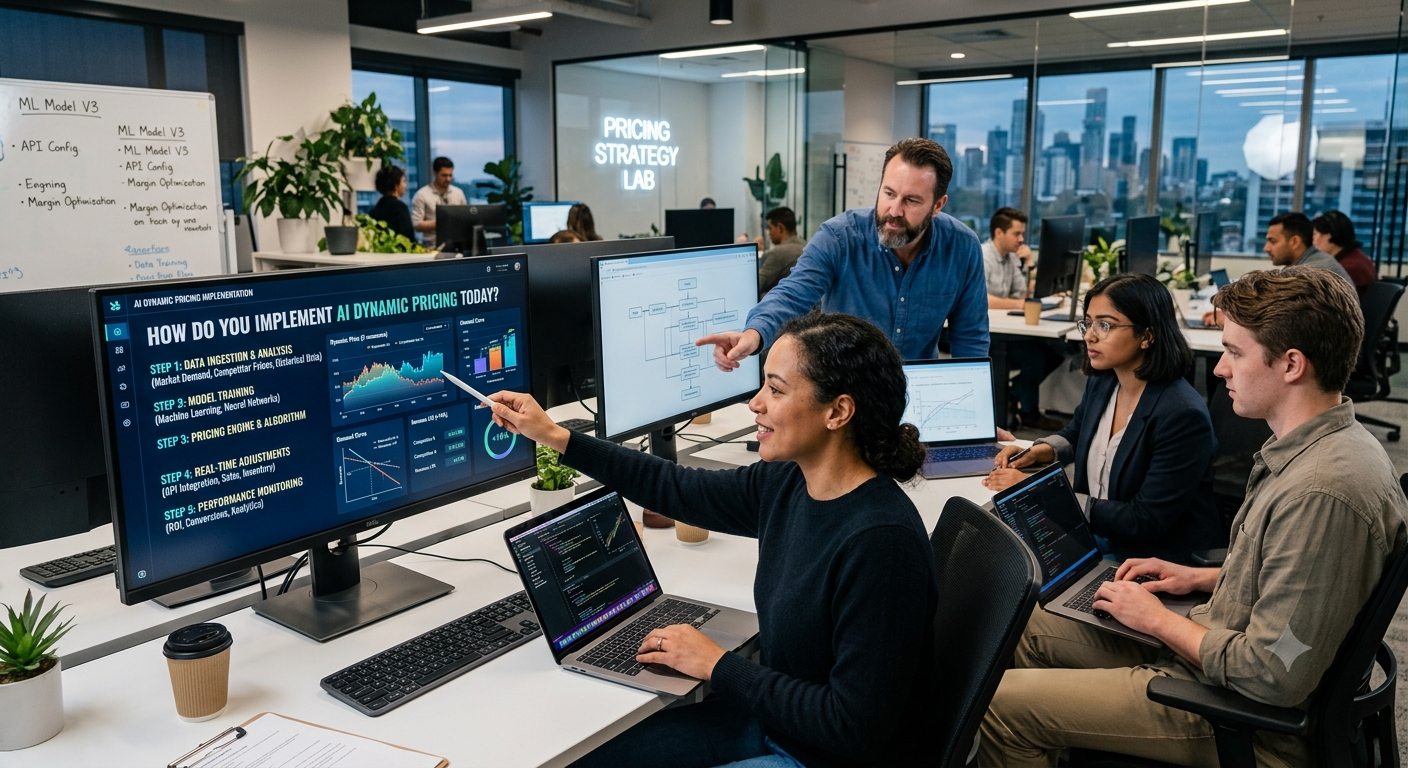
How Do You Implement AI Dynamic Pricing Today? Ultimate Guide
How Do You Handle CTO Transitions Without Friction

How Do You Handle CTO Transitions Without Friction? Ultimate Guide

When Your Co-Founder CTO Steps Down: Maintaining Product Momentum During Executive Technology Transitions

Losing a technical co-founder is one of the hardest moments a startup can face. The CTO often holds deep product knowledge, technical vision, and team trust. When they step down, uncertainty spreads quickly.

However, this moment does not have to derail your company. With the right approach, founders can maintain product momentum and keep the team focused. This guide explains how to manage a co-founder CTO transition without losing direction.

We will cover communication, technical continuity, and rebuilding confidence across your team and stakeholders.

Why CTO Transitions Feel So Disruptive

A co-founder CTO is not just an employee. They often carry unwritten knowledge about the codebase, architecture decisions, and product history. This makes their exit feel especially disruptive.

Engineering teams may worry about direction. Without clear leadership, priorities can become unclear, slowing down development significantly. Meanwhile, other departments may question the company’s overall stability.

Investors also pay close attention to leadership changes. A sudden CTO exit can raise concerns about internal conflict or company health, even when the departure is amicable. Managing this perception carefully matters just as much as managing the technical transition.

Customers, too, may notice delays if product releases slow down. Therefore, addressing the transition quickly and transparently helps protect relationships across every stakeholder group.

Immediate Steps After a Co-Founder CTO Steps Down

The first priority is communication. Inform your engineering team directly and honestly. Avoid vague statements that create more questions than answers.

Next, identify an interim technical leader immediately. This could be a senior engineer, another co-founder, or an external advisor. Having someone visible in charge prevents confusion during the transition period.

Document critical technical knowledge as soon as possible. Schedule sessions with the departing CTO, if possible, to capture architecture decisions, system dependencies, and ongoing project details before they leave.

Review your product roadmap next. Some projects may need to pause temporarily while priorities are reassessed. Being honest about short-term delays is better than overpromising and missing deadlines later.

Finally, communicate with investors proactively. A clear, confident explanation of your transition plan reassures stakeholders far more than silence or delayed updates.

Maintaining Product Momentum During the Transition in CTO

Momentum is easy to lose during leadership gaps. To prevent this, focus on smaller, achievable milestones instead of large, complex projects during the transition period.

Empower your engineering team to make decisions within clear boundaries. Micromanaging during uncertainty often slows progress further. Instead, trust your team’s expertise while providing clear priorities.

Consider bringing in a fractional or interim CTO if the transition will take time. This provides technical guidance without rushing a permanent hiring decision under pressure.

Regular check-ins help maintain visibility into progress. Weekly updates, even brief ones, keep everyone aligned and reduce uncertainty about project status.

It also helps to celebrate small wins publicly during this period. Highlighting completed features or resolved issues reassures the team that progress continues despite the leadership change.

Finding the Right Long-Term Technical Leadership in CTO

Rushing to hire a permanent CTO often leads to poor fit. Instead, take time to clearly define what your company needs from its next technical leader.

Consider whether you need someone focused on scaling infrastructure, building new products, or managing a growing engineering team. These are very different skill sets, and clarity here prevents costly hiring mistakes.

Involve your engineering team in the hiring process where appropriate. Their input helps identify candidates who will fit well within existing team culture and technical practices.

External advisors or board members can also provide valuable guidance during this search. Their outside perspective often helps founders avoid rushed decisions driven by short-term pressure.

Once you find the right candidate, plan a thoughtful onboarding process. Introduce them properly to the team, existing systems, and ongoing projects to set them up for success from day one.

Rebuilding Team and Stakeholder Confidence

Trust takes time to rebuild after a major leadership change. Consistent, transparent communication is the most effective tool founders have during this period.

Share regular updates about progress, even when there is no major news to report. Silence often creates more anxiety than honest, incremental updates.

Recognize the emotional impact on your team as well. A co-founder leaving can feel personal, even for employees who were not close to them directly. Acknowledging this openly shows strong, empathetic leadership.

With investors, focus on demonstrating continued execution. Hitting product milestones, even small ones, proves that the company remains stable and capable despite the transition.

Over time, consistent delivery rebuilds confidence more effectively than any single announcement or reassurance ever could.

Protecting Engineering Culture Through the Change

Engineering culture often reflects the personality of its technical founder. When that person leaves, culture can shift in subtle but important ways.

Pay attention to team rituals that mattered under the previous leadership. Code review practices, planning meetings, and communication norms often carry the departing CTO’s influence. Decide deliberately which practices to keep and which may need adjustment.

Involve senior engineers in preserving what worked well. They often understand the day-to-day culture better than founders who are less involved in technical details. Their input helps maintain continuity even as leadership changes.

At the same time, avoid forcing every practice to stay exactly the same. New leadership, even interim leadership, may bring valuable improvements. Balance respect for existing culture with openness to healthy evolution.

Clear documentation also protects culture during transitions. Written guidelines on coding standards, deployment processes, and team norms reduce reliance on any single person’s institutional memory going forward.

Learning from Companies That Handled This Well

Many successful companies have navigated co-founder CTO transitions without losing momentum. A common thread among them is early, proactive planning rather than reactive scrambling.

These companies often maintain detailed technical documentation continuously, not just during a crisis. This habit alone significantly reduces the disruption caused by any sudden leadership change.

They also tend to build strong second-tier technical leadership early. Senior engineers who can step up temporarily provide a natural safety net during unexpected transitions.

Clear, calm communication during the actual transition period is another shared trait. Founders who address concerns directly, rather than avoiding difficult conversations, tend to retain team trust more effectively.

Finally, these companies treat the transition as a growth opportunity rather than purely a setback. New leadership sometimes brings fresh perspective that strengthens the product and team culture over time.

How Do You Handle CTO Transitions Without Friction

Conclusion

A co-founder CTO stepping down is undoubtedly challenging, but it does not have to derail your company’s progress. Clear communication, strong interim leadership, and a thoughtful hiring process can help maintain product momentum throughout the transition.

Focus on transparency with your team, investors, and customers. With the right approach, your company can emerge from this transition stronger and more resilient than before.

Frequently Asked Questions

1. What should founders do immediately after a co-founder CTO leaves? Communicate honestly with the team, appoint interim technical leadership, and document critical technical knowledge before the transition is complete.

2. Should we rush to hire a new CTO? No. Taking time to define your exact needs leads to better long-term hiring decisions than rushing under pressure.

3. How do we maintain investor confidence during a CTO transition? Proactive, transparent communication and continued product execution help maintain investor trust during leadership changes.

4. Can an interim CTO help during this period? Yes, a fractional or interim CTO can provide technical guidance while you search for a permanent replacement.

5. How long does a typical CTO transition take? This varies widely, but most startups need several months to fully stabilize leadership and hire the right long-term replacement.

Also Read:

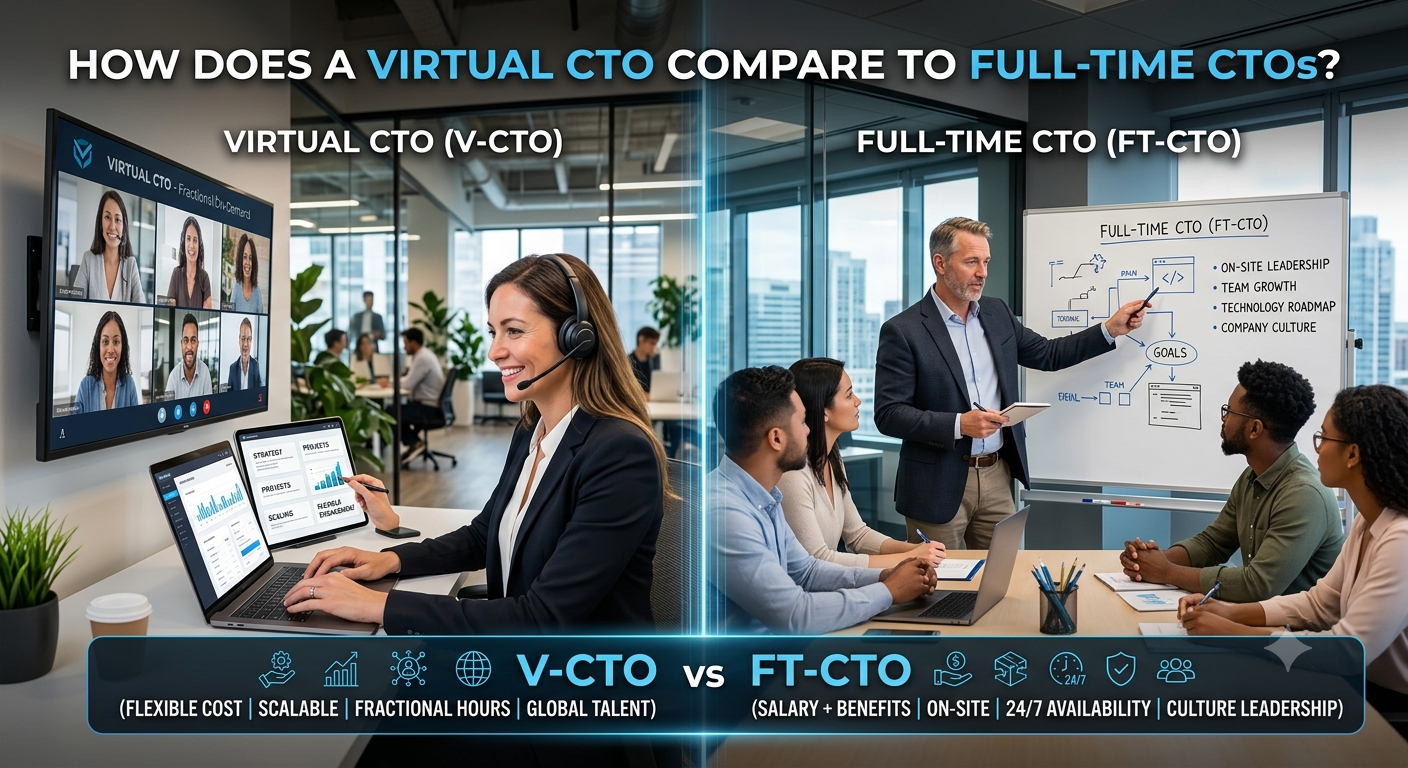
How Does a Virtual CTO Compare to Full-Time CTOs? Ultimate Guide

How Do You Implement AI Dynamic Pricing Today? Ultimate Guide
How Does a Virtual CTO Compare to Full-Time CTOs

How Does a Virtual CTO Compare to Full-Time CTOs? Ultimate Guide

Virtual CTO for FinTech Startups: Architecting Banking API Integrations With Zero Downtime

Fintech founders face a tough puzzle. You must launch fast, stay secure, and never let payments fail. Yet many startups cannot afford a full-time chief technology officer. Therefore, a virtual CTO for fintech startups can be a smart answer. This expert guides your technology plan on a flexible basis. One of the hardest tasks is connecting to banks through APIs without any downtime. This guide explains how a virtual CTO approaches that job. You will also learn the design habits that keep money moving.

What Is a Virtual CTO for FinTech Startups?

A virtual CTO is a senior technology leader who works with you part time or on contract. Some people call this role a fractional CTO. The person sets your tech strategy, guides your engineers, and reviews key choices. You pay only for the time you need. That makes the model a smart fit for early-stage teams.

Fintech adds special pressure to this role. Your product handles real money and sensitive data. Regulators watch closely, and customers lose trust fast after an outage. A virtual CTO who knows fintech understands these risks. They bring experience from many projects, so you avoid common traps.

Typical duties are broad. They pick the tech stack and design the system architecture. They set security standards and plan for compliance rules such as PCI DSS. Hiring and coaching developers is part of the job too. Most of all, they connect tech choices to business goals.

Compare this with a full-time CTO. A full-time hire costs more and may take months to find. A virtual CTO can start within weeks. As your company grows, you can move to a full-time leader with a clean plan already in place.

Consider a small payments startup with five engineers. The team knows how to build features but lacks bank experience. A virtual CTO reviews the plan, spots weak points, and sets clear standards. Developers gain confidence, and the founder gains a trusted adviser. Moreover, investors like to see this level of technical care.

Why Banking API Integrations Are Hard

Banking APIs let your app talk to banks and payment networks. They power account checks, payments, and balance data. Open banking rules in many regions make these APIs more common. However, each bank works differently. Formats, limits, and rules vary widely.

Banks also change systems without much warning. An API may slow down, return odd errors, or go offline for maintenance. Your product must handle all of this smoothly. A single weak link can freeze payments for thousands of users.

Security adds more weight. You must protect tokens, keys, and customer data at every step. Rules require strong authentication and careful logging. Mistakes can lead to fines and lost trust.

For these reasons, integration cannot be an afterthought. It needs a clear architecture from day one. That is exactly where a virtual CTO adds value.

Cost is another factor. Every hour of downtime can mean failed payments and angry customers. Support tickets rise, and partners start to worry. Additionally, repeated outages may put your bank relationship at risk. Prevention is always cheaper than recovery, and it keeps your team calm.

How a Virtual CTO Designs for Zero Downtime

Zero downtime means your service stays available even when parts fail or change. No system is perfect, but good design gets very close. Here are the core ideas a virtual CTO uses.

Build a Clean API Gateway Layer

A gateway sits between your app and every bank API. Your core product talks only to the gateway. The gateway handles each bank’s format, rules, and quirks. If a bank changes something, you fix one place instead of many. This also makes adding new banks much faster.

Use Retries, Timeouts, and Circuit Breakers

Networks fail often, so plan for that. Smart retries try again after a short pause. Timeouts stop your system from waiting forever. A circuit breaker cuts off a failing service for a moment so it cannot drag everything down. Together, these tools keep small problems small.

Make Payments Safe to Repeat

However, retries can cause double payments if you are careless. The fix is called idempotency. Each payment request carries a unique key. If the same request arrives twice, the system processes it only once. This protects customers and your reputation.

Add Backup Routes and Queues

Never depend on one bank connection for critical flows. A backup provider can take over when the main one fails. Message queues store requests safely during a slowdown. As a result, work continues once the service recovers. Customers see a short delay instead of an error.

Data consistency deserves attention too. When a payment moves between systems, every record must match. Reconciliation jobs compare your ledger with bank statements each day. Any gap triggers an alert. This habit catches quiet errors before customers notice them.

Release Without Stopping the Service

Deployments often cause outages. Blue-green deployment avoids this. You run the new version next to the old one and switch traffic only after tests pass. If something breaks, you switch back in seconds. Feature flags let you turn new code on for a few users first.

Testing, Monitoring, and Compliance

However, design alone is not enough. Teams must test and watch the system all the time. A virtual CTO builds these habits into your culture.

Start with sandbox testing. For example, most banks offer test environments. Run real scenarios there, including failures and slow responses. Load tests show how your system behaves at peak traffic. Chaos tests, which break parts on purpose, reveal hidden weak spots.

Monitoring comes next. Track response times, error rates, and payment success rates. Set alerts that reach the right person quickly, day or night. Dashboards should show the health of every bank connection at a glance. Clear logs help your team find causes in minutes, not hours.

Meanwhile, compliance needs equal care. Encrypt data in transit and at rest. Limit access with roles and strong authentication. Keep audit trails for every payment action. Plan regular security reviews and penetration tests. These steps satisfy regulators and calm nervous partners.

Finally, prepare for incidents. Write a simple runbook that explains who does what during an outage. Practice it with your team. After each incident, hold a blameless review and fix the root cause. Over time, your platform becomes tougher and easier to trust.

How to Work With a Virtual CTO for FinTech Startups

Set clear goals before you start. Do you need an architecture plan, a team review, or a compliance roadmap? Agree on deliverables and a schedule. Decide how you will measure success after three months. Ask for regular reports in plain language.

Look for real fintech experience. Ask about past banking API projects and how they handled outages. Check references and past results. Ask to see sample architecture notes or reports. A good virtual CTO explains complex ideas simply and listens to your business needs.

Treat the relationship as a partnership. Give access to your team, your data, and your roadmap. Involve your developers in decisions so knowledge stays in-house. Review progress each month. The best outcome is a stronger internal team that can run without constant outside help.

Conclusion: Keep Payments Running With the Right Tech Leadership

A virtual CTO for fintech startups gives you expert leadership without the cost of a full-time hire. Clean gateways, safe retries, backup routes, and careful releases help banking API integrations run with zero downtime. Strong testing, monitoring, and compliance make the system even more reliable. If your startup is growing fast, now is a great time to get expert guidance. Solid technology today protects your customers and your future. Take the first step by reviewing where your current integrations might fail.

How Does a Virtual CTO Compare to Full-Time CTOs

Frequently Asked Questions

What does a virtual CTO for fintech startups do?

A virtual CTO sets technology strategy, designs architecture, and guides engineers on a part-time basis. In fintech, they also focus on security, compliance, and banking API integration.

How is a virtual CTO different from a full-time CTO?

A virtual CTO works flexibly and costs less. A full-time CTO is embedded daily in your company. Many startups begin with virtual leadership and hire full-time later.

How can banking API integrations have zero downtime?

Use a gateway layer, retries, circuit breakers, backup providers, and blue-green releases. Add strong monitoring so problems are caught early.

When should a fintech startup hire a virtual CTO?

Hire one when you plan your first product build, prepare for a bank partnership, or face scaling problems. Early guidance prevents costly rework.

What is idempotency in payment APIs?

Idempotency means the same request gives the same result, even if sent twice. It stops duplicate charges when a retry happens.

Also Read:

How Do You Implement AI Dynamic Pricing Today? Ultimate Guide
How Do Modern Brands Manage B2B Payments? Ultimate Guide

How Do You Implement AI Dynamic Pricing Today

How Do You Implement AI Dynamic Pricing Today? Ultimate Guide
Why AI-Driven Dynamic Pricing Needs Payments

Prices no longer stay fixed for long. Demand shifts by the hour, and rivals change their offers all day. Static price lists cannot keep up with this pace. AI-driven dynamic pricing solves the problem by adjusting prices in real time.

However, a smart price means little if checkout fails to honor it. That is why payment integration matters so much. This article shows how to link pricing AI with your payment systems. It helps e-commerce brands, fintech teams, and SaaS founders. You will learn the setup, the risks, and the steps to start.

What Is AI-Driven Dynamic Pricing?

Dynamic pricing means changing prices based on market signals. Airlines and ride apps have used it for years. AI now brings the same power to any online business. The models learn from your data and improve over time.

Signals That Feed Pricing Algorithms

A good model studies many inputs at once. These include demand, stock levels, competitor prices, and seasonality. Customer behavior, such as browsing and cart activity, is reviewed as well. Some models track price elasticity, which shows how sales change when the price moves.

Payment data adds a strong extra layer of insight. It shows what customers actually pay, not just what they view. Consequently, the model learns real willingness to pay.

Dynamic Pricing vs. Rule-Based Pricing

Rule-based tools follow fixed if-then logic. A typical rule says to cut the price ten percent when stock is high. Such rules are simple but rigid. AI models test many factors together and find patterns that humans miss.

They also react faster. A rule may update once a day, while an AI model can update within minutes. That speed protects your margins and wins more sales.

Why Businesses Adopt AI-Driven Dynamic Pricing

Margins are thin in most online markets. A one percent gain in price can lift profit far more than a one percent gain in volume. Smart pricing helps you find that gain without guessing.

It also saves time. Manual price checks across thousands of products are slow and error-prone. Automated engines handle the work around the clock. Your team can then focus on strategy, not spreadsheets.

Why Payment Systems Are the Missing Link

Many pricing tools stop at the product page. The price changes, but the payment layer knows nothing about it. This gap causes real problems. Customers see one price and get charged another. Trust falls fast when that happens.

Integration closes the loop. The pricing engine sends the final price to the payment gateway. The gateway confirms the charge in real time. Then the result flows back to the model as fresh data.

Benefits of Payment Data in Pricing Models

Payment data reveals useful truths. It shows which payment methods convert best and where customers abandon checkout. Refund and chargeback patterns become visible by price band.

With these insights, you can tune prices by segment. You can offer smart rewards for cheaper payment methods. For instance, a small discount for bank transfers can cut card fees.

Fraud and Risk Signals

Payment systems already score fraud risk on every order. Sharing these scores with the pricing engine is valuable. A high-risk order may need a different checkout flow. Trusted repeat buyers, meanwhile, may deserve loyalty prices.

Keep the two goals separate, though. Pricing should never punish people unfairly. Risk data should protect revenue, not overcharge customers.

How to Integrate Dynamic Pricing With Payment Gateways

The setup needs care. Here is a simple path that many teams follow.

Step 1: Map Your Data Sources

Every system that touches price should be listed. Include your catalog, inventory, CRM, analytics, and payment gateway. Note where each one holds data and how often it updates. Clean and connected data is the base of good pricing.

Step 2: Use APIs and Webhooks

An API is a doorway between two software tools. A webhook is an alert that one system sends to another. Use both. The pricing engine calls the API to set the price. The gateway then sends webhooks when payments succeed or fail.

Most modern gateways support this pattern. Check for real-time endpoints and clear rate limits. Test how the system behaves during traffic spikes.

Step 3: Lock the Price at Checkout

Never let prices change in the middle of a payment. Create a price quote with a short expiry, such as ten minutes. The quote should be stored against the cart. The gateway must then charge exactly that amount. As a result, customers see no surprises.

Step 4: Handle Currency, Tax, and Fees

Global stores face extra layers. Prices may vary by currency and tax rule. Payment fees also differ by method. These costs should be built into the price logic from day one. Otherwise, margins can shrink without warning.

Step 5: Set Price Floors and Ceilings

Give the AI firm limits. A floor keeps you above cost. A ceiling protects your brand from extreme jumps. Add change limits per hour to stop wild swings. Guardrails keep smart tools safe.

Real-World Use Cases for Payment-Linked Pricing

Online stores use the model to adjust prices during sales and stock shortages. A fashion brand can trim prices on slow items while holding firm on best sellers. Payment data shows which discounts truly convert into paid orders.

SaaS companies apply the same idea to subscription plans and usage fees. Fintech firms use it to set fees based on transaction size and risk. Travel and event sellers raise or lower prices as seats fill. In each case, the checkout must confirm the exact price the customer saw.

Marketplaces gain too. Sellers get pricing suggestions that match demand, and the payment layer settles funds correctly. This builds trust on both sides of the platform.

Best Practices, Risks, and Compliance

Dynamic pricing can backfire without care. Customers dislike feeling tricked. Unfair practices are watched closely by regulators.

Keep Pricing Fair and Transparent

Avoid pricing based on personal traits. Sensitive data such as health or ethnicity should never be used. Explain price changes in simple terms when asked. Offer loyalty and volume rewards that customers can see. Fairness builds long-term trust.

Protect Payment Data

PCI DSS, the global card security standard, must be followed. Raw card numbers should never be stored in the pricing engine. Tokens are used instead. Encrypt data in transit and at rest. Vendor security should be reviewed often.

Test Before You Scale

Start with A/B tests on a small product group. Compare revenue, conversion, and refund rates. Each test should run for at least two full weeks. Then expand to more products. A human reviewer should stay in the loop for major changes.

Common Mistakes to Avoid

Many teams launch too fast. Some skip price limits and watch margins collapse. Others ignore taxes and fees inside the model. A few forget mobile checkout, where prices often lag. These gaps should be fixed before you scale.

Choose the Right Tools

Look for a pricing engine with open APIs and strong analytics. Confirm that it works with your payment gateway and orchestration layer. Ask how quickly it can push a new price to checkout. Request a sandbox so your team can test safely.

Measure What Matters

Track revenue per visitor, conversion rate, margin, and checkout success rate. Watch customer complaints closely. If trust metrics fall, slow down. Smart pricing should raise profit without hurting loyalty.

Conclusion: Make Pricing and Payments Work as One

AI-driven dynamic pricing helps you respond to the market in real time. Payment integration makes those prices reliable at checkout. Together, they raise revenue, cut friction, and improve decisions. However, success needs clean data, firm guardrails, and fair rules.

Start small with one product line. Pilot results should be shared with finance, product, and support teams. Connect your gateway, lock prices at checkout, and test carefully. Then scale what works. Ready to lead in payments and pricing innovation?

How Do You Implement AI Dynamic Pricing Today

Frequently Asked Questions

1. What is AI-driven dynamic pricing?

It is a method where AI changes prices automatically using live data. Live inputs include demand, stock, competitor prices, and customer behavior. Better revenue and margins are the goal.

2. How does dynamic pricing connect to a payment gateway?

The pricing engine sends the approved price through an API. The gateway charges that exact amount and returns the result. Webhooks then feed payment outcomes back to the model.

3. Is dynamic pricing legal?

It is legal in most regions when it is fair and transparent. Rules against discrimination and deceptive pricing still apply. Check local laws and get legal advice before launch.

4. Which businesses benefit most from real-time pricing?

E-commerce stores, travel firms, SaaS companies, and marketplaces gain the most. Any business with changing demand or limited stock can benefit.

5. How can I avoid upsetting customers?

Set price limits, avoid sudden large jumps, and explain your pricing logic. Reward loyal buyers. Monitor complaints and adjust quickly.

Also Read:

How Do Invisible Payments Boost Customer Joy? Ultimate Guide

How Do Modern Brands Manage B2B Payments? Ultimate Guide

How Do Invisible Payments Boost Customer Joy

How Do Invisible Payments Boost Customer Joy? Ultimate Guide

Invisible Payments: The Rise of Pay Without Checkout Experiences

Introduction

Imagine leaving a store without scanning a single item. No line, no card swipe, no waiting. This is the idea behind invisible payments. These systems let customers pay without checkout, using sensors, apps, or stored payment details. Furthermore, this trend is growing fast across retail, transportation, and food service. Businesses are adopting invisible payments to reduce friction and boost customer satisfaction. In this article, we explore how invisible payments work. We will also look at their benefits, challenges, and future potential. Whether you run a store or simply enjoy smoother shopping, this guide has useful insights for you.

Main Section 1: What Are Invisible Payments?

Invisible payments remove the traditional checkout step entirely. Customers link their payment method to an app or account beforehand. Then, sensors or scanners detect what they take or use. Payment happens automatically in the background. As a result, there is no register, no line, and no manual transaction.

This concept already exists in several familiar forms. Ride-sharing apps charge riders automatically after each trip. Similarly, some grocery stores use camera systems to track purchases. Toll roads have used similar technology for years through automatic vehicle scanning. Each example shares one goal: removing friction from the payment moment.

Invisible payments rely on a mix of technologies. These include mobile apps, RFID tags, computer vision, and secure cloud accounts. Consequently, the customer experience feels almost magical. However, strong technology and data security work behind the scenes to make it possible.

Main Section 2: Why Invisible Payments Are Growing So Quickly

Consumer expectations have shifted dramatically in recent years. People want speed and simplicity in every transaction. Long checkout lines feel outdated compared to instant digital experiences. Therefore, businesses are racing to remove this pain point.

Mobile technology has also matured significantly. Most customers now carry smartphones with secure payment apps installed. This makes background payments easier to implement safely. Meanwhile, advances in computer vision and sensor technology have dropped in cost. This allows more businesses to afford invisible payment systems.

Additionally, the pandemic accelerated contactless payment adoption worldwide. Many customers now prefer minimal physical interaction during purchases. Invisible payments take this preference one step further. There is no card tap and no manual entry required at all.

Retailers also benefit financially from faster transactions. Shorter wait times often lead to higher customer satisfaction scores. In turn, satisfied customers tend to spend more and return more often. This creates a strong business case for adopting invisible payment technology.

Main Section 3: Real-World Examples of Pay Without Checkout

Several industries already use invisible payment models successfully. Cashierless convenience stores let shoppers grab items and simply walk out. Cameras and weight sensors track every item automatically. Payment then processes through the customer’s linked account.

Ride-hailing and food delivery apps offer another clear example. Users never exchange cash or cards during their trip or order. Instead, payment happens instantly once the service is complete. This model has become the standard across most delivery platforms today.

Public transportation systems have also embraced invisible payments. Contactless transit cards and tap-to-ride systems reduce boarding delays. Some cities are even testing facial recognition for fare collection. Similarly, smart parking systems now charge drivers automatically upon exit.

Hotels and gyms are exploring similar technology too. Guests can access rooms and pay for extra services without visiting a front desk. As these examples show, invisible payments extend far beyond retail stores.

Main Section 4: Challenges and Considerations for Businesses

Despite clear benefits, invisible payments come with real challenges. Security remains the top concern for most businesses and customers. Storing payment details requires strong encryption and fraud protection systems. Without proper safeguards, businesses risk data breaches and customer trust loss.

Privacy is another important consideration. Camera-based tracking systems collect detailed shopper behavior data. Consequently, businesses must clearly explain how this data gets used. Transparent privacy policies help build customer confidence in these systems.

Implementation costs can also be significant. Sensors, cameras, and software integration require upfront investment. Smaller businesses may need to start with simpler versions of this technology. For example, app-based payment systems cost less than full computer vision setups.

Employee training matters as well. Staff need to understand new systems and assist customers during the transition period. Meanwhile, businesses should plan for occasional technical issues. Backup payment options should always remain available for reliability.

Finally, customer education plays a key role in adoption. Some shoppers may feel hesitant about automatic payments at first. Clear signage and simple onboarding can ease this concern effectively.

Conclusion

Invisible payments are reshaping how customers experience transactions everywhere. From cashierless stores to automatic ride payments, checkout-free experiences are becoming common. Businesses that adopt this technology thoughtfully can boost speed and satisfaction. However, success requires strong security, clear privacy practices, and proper customer education. As technology continues advancing, invisible payments will likely become the new standard. Companies that prepare today will lead this shift tomorrow.

How Do Invisible Payments Boost Customer Joy

Frequently Asked Questions

1. What are invisible payments?

Invisible payments let customers complete purchases without a traditional checkout. Sensors or apps handle the transaction automatically in the background.

2. Are invisible payments safe to use?

Yes, when businesses use strong encryption and fraud protection. Security measures protect customer data throughout every transaction.

3. Which industries use invisible payments today?

Retail, transportation, food delivery, and hospitality industries already use invisible payment systems successfully.

4. Do invisible payments require a smartphone?

Most invisible payment systems use a smartphone app or linked account. However, some use cameras or sensors instead.

5. Will invisible payments replace traditional checkout completely?

Not entirely, but adoption is growing quickly. Many businesses will likely offer both options for years to come.

Also Read:

How Do Invisible Payments Work in Real Life? Ultimate Guide

How Do Modern Brands Manage B2B Payments? Ultimate Guide

How Do Invisible Payments Work in Real Life

How Do Invisible Payments Work in Real Life? Ultimate Guide

Invisible Payments: The Rise of Pay Without Checkout Experiences

Introduction

Imagine leaving a store without ever opening your wallet. No cards, no scanning, no waiting in line. This is the promise of invisible payments. Also known as pay without checkout, this technology is changing how people shop and pay. Retailers, app developers, and business owners are all paying close attention. In this blog, we explore how invisible payments work, why they matter, and what your business needs to know. You will also learn practical steps to prepare for this shift. By the end, you will understand why checkout-free shopping is becoming the new normal.

What Are Invisible Payments and How Do They Work

Invisible payments remove the traditional checkout step from a purchase. Instead of swiping a card, sensors and apps handle payment automatically. For example, Amazon Go stores use cameras and sensors to track what you pick up. When you leave, your account gets charged automatically. This is a clear example of pay without checkout in action.

Behind the scenes, invisible payments rely on a few key technologies. These include mobile apps, biometric identification, and IoT sensors. Together, they confirm your identity and process payment without manual input. As a result, the entire shopping experience feels faster and more seamless. Customers no longer need to stand in line or fumble for a card.

A Quick Look at How the Process Flows

First, a customer links their payment method to an app or account. Next, sensors or cameras track their movement and item selection. Finally, the system calculates the total and charges the account automatically. The customer simply walks away once finished. This short sequence explains why the experience feels almost instant to most shoppers.

This technology is not limited to physical stores. Ride-sharing apps like Uber also use invisible payments. You get out of the car, and the app charges your account instantly. Similarly, some restaurants now offer pay without checkout through table-based apps. These examples show how widespread this trend has already become.

The Core Technologies Powering Invisible Payments

Biometric authentication plays a growing role in these systems. Fingerprints, facial recognition, and palm scans confirm identity in seconds. Meanwhile, mobile wallets store payment details securely for quick access. Together, these tools remove the need for physical cards entirely.

Cloud computing also supports invisible payments behind the scenes. It processes transactions quickly, even during busy shopping hours. Additionally, machine learning helps systems detect fraud in real time. This combination of technologies makes pay without checkout both fast and secure for most users.

Why Businesses Are Adopting Pay Without Checkout Models

Businesses adopt invisible payments for several strong reasons. First, they improve the customer experience significantly. Shoppers value speed and convenience above almost everything else. When checkout lines disappear, satisfaction scores tend to rise.

Second, invisible payments reduce operational costs over time. Fewer cashiers and checkout counters mean lower staffing expenses. Additionally, faster transactions allow more customers to be served during busy hours. This directly impacts revenue in high-traffic locations like airports and stadiums. Stores also save floor space once large checkout counters are removed, allowing more room for products.

Third, this model generates valuable customer data. Every invisible payment creates a digital record of purchase behavior. Consequently, businesses can personalize offers and improve inventory planning. However, this also means data privacy must be handled with great care. Companies that build trust around data security will win customer loyalty faster than competitors who ignore it.

The Competitive Advantage of Early Adoption

Businesses that adopt invisible payments early often stand out from competitors. Customers remember brands that make shopping effortless and quick. This positive experience often leads to repeat visits and referrals. Word of mouth spreads fast when a checkout feels almost magical.

Early adopters also gain valuable operational insights. They learn how customers move through a store or app. Furthermore, this data helps refine layouts, staffing, and product placement. Businesses that wait too long may struggle to catch up once the trend becomes standard practice.

Challenges and Risks of Invisible Payment Systems

Despite the benefits, invisible payments come with real challenges. Security is the biggest concern for most businesses. Storing payment details and biometric data requires strong encryption and compliance. A single data breach can damage a brand’s reputation permanently.

Another challenge involves customer trust. Some shoppers feel uneasy about being tracked by cameras and sensors. Therefore, businesses must be transparent about what data is collected and why. Clear privacy policies and opt-in choices help ease these concerns.

Technical reliability also matters a great deal. If sensors misread a purchase, customers may be charged incorrectly. This can lead to disputes and lost trust. Similarly, businesses need backup systems in case the technology fails. Testing thoroughly before launch reduces these risks significantly. In contrast, rushing implementation often leads to costly mistakes and unhappy customers.

Regulatory and Compliance Considerations

Different regions have different rules about biometric data collection. Businesses must research local regulations before launching invisible payments. Ignoring these rules can lead to fines or legal trouble. Therefore, working with a legal team early saves time and money later.

Payment card industry standards also apply to invisible payment systems. Companies must follow strict guidelines for storing and processing card data. Additionally, regular security audits help catch weaknesses before they become real problems. Staying compliant builds long-term credibility with both customers and regulators.

How to Prepare Your Business for Invisible Payments

Getting ready for invisible payments does not require a complete overhaul. Start by researching which pay without checkout tools fit your industry. Retailers, restaurants, and service businesses each have different needs and options.

Next, evaluate your current payment infrastructure. Check whether your systems can integrate with sensors, apps, or biometric tools. Furthermore, talk to vendors who specialize in invisible payment technology. Many offer scalable solutions for small and medium businesses, not just large retailers. Ask for case studies from businesses similar to yours before signing any contract.

Employee training also plays a key role in this transition. Staff should understand how the new system works and how to help customers. Additionally, create a clear communication plan for customers before launching. Explain the benefits and address privacy questions upfront. Finally, start with a pilot program in one location before expanding company-wide. This approach lets you fix issues early and build confidence in the system.

Measuring Success After Launch

Track key metrics like transaction speed and customer satisfaction scores. Compare these numbers against your old checkout process regularly. This data shows whether invisible payments are truly improving the experience. Also, monitor error rates closely during the first few months.

Customer feedback surveys offer valuable insight beyond raw numbers. Ask shoppers directly how they feel about the new system. Their honest responses often reveal issues that data alone cannot show. Use this feedback to refine your approach before a full rollout across every location.

If your goal is to lead in this space and build real trust with your audience, Build your authority with Digital Payment Guru. Expert guidance can help you stay ahead as invisible payments continue to grow.

How Do Invisible Payments Work in Real Life

Conclusion

Invisible payments are reshaping how people shop, eat, and travel. Pay without checkout offers speed, convenience, and a smoother customer journey. Businesses that adopt this technology early can reduce costs and boost satisfaction. However, success requires careful attention to security, privacy, and reliability. Start small, test often, and communicate clearly with your customers. As more industries embrace invisible payments, staying informed will keep your business competitive. The future of checkout is quiet, fast, and nearly invisible.

Customers today expect convenience at every touchpoint of their journey. Businesses that ignore this shift risk falling behind quickly. On the other hand, those who invest wisely will build lasting loyalty. Take the first step by researching solutions that fit your industry. The sooner you start, the sooner you can offer a truly effortless experience to every shopper who walks through your door.

Frequently Asked Questions

1. What are invisible payments?

Invisible payments let customers pay automatically without a traditional checkout step, often using sensors, apps, or biometric data.

2. Is pay without checkout safe to use?

Yes, when businesses use strong encryption and clear privacy policies. Security remains a top priority for these systems.

3. Which industries use invisible payment technology the most?

Retail stores, ride-sharing apps, and restaurants are leading adopters of pay without checkout experiences today.

4. Do invisible payments require special hardware?

Many systems use sensors, cameras, or mobile apps. Requirements vary depending on the specific technology you choose.

5. How can small businesses start using invisible payments?

Start with a pilot program using an affordable vendor solution. Test performance before rolling it out to all locations.

Also Read:

How Do Smart Businesses Use Voice Payments? Complete Guide

How Do Modern Brands Manage B2B Payments? Ultimate Guide

How Do Smart Businesses Use Voice Payments

How Do Smart Businesses Use Voice Payments? Complete Guide

Voice-Activated Payments: Use Cases and Adoption Challenges

Introduction

Voice-activated payments let people pay using only their voice. No typing, no swiping, and no tapping a screen. This technology is growing fast as smart speakers and voice assistants become common in homes and cars.

Business owners and developers want to know how this trend works in real life. This guide covers the top use cases, the benefits, and the challenges that come with adoption. Let’s explore how voice payments are shaping the future of commerce.

Consumers increasingly expect fast, effortless checkout experiences. Voice technology answers that demand directly. Understanding both the opportunities and the risks helps businesses plan a smarter rollout strategy.

What Are Voice-Activated Payments

Voice-activated payments use speech recognition to complete a transaction. A user simply speaks a command, such as asking a smart speaker to reorder groceries. The system verifies the request and processes the payment.

This technology relies on voice assistants like Alexa, Google Assistant, and Siri. These assistants connect to banking apps or payment platforms in the background. As a result, users complete purchases without touching a device.

Voice payments also use security layers like voice recognition and PIN confirmation. This helps prevent unauthorized transactions. Consequently, the system balances convenience with safety for everyday users.

The technology has grown alongside smart speakers and voice-enabled apps. Millions of households already own a device that supports voice commands. As a result, the audience for voice payments keeps expanding every year.

Businesses find this appealing because it removes friction from checkout. A shorter, simpler payment process often leads to higher completion rates. Similarly, customers enjoy the speed and ease of a hands-free experience.

Developers build these systems using natural language processing and secure payment APIs. The two technologies work together behind the scenes. This combination turns a spoken sentence into a completed, verified transaction.

Tokenization also protects sensitive card details during a voice transaction. Instead of storing raw numbers, the system uses secure tokens. This reduces the impact of any potential data breach significantly.

Multi-factor confirmation is becoming standard practice too. Combining a voice print with a device check adds another safety net. This layered approach reduces fraud without slowing the customer down too much.

Top Use Cases for Voice-Activated Payments

Voice payments show up in many everyday situations. Retail is one of the biggest areas. Shoppers can reorder favorite products just by speaking to a smart speaker at home.

Banking is another strong use case. Customers can check balances or transfer money using voice commands through their bank’s app. This saves time compared to logging in manually.

Food delivery services also use voice payments. Users can order meals hands-free while cooking or driving. Similarly, ride-sharing apps let users book and pay for rides through voice assistants.

In the automotive industry, connected cars allow drivers to pay for fuel or parking without leaving the vehicle. This use case is growing quickly as more cars include built-in voice assistants.

Healthcare providers are testing voice payments as well. Patients can pay medical bills or copays through voice-enabled portals. This makes billing easier for people with limited mobility or busy schedules.

Utility companies increasingly offer voice-based bill pay options too. Customers simply confirm the amount by voice, and the system handles the rest. This reduces late payments and improves customer satisfaction.

Voice Payments in Smart Homes

Smart home devices make voice payments even more useful. Homeowners can pay utility bills or subscribe to services just by speaking. This hands-free approach fits busy daily routines perfectly.

Subscription boxes and grocery refills also work well with this setup. A quick voice command restocks household items without opening an app. This convenience keeps customers coming back for repeat purchases.

Key Adoption Challenges Businesses Face

Despite its promise, voice-activated payment adoption faces real hurdles. Security remains the top concern. Voices can sometimes be mimicked or recorded, which creates fraud risks.

Therefore, companies must use multiple layers of verification. This might include voice biometrics combined with a spoken PIN. However, adding steps can reduce the convenience that makes voice payments attractive in the first place.

Another challenge is accuracy. Background noise or accents can confuse voice recognition systems. This leads to failed transactions and frustrated users. Developers must keep improving speech recognition models to reduce these errors.

Trust is also a barrier. Many people feel uneasy about speaking financial details out loud. Privacy concerns grow when payments happen in shared spaces, like a living room with guests present.

Finally, technical integration is complex. Businesses need to connect voice assistants with existing payment systems securely. This requires strong developer support and ongoing testing to avoid glitches.

Regulatory compliance adds another layer of difficulty. Payment rules differ across regions and industries. Businesses must ensure their voice payment system meets local financial regulations before launching publicly.

User experience design is often overlooked too. A confusing voice flow frustrates customers quickly. Clear prompts and short confirmation steps make the process feel natural instead of clunky.

Language and accessibility gaps also matter. Not every customer speaks the same language or dialect supported by the system. Businesses that ignore this risk excluding large groups of potential users.

How Businesses Can Prepare for Voice Payment Growth

Businesses ready to adopt voice payments should start with a clear strategy. First, identify where voice commands add real value, such as reorders or bill payments. Not every transaction needs a voice option.

Next, invest in strong security protocols. Use voice biometrics along with backup verification methods. This builds customer trust while reducing fraud risk. Meanwhile, always give users an alternative way to pay if voice fails.

Testing matters too. Run pilot programs before a full launch. Gather user feedback and fix issues early. This approach saves money and prevents a poor first impression.

Finally, educate customers about how the system works. Clear instructions reduce confusion and build confidence. As adoption grows, businesses that prepare early will gain a strong competitive advantage.

It also pays to monitor industry trends closely. Payment technology changes fast, and new standards appear often. Staying updated helps businesses avoid falling behind competitors who adapt quickly.

Partnering with experienced payment providers can shorten the learning curve. These partners understand compliance, security, and integration challenges already. This support reduces risk during the early stages of adoption.

Measuring Success After Launch

Once voice payments go live, track key metrics closely. Watch completion rates, failed transactions, and customer feedback scores. These numbers reveal whether the system truly helps customers.

Adjust prompts and verification steps based on real usage data. Small changes often fix common friction points quickly. As a result, the experience keeps improving after the initial launch.

Compare performance against traditional payment methods too. This comparison shows whether voice payments actually save time or reduce errors. Consistent measurement keeps the strategy honest and effective.

Share results with your team regularly. Transparency around wins and setbacks builds momentum for future improvements. Over time, this data-driven approach turns a pilot project into a trusted, long-term system.

How Do Smart Businesses Use Voice Payments

Conclusion

Voice-activated payments offer real convenience for both businesses and customers. Use cases span retail, banking, food delivery, and connected cars. However, adoption challenges like security, accuracy, and trust still need attention.

Companies that address these challenges thoughtfully will lead this growing market. Voice commerce is not just a trend. It is becoming part of daily life for many consumers.

Businesses that invest early in secure, well-tested voice payment systems will build stronger customer loyalty. Patience and careful testing today lead to smoother, more trusted experiences tomorrow.

Looking ahead, expect voice recognition accuracy to keep improving. As it does, more industries will explore fresh use cases beyond the ones covered in this guide.

Ready to lead in this space with confidence? Build your authority with Digital Payment Guru and stay ahead of the voice payment revolution.

Frequently Asked Questions

1. What are voice-activated payments?

Voice-activated payments let users complete transactions by speaking to a device, such as a smart speaker or voice assistant, instead of typing or tapping.

2. Are voice-activated payments secure?

They can be secure when combined with voice biometrics and extra verification steps like a spoken PIN. Businesses should always add layered security.

3. Which industries use voice payments the most?

Retail, banking, food delivery, and the automotive industry use voice payments heavily. Smart home services also rely on this technology often.

4. Why do some businesses hesitate to adopt voice payments?

Businesses worry about fraud risks, accuracy issues, and customer trust. These challenges require careful planning and strong security measures.

5. How can a business start using voice payments? Start with a small pilot program, add strong security, and gather customer feedback. This helps identify problems before a full rollout. A trusted payment partner can also speed up the process.

Also Read:

How Do Modern Brands Manage B2B Payments? Ultimate Guide

How Do Split Payments Boost Seller Retention? Ultimate Guide

How Do Modern Brands Manage B2B Payments

How Do Modern Brands Manage B2B Payments? Ultimate Guide

Payments in B2B Commerce: Why It’s Still Broken

Getting paid should be simple. Yet in B2B commerce payments, delays, errors, and confusion remain the norm. Many business owners accept this as just how things work.

Yet frustration keeps growing as businesses scale. What felt manageable at a small size becomes unsustainable once transaction volume increases. Recognizing this shift early helps leaders act before problems compound further.

That assumption is costly. Late payments hurt cash flow, strain supplier relationships, and slow down growth. Understanding the root causes is the first step toward fixing them.

This article breaks down why B2B commerce payments still struggle today. It also shows practical ways businesses can close these gaps and get paid faster.

Every industry feels this pain differently. Manufacturing companies wait on large purchase orders, while service providers chase recurring invoices. Regardless of industry, the underlying frustration remains remarkably similar.

Solving this problem requires more than a single tool. It takes a shift in mindset, alongside better systems and clearer expectations between buyers and sellers.

The Core Problems With B2B Commerce Payments

Manual processes remain shockingly common. Many companies still send invoices by email and track payments in spreadsheets. This approach invites errors and missed deadlines.

These outdated habits persist even inside otherwise modern companies. Teams often adopt new software for other functions while leaving payments untouched. This inconsistency creates an obvious weak link in the overall process.

Approval chains add another layer of friction. A single invoice might need sign-off from three or four people. Meanwhile, the vendor waits, wondering when payment will arrive.

Payment terms also create confusion. Net-30, net-60, and net-90 arrangements vary by client. As a result, finance teams juggle dozens of different timelines at once.

Currency and banking differences complicate cross-border deals further. A payment sent from one country can take days to clear in another. Consequently, international suppliers often face the longest waits.

Fraud risk adds extra caution to every transaction. Businesses verify details repeatedly before releasing funds. While necessary, this step slows things down even more.

Legacy banking infrastructure adds friction on top of everything else. Wire transfers can take several business days to clear. Meanwhile, weekend and holiday schedules extend these timelines even further.

Together, these issues create a system built on patience rather than efficiency. Buyers and sellers both lose time they cannot get back.

Disputes over invoice details add further delay. A missing purchase order number or a mismatched amount can freeze payment entirely. Meanwhile, resolving these small errors often takes several rounds of email.

Multiple payment methods complicate things too. Checks, wire transfers, and digital platforms all move at different speeds. As a result, finance teams juggle several systems just to track one transaction.

Why These Problems Persist

Legacy systems are hard to replace. Many businesses built their finance operations years ago. Switching to new software feels risky, even when the old system clearly struggles.

Trust also plays a role. Buyers often delay payment simply because they can. Without strong contracts or automated reminders, there is little pressure to pay on time.

Additionally, many teams lack visibility into payment status. Finance staff cannot always see where an invoice sits in the approval chain. Therefore, delays go unnoticed until a supplier complains.

Smaller businesses face a unique challenge here. They often lack the negotiating power to demand faster terms. Larger buyers set the rules, and smaller vendors simply comply.

Regulatory differences across regions add more complexity. Tax rules, reporting requirements, and banking laws vary widely. This forces businesses to manage multiple compliance checklists at once.

All these factors combine into a slow-moving system. No single fix solves everything, but understanding each piece helps businesses target the right solutions.

Internal politics can slow things down as well. Departments sometimes disagree on who owns the payment process. Therefore, invoices bounce between teams before anyone takes real responsibility.

Fear of change also keeps outdated habits alive. Finance leaders often worry that new systems will disrupt existing relationships. This caution, while understandable, keeps many businesses stuck with slow processes longer than necessary.

The Real Cost of Broken B2B Payments

Cash flow suffers first. When payments arrive late, businesses struggle to cover their own expenses. This can create a ripple effect across an entire supply chain.

Supplier relationships also take a hit. Vendors who face repeated delays may raise prices or reduce service quality. In contrast, reliable payers often receive better terms and priority service.

Staff time is another hidden cost. Finance teams spend hours chasing overdue invoices instead of focusing on growth tasks. This drains productivity across the whole department.

Growth opportunities can disappear too. Businesses with weak cash flow struggle to invest in new equipment or hires. Thus, payment delays quietly limit long-term potential.

Reputation matters as well. Word travels fast among suppliers and partners. A business known for slow payments may struggle to secure favorable deals in the future.

These costs add up quickly. What looks like a minor administrative issue often becomes a serious barrier to business success.

Stress on internal teams should not be ignored either. Constantly chasing payments creates tension and burnout among finance staff. Over time, this can even affect employee retention within the department.

Smaller vendors often feel this pain the most. A single late payment can strain their entire operating budget. In contrast, larger enterprises usually have more cushion to absorb these delays.

How Businesses Can Fix B2B Commerce Payments

Automation offers the fastest path forward. Digital invoicing tools reduce manual errors and speed up approvals significantly. Many platforms also send automatic reminders to reduce late payments.

Cloud-based platforms make this transition easier than before. Teams can access invoices and payment status from anywhere. This flexibility supports remote and hybrid work environments common today.

Clear payment terms help too. Setting consistent timelines across all clients removes confusion. Similarly, offering small discounts for early payment can encourage faster action.

Real-time tracking improves visibility for everyone involved. Both buyers and sellers can see exactly where a payment stands. This transparency builds trust and reduces unnecessary follow-up calls.

Choosing the right payment partner also matters. Look for providers who support multiple currencies and fast settlement times. This is especially important for businesses working across borders.

Security features deserve close attention during vendor selection. Strong encryption and fraud detection protect both parties. As a result, businesses can move faster without taking on unnecessary risk.

Regular audits help catch problems early. Reviewing payment cycles every quarter reveals patterns worth addressing. As a result, businesses can fix small issues before they grow larger.

Negotiating better terms upfront also helps both sides. Clear agreements about deadlines and penalties reduce ambiguity later. Consequently, disputes become far less frequent once expectations are documented clearly.

Finally, strong communication between finance teams and suppliers builds better habits. Open conversations about expectations often prevent disputes before they start.

Standardizing invoice formats also reduces friction significantly. When every invoice follows the same structure, approvals move faster. This small change often prevents many common disputes.

Training staff on new systems matters just as much as choosing the right tool. A platform only helps when people actually use it correctly and consistently across every transaction.

Conclusion

B2B commerce payments do not have to stay broken. With better tools, clear terms, and stronger visibility, businesses can finally close these long-standing gaps.

The companies that fix this now will move faster than competitors still stuck in old habits. Speed and reliability become a real competitive advantage.

Suppliers notice which partners pay on time. Over the long run, reliable payers often receive better pricing and priority treatment. This reputation becomes a genuine business asset.

Change takes effort, but the payoff is worth it. Stronger cash flow, better relationships, and less administrative stress all follow once the system finally works properly.

Ready to modernize how your business handles payments? Build your authority with Digital Payment Guru and turn payment friction into a growth opportunity.

How Do Modern Brands Manage B2B Payments

Frequently Asked Questions

  1. Why are B2B commerce payments often delayed? Delays usually come from manual processes, long approval chains, and unclear payment terms. These factors slow down even simple transactions.
  2. How can businesses reduce late payments from clients? Setting clear terms, sending automatic reminders, and offering early payment discounts all help. Consistent communication also reduces confusion around deadlines.
  3. What role does automation play in B2B payments? Automation reduces manual errors and speeds up approvals. It also gives both buyers and sellers real-time visibility into payment status.
  4. Why is cross-border B2B payment more difficult? Different currencies, banking systems, and regulations add complexity. These differences often extend settlement times for international transactions.
  5. What is the biggest hidden cost of broken payment systems? Lost staff time and weakened supplier relationships are often overlooked. Both quietly limit a business’s ability to grow efficiently.

Also Read:

How Do You Choose Subscription Payment Systems? Ultimate Guide

How Do Split Payments Boost Seller Retention? Ultimate Guide

How Does Reliable Payment Tech Drive Gamer Trust

How Does Reliable Payments Tech Drive Gamer Trust? Ultimate Guide

Payments for Gaming Platforms: Handling Microtransactions at Scale

Introduction

Gaming platforms live and die by their payment systems. A single failed transaction can push a player away for good. As games grow, so does the volume of microtransactions. Players buy skins, coins, boosts, and battle passes, often within seconds of deciding to spend. This creates unique pressure on payment infrastructure. Speed, reliability, and security all matter at once. In this guide, we explore how payments for gaming platforms work when microtransactions happen at scale. You will learn what makes gaming payments different, the biggest challenges operators face, and practical steps to build a system that can handle millions of small transactions without breaking down. By the end, you will have a clear framework for evaluating your own payment stack against the demands of modern, high-volume gaming.

What Makes Gaming Microtransactions Different with Payments

Microtransactions are small in value but massive in volume. A single popular game can process millions of purchases each day. Each purchase might be worth only a dollar or two. However, the total transaction count creates real strain on payment systems. Traditional payment setups, built for larger and less frequent purchases, often struggle here.

Speed is another defining factor. Players expect instant delivery after payment. A delay of even a few seconds can feel broken, especially during active gameplay. As a result, payment systems for games must process approvals almost instantly. This is different from e-commerce, where a short delay before shipping confirmation is normal and expected.

Fraud risk also looks different in gaming. Stolen cards are often tested through small in-game purchases before being used for larger crimes elsewhere. Consequently, gaming platforms become an early target for fraud testing. This means fraud detection must work in real time, without slowing down legitimate players.

Finally, global reach adds complexity. Gaming audiences span nearly every country. Each region has different preferred payment methods, currencies, and regulations. A platform built only for credit cards will lose players in markets where mobile wallets or prepaid vouchers dominate.

Player behavior also differs from typical online shopping. Purchases often happen impulsively, driven by in-game moments such as reaching a difficult level or unlocking a limited-time offer. This means checkout friction has an outsized effect on revenue. Every extra step in the payment flow risks losing a sale that would have closed instantly with a smoother process. As a result, gaming platforms tend to invest heavily in one-click or saved-payment experiences that other industries adopt more slowly.

Core Challenges in Scaling Gaming Payments

The first major challenge is transaction cost. Processing fees that seem small on a single purchase add up quickly across millions of microtransactions. Platforms need pricing models that remain profitable even on very small purchase amounts. Otherwise, popular low-cost items can quietly erode margins.

The second challenge is infrastructure load. Payment systems must handle sudden spikes, such as when a new game update launches. Traffic can jump within minutes, and any slowdown directly costs revenue. Therefore, scalable, cloud-based payment infrastructure is essential rather than optional.

Chargebacks present a third challenge. Because microtransactions are low value, some players dispute charges casually, assuming the amount is too small to matter. However, chargeback fees are often flat, regardless of the purchase size. A high volume of small disputes can quickly damage profitability and merchant standing with payment processors.

Regulatory compliance adds a fourth layer of difficulty. Rules around in-game purchases, loot boxes, and payments involving minors vary by country. Some regions require clear spending limits or parental controls. Platforms operating globally must track and apply these rules correctly, or risk fines and platform bans.

Currency handling introduces a fifth challenge that is easy to overlook. Displaying prices in a player’s local currency improves trust and conversion. However, currency conversion also introduces rounding issues and exchange rate risk. Platforms must decide whether to absorb small fluctuations or pass them along, and that decision affects both margins and player perception of fairness.

How to Build a Payments System That Scales

Start with a payment provider built for high transaction volume. Look for partners with proven experience in gaming, not just general e-commerce. These providers understand microtransaction pricing and can offer better rates at scale.

Next, prioritize multiple payment methods from day one. Credit cards remain important, but mobile wallets, carrier billing, and prepaid options often drive higher conversion in specific regions. Offering local payment methods can increase completed purchases significantly, especially in markets where card ownership is low.

Implement real-time fraud detection that uses behavioral signals, not just static rules. For example, a system might flag rapid, repeated small purchases from a new account as suspicious. Modern fraud tools use machine learning to catch these patterns without blocking genuine players. Balance is key here. Overly strict fraud rules frustrate real customers, while weak rules invite abuse.

Additionally, build a smart retry system for failed payments. Many failures happen due to temporary issues, such as a bank’s fraud check or a network hiccup. Automatically retrying a failed charge, with proper safeguards, can recover a meaningful share of lost revenue without extra effort from the player.

Finally, invest in clear reporting and reconciliation tools. At scale, manual tracking of transactions becomes impossible. Automated dashboards that show revenue, chargeback rates, and regional performance help teams spot problems early and react quickly.

It also helps to separate your payment logic from your core game code. Keeping these systems modular means you can update payment providers, add new methods, or adjust pricing without touching gameplay systems. This separation reduces risk and speeds up future changes, since payment teams can iterate independently from game development teams.

Best Practices for Reliability and Trust on Payments

Reliability builds player trust, and trust drives spending. Aim for near-perfect uptime on your payment system, since even brief outages during peak hours can cause significant revenue loss and player frustration.

Transparency also matters greatly. Clearly show players what they are buying and the exact price before confirming. Hidden fees or confusing currency conversions create frustration and increase support tickets. Similarly, send instant purchase confirmations so players know their transaction succeeded.

Security should never be an afterthought. Use tokenization to avoid storing raw card data directly. This reduces your compliance burden and protects players if a breach ever occurs elsewhere in your systems. Regular security audits are equally important, especially as your platform integrates new payment partners over time.

Consider offering spending controls, particularly for platforms with younger audiences. Features like daily spending caps or parental approval steps build long-term trust with both players and regulators. This proactive approach can also reduce chargeback disputes tied to unauthorized purchases by minors.

Lastly, monitor performance across regions separately. A payment method that works well in one country may perform poorly elsewhere. Regular regional reviews help you adjust your payment mix and maintain strong conversion rates everywhere you operate.

It is also wise to run periodic load tests that simulate peak traffic before major releases. Simulated stress testing reveals weak points in your payment stack while the stakes are still low. Fixing a bottleneck during a test costs far less, in both money and reputation, than discovering it during a live launch with thousands of players trying to spend at once.

How Does Reliable Payment Tech Drive Gamer Trust

Conclusion

Handling microtransactions at scale requires more than a standard payment setup. Gaming platforms need speed, global payment options, strong fraud protection, and reliable infrastructure working together. By choosing the right partners and building smart, automated systems, you can support massive transaction volumes without sacrificing player trust. As your platform grows, these foundations will keep payments smooth, secure, and profitable. Build your authority with Digital Payment Guru and turn your payment infrastructure into a genuine competitive advantage.

Frequently Asked Questions

1. What is a microtransaction in gaming?

A microtransaction is a small in-game purchase, such as buying virtual currency, cosmetic items, or extra content, usually for a low price.

2. Why do gaming platforms face more fraud attempts than other industries?

Stolen payment cards are often tested through small gaming purchases before being used elsewhere, making games an early fraud target.

3. How can gaming platforms reduce chargeback rates?

Clear pricing, instant confirmations, and spending controls all help reduce disputes caused by confusion or unauthorized purchases.

4. Do gaming platforms need to support multiple payment methods?

Yes. Supporting local wallets, carrier billing, and prepaid options improves conversion rates in regions with low card ownership.

5. What role does infrastructure play in payment scalability?

Cloud-based, scalable infrastructure ensures payment systems handle sudden traffic spikes, such as new game launches, without downtime.

Also Read:

How Do SaaS Leaders Plan Payment Strategies? Ultimate Guide

How Do EdTech Start-ups Simplify Payments? Ultimate Guide