How Does a Virtual CTO Compare to Full-Time CTOs

How Does a Virtual CTO Compare to Full-Time CTOs? Ultimate Guide

Virtual CTO for FinTech Startups: Architecting Banking API Integrations With Zero Downtime

Fintech founders face a tough puzzle. You must launch fast, stay secure, and never let payments fail. Yet many startups cannot afford a full-time chief technology officer. Therefore, a virtual CTO for fintech startups can be a smart answer. This expert guides your technology plan on a flexible basis. One of the hardest tasks is connecting to banks through APIs without any downtime. This guide explains how a virtual CTO approaches that job. You will also learn the design habits that keep money moving.

What Is a Virtual CTO for FinTech Startups?

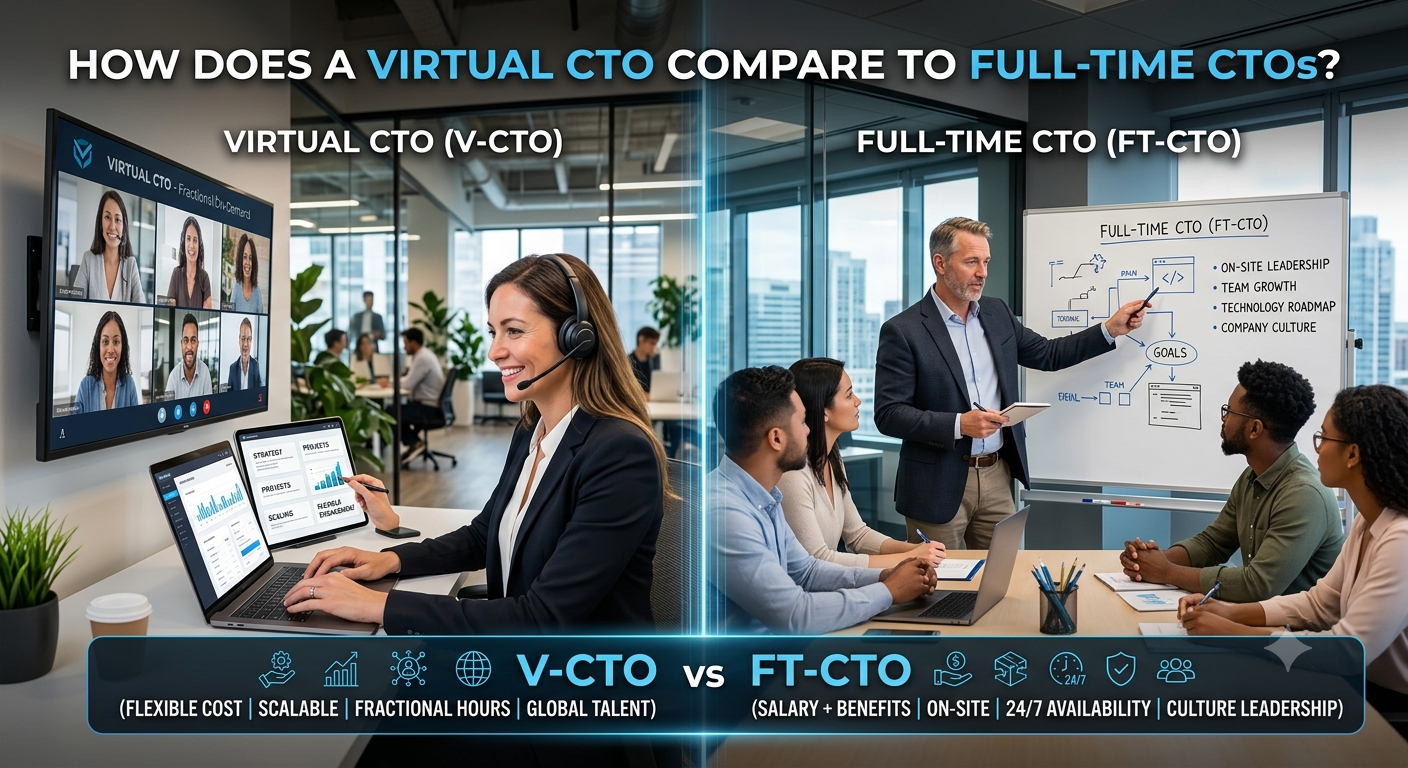
A virtual CTO is a senior technology leader who works with you part time or on contract. Some people call this role a fractional CTO. The person sets your tech strategy, guides your engineers, and reviews key choices. You pay only for the time you need. That makes the model a smart fit for early-stage teams.

Fintech adds special pressure to this role. Your product handles real money and sensitive data. Regulators watch closely, and customers lose trust fast after an outage. A virtual CTO who knows fintech understands these risks. They bring experience from many projects, so you avoid common traps.

Typical duties are broad. They pick the tech stack and design the system architecture. They set security standards and plan for compliance rules such as PCI DSS. Hiring and coaching developers is part of the job too. Most of all, they connect tech choices to business goals.

Compare this with a full-time CTO. A full-time hire costs more and may take months to find. A virtual CTO can start within weeks. As your company grows, you can move to a full-time leader with a clean plan already in place.

Consider a small payments startup with five engineers. The team knows how to build features but lacks bank experience. A virtual CTO reviews the plan, spots weak points, and sets clear standards. Developers gain confidence, and the founder gains a trusted adviser. Moreover, investors like to see this level of technical care.

Why Banking API Integrations Are Hard

Banking APIs let your app talk to banks and payment networks. They power account checks, payments, and balance data. Open banking rules in many regions make these APIs more common. However, each bank works differently. Formats, limits, and rules vary widely.

Banks also change systems without much warning. An API may slow down, return odd errors, or go offline for maintenance. Your product must handle all of this smoothly. A single weak link can freeze payments for thousands of users.

Security adds more weight. You must protect tokens, keys, and customer data at every step. Rules require strong authentication and careful logging. Mistakes can lead to fines and lost trust.

For these reasons, integration cannot be an afterthought. It needs a clear architecture from day one. That is exactly where a virtual CTO adds value.

Cost is another factor. Every hour of downtime can mean failed payments and angry customers. Support tickets rise, and partners start to worry. Additionally, repeated outages may put your bank relationship at risk. Prevention is always cheaper than recovery, and it keeps your team calm.

How a Virtual CTO Designs for Zero Downtime

Zero downtime means your service stays available even when parts fail or change. No system is perfect, but good design gets very close. Here are the core ideas a virtual CTO uses.

Build a Clean API Gateway Layer

A gateway sits between your app and every bank API. Your core product talks only to the gateway. The gateway handles each bank’s format, rules, and quirks. If a bank changes something, you fix one place instead of many. This also makes adding new banks much faster.

Use Retries, Timeouts, and Circuit Breakers

Networks fail often, so plan for that. Smart retries try again after a short pause. Timeouts stop your system from waiting forever. A circuit breaker cuts off a failing service for a moment so it cannot drag everything down. Together, these tools keep small problems small.

Make Payments Safe to Repeat

However, retries can cause double payments if you are careless. The fix is called idempotency. Each payment request carries a unique key. If the same request arrives twice, the system processes it only once. This protects customers and your reputation.

Add Backup Routes and Queues

Never depend on one bank connection for critical flows. A backup provider can take over when the main one fails. Message queues store requests safely during a slowdown. As a result, work continues once the service recovers. Customers see a short delay instead of an error.

Data consistency deserves attention too. When a payment moves between systems, every record must match. Reconciliation jobs compare your ledger with bank statements each day. Any gap triggers an alert. This habit catches quiet errors before customers notice them.

Release Without Stopping the Service

Deployments often cause outages. Blue-green deployment avoids this. You run the new version next to the old one and switch traffic only after tests pass. If something breaks, you switch back in seconds. Feature flags let you turn new code on for a few users first.

Testing, Monitoring, and Compliance

However, design alone is not enough. Teams must test and watch the system all the time. A virtual CTO builds these habits into your culture.

Start with sandbox testing. For example, most banks offer test environments. Run real scenarios there, including failures and slow responses. Load tests show how your system behaves at peak traffic. Chaos tests, which break parts on purpose, reveal hidden weak spots.

Monitoring comes next. Track response times, error rates, and payment success rates. Set alerts that reach the right person quickly, day or night. Dashboards should show the health of every bank connection at a glance. Clear logs help your team find causes in minutes, not hours.

Meanwhile, compliance needs equal care. Encrypt data in transit and at rest. Limit access with roles and strong authentication. Keep audit trails for every payment action. Plan regular security reviews and penetration tests. These steps satisfy regulators and calm nervous partners.

Finally, prepare for incidents. Write a simple runbook that explains who does what during an outage. Practice it with your team. After each incident, hold a blameless review and fix the root cause. Over time, your platform becomes tougher and easier to trust.

How to Work With a Virtual CTO for FinTech Startups

Set clear goals before you start. Do you need an architecture plan, a team review, or a compliance roadmap? Agree on deliverables and a schedule. Decide how you will measure success after three months. Ask for regular reports in plain language.

Look for real fintech experience. Ask about past banking API projects and how they handled outages. Check references and past results. Ask to see sample architecture notes or reports. A good virtual CTO explains complex ideas simply and listens to your business needs.

Treat the relationship as a partnership. Give access to your team, your data, and your roadmap. Involve your developers in decisions so knowledge stays in-house. Review progress each month. The best outcome is a stronger internal team that can run without constant outside help.

Conclusion: Keep Payments Running With the Right Tech Leadership

A virtual CTO for fintech startups gives you expert leadership without the cost of a full-time hire. Clean gateways, safe retries, backup routes, and careful releases help banking API integrations run with zero downtime. Strong testing, monitoring, and compliance make the system even more reliable. If your startup is growing fast, now is a great time to get expert guidance. Solid technology today protects your customers and your future. Take the first step by reviewing where your current integrations might fail.
How Does a Virtual CTO Compare to Full-Time CTOs

Frequently Asked Questions

What does a virtual CTO for fintech startups do?

A virtual CTO sets technology strategy, designs architecture, and guides engineers on a part-time basis. In fintech, they also focus on security, compliance, and banking API integration.

How is a virtual CTO different from a full-time CTO?

A virtual CTO works flexibly and costs less. A full-time CTO is embedded daily in your company. Many startups begin with virtual leadership and hire full-time later.

How can banking API integrations have zero downtime?

Use a gateway layer, retries, circuit breakers, backup providers, and blue-green releases. Add strong monitoring so problems are caught early.

When should a fintech startup hire a virtual CTO?

Hire one when you plan your first product build, prepare for a bank partnership, or face scaling problems. Early guidance prevents costly rework.

What is idempotency in payment APIs?

Idempotency means the same request gives the same result, even if sent twice. It stops duplicate charges when a retry happens.

Also Read:

How Do You Implement AI Dynamic Pricing Today? Ultimate Guide
How Do Modern Brands Manage B2B Payments? Ultimate Guide

How Do You Implement AI Dynamic Pricing Today

How Do You Implement AI Dynamic Pricing Today? Ultimate Guide
Why AI-Driven Dynamic Pricing Needs Payments

Prices no longer stay fixed for long. Demand shifts by the hour, and rivals change their offers all day. Static price lists cannot keep up with this pace. AI-driven dynamic pricing solves the problem by adjusting prices in real time.

However, a smart price means little if checkout fails to honor it. That is why payment integration matters so much. This article shows how to link pricing AI with your payment systems. It helps e-commerce brands, fintech teams, and SaaS founders. You will learn the setup, the risks, and the steps to start.

What Is AI-Driven Dynamic Pricing?

Dynamic pricing means changing prices based on market signals. Airlines and ride apps have used it for years. AI now brings the same power to any online business. The models learn from your data and improve over time.

Signals That Feed Pricing Algorithms

A good model studies many inputs at once. These include demand, stock levels, competitor prices, and seasonality. Customer behavior, such as browsing and cart activity, is reviewed as well. Some models track price elasticity, which shows how sales change when the price moves.

Payment data adds a strong extra layer of insight. It shows what customers actually pay, not just what they view. Consequently, the model learns real willingness to pay.

Dynamic Pricing vs. Rule-Based Pricing

Rule-based tools follow fixed if-then logic. A typical rule says to cut the price ten percent when stock is high. Such rules are simple but rigid. AI models test many factors together and find patterns that humans miss.

They also react faster. A rule may update once a day, while an AI model can update within minutes. That speed protects your margins and wins more sales.

Why Businesses Adopt AI-Driven Dynamic Pricing

Margins are thin in most online markets. A one percent gain in price can lift profit far more than a one percent gain in volume. Smart pricing helps you find that gain without guessing.

It also saves time. Manual price checks across thousands of products are slow and error-prone. Automated engines handle the work around the clock. Your team can then focus on strategy, not spreadsheets.

Why Payment Systems Are the Missing Link

Many pricing tools stop at the product page. The price changes, but the payment layer knows nothing about it. This gap causes real problems. Customers see one price and get charged another. Trust falls fast when that happens.

Integration closes the loop. The pricing engine sends the final price to the payment gateway. The gateway confirms the charge in real time. Then the result flows back to the model as fresh data.

Benefits of Payment Data in Pricing Models

Payment data reveals useful truths. It shows which payment methods convert best and where customers abandon checkout. Refund and chargeback patterns become visible by price band.

With these insights, you can tune prices by segment. You can offer smart rewards for cheaper payment methods. For instance, a small discount for bank transfers can cut card fees.

Fraud and Risk Signals

Payment systems already score fraud risk on every order. Sharing these scores with the pricing engine is valuable. A high-risk order may need a different checkout flow. Trusted repeat buyers, meanwhile, may deserve loyalty prices.

Keep the two goals separate, though. Pricing should never punish people unfairly. Risk data should protect revenue, not overcharge customers.

How to Integrate Dynamic Pricing With Payment Gateways

The setup needs care. Here is a simple path that many teams follow.

Step 1: Map Your Data Sources

Every system that touches price should be listed. Include your catalog, inventory, CRM, analytics, and payment gateway. Note where each one holds data and how often it updates. Clean and connected data is the base of good pricing.

Step 2: Use APIs and Webhooks

An API is a doorway between two software tools. A webhook is an alert that one system sends to another. Use both. The pricing engine calls the API to set the price. The gateway then sends webhooks when payments succeed or fail.

Most modern gateways support this pattern. Check for real-time endpoints and clear rate limits. Test how the system behaves during traffic spikes.

Step 3: Lock the Price at Checkout

Never let prices change in the middle of a payment. Create a price quote with a short expiry, such as ten minutes. The quote should be stored against the cart. The gateway must then charge exactly that amount. As a result, customers see no surprises.

Step 4: Handle Currency, Tax, and Fees

Global stores face extra layers. Prices may vary by currency and tax rule. Payment fees also differ by method. These costs should be built into the price logic from day one. Otherwise, margins can shrink without warning.

Step 5: Set Price Floors and Ceilings

Give the AI firm limits. A floor keeps you above cost. A ceiling protects your brand from extreme jumps. Add change limits per hour to stop wild swings. Guardrails keep smart tools safe.

Real-World Use Cases for Payment-Linked Pricing

Online stores use the model to adjust prices during sales and stock shortages. A fashion brand can trim prices on slow items while holding firm on best sellers. Payment data shows which discounts truly convert into paid orders.

SaaS companies apply the same idea to subscription plans and usage fees. Fintech firms use it to set fees based on transaction size and risk. Travel and event sellers raise or lower prices as seats fill. In each case, the checkout must confirm the exact price the customer saw.

Marketplaces gain too. Sellers get pricing suggestions that match demand, and the payment layer settles funds correctly. This builds trust on both sides of the platform.

Best Practices, Risks, and Compliance

Dynamic pricing can backfire without care. Customers dislike feeling tricked. Unfair practices are watched closely by regulators.

Keep Pricing Fair and Transparent

Avoid pricing based on personal traits. Sensitive data such as health or ethnicity should never be used. Explain price changes in simple terms when asked. Offer loyalty and volume rewards that customers can see. Fairness builds long-term trust.

Protect Payment Data

PCI DSS, the global card security standard, must be followed. Raw card numbers should never be stored in the pricing engine. Tokens are used instead. Encrypt data in transit and at rest. Vendor security should be reviewed often.

Test Before You Scale

Start with A/B tests on a small product group. Compare revenue, conversion, and refund rates. Each test should run for at least two full weeks. Then expand to more products. A human reviewer should stay in the loop for major changes.

Common Mistakes to Avoid

Many teams launch too fast. Some skip price limits and watch margins collapse. Others ignore taxes and fees inside the model. A few forget mobile checkout, where prices often lag. These gaps should be fixed before you scale.

Choose the Right Tools

Look for a pricing engine with open APIs and strong analytics. Confirm that it works with your payment gateway and orchestration layer. Ask how quickly it can push a new price to checkout. Request a sandbox so your team can test safely.

Measure What Matters

Track revenue per visitor, conversion rate, margin, and checkout success rate. Watch customer complaints closely. If trust metrics fall, slow down. Smart pricing should raise profit without hurting loyalty.

Conclusion: Make Pricing and Payments Work as One

AI-driven dynamic pricing helps you respond to the market in real time. Payment integration makes those prices reliable at checkout. Together, they raise revenue, cut friction, and improve decisions. However, success needs clean data, firm guardrails, and fair rules.

Start small with one product line. Pilot results should be shared with finance, product, and support teams. Connect your gateway, lock prices at checkout, and test carefully. Then scale what works. Ready to lead in payments and pricing innovation?

How Do You Implement AI Dynamic Pricing Today

Frequently Asked Questions

1. What is AI-driven dynamic pricing?

It is a method where AI changes prices automatically using live data. Live inputs include demand, stock, competitor prices, and customer behavior. Better revenue and margins are the goal.

2. How does dynamic pricing connect to a payment gateway?

The pricing engine sends the approved price through an API. The gateway charges that exact amount and returns the result. Webhooks then feed payment outcomes back to the model.

3. Is dynamic pricing legal?

It is legal in most regions when it is fair and transparent. Rules against discrimination and deceptive pricing still apply. Check local laws and get legal advice before launch.

4. Which businesses benefit most from real-time pricing?

E-commerce stores, travel firms, SaaS companies, and marketplaces gain the most. Any business with changing demand or limited stock can benefit.

5. How can I avoid upsetting customers?

Set price limits, avoid sudden large jumps, and explain your pricing logic. Reward loyal buyers. Monitor complaints and adjust quickly.

Also Read:

How Do Invisible Payments Boost Customer Joy? Ultimate Guide

How Do Modern Brands Manage B2B Payments? Ultimate Guide

How Do Invisible Payments Boost Customer Joy

How Do Invisible Payments Boost Customer Joy? Ultimate Guide

Invisible Payments: The Rise of Pay Without Checkout Experiences

Introduction

Imagine leaving a store without scanning a single item. No line, no card swipe, no waiting. This is the idea behind invisible payments. These systems let customers pay without checkout, using sensors, apps, or stored payment details. Furthermore, this trend is growing fast across retail, transportation, and food service. Businesses are adopting invisible payments to reduce friction and boost customer satisfaction. In this article, we explore how invisible payments work. We will also look at their benefits, challenges, and future potential. Whether you run a store or simply enjoy smoother shopping, this guide has useful insights for you.

Main Section 1: What Are Invisible Payments?

Invisible payments remove the traditional checkout step entirely. Customers link their payment method to an app or account beforehand. Then, sensors or scanners detect what they take or use. Payment happens automatically in the background. As a result, there is no register, no line, and no manual transaction.

This concept already exists in several familiar forms. Ride-sharing apps charge riders automatically after each trip. Similarly, some grocery stores use camera systems to track purchases. Toll roads have used similar technology for years through automatic vehicle scanning. Each example shares one goal: removing friction from the payment moment.

Invisible payments rely on a mix of technologies. These include mobile apps, RFID tags, computer vision, and secure cloud accounts. Consequently, the customer experience feels almost magical. However, strong technology and data security work behind the scenes to make it possible.

Main Section 2: Why Invisible Payments Are Growing So Quickly

Consumer expectations have shifted dramatically in recent years. People want speed and simplicity in every transaction. Long checkout lines feel outdated compared to instant digital experiences. Therefore, businesses are racing to remove this pain point.

Mobile technology has also matured significantly. Most customers now carry smartphones with secure payment apps installed. This makes background payments easier to implement safely. Meanwhile, advances in computer vision and sensor technology have dropped in cost. This allows more businesses to afford invisible payment systems.

Additionally, the pandemic accelerated contactless payment adoption worldwide. Many customers now prefer minimal physical interaction during purchases. Invisible payments take this preference one step further. There is no card tap and no manual entry required at all.

Retailers also benefit financially from faster transactions. Shorter wait times often lead to higher customer satisfaction scores. In turn, satisfied customers tend to spend more and return more often. This creates a strong business case for adopting invisible payment technology.

Main Section 3: Real-World Examples of Pay Without Checkout

Several industries already use invisible payment models successfully. Cashierless convenience stores let shoppers grab items and simply walk out. Cameras and weight sensors track every item automatically. Payment then processes through the customer’s linked account.

Ride-hailing and food delivery apps offer another clear example. Users never exchange cash or cards during their trip or order. Instead, payment happens instantly once the service is complete. This model has become the standard across most delivery platforms today.

Public transportation systems have also embraced invisible payments. Contactless transit cards and tap-to-ride systems reduce boarding delays. Some cities are even testing facial recognition for fare collection. Similarly, smart parking systems now charge drivers automatically upon exit.

Hotels and gyms are exploring similar technology too. Guests can access rooms and pay for extra services without visiting a front desk. As these examples show, invisible payments extend far beyond retail stores.

Main Section 4: Challenges and Considerations for Businesses

Despite clear benefits, invisible payments come with real challenges. Security remains the top concern for most businesses and customers. Storing payment details requires strong encryption and fraud protection systems. Without proper safeguards, businesses risk data breaches and customer trust loss.

Privacy is another important consideration. Camera-based tracking systems collect detailed shopper behavior data. Consequently, businesses must clearly explain how this data gets used. Transparent privacy policies help build customer confidence in these systems.

Implementation costs can also be significant. Sensors, cameras, and software integration require upfront investment. Smaller businesses may need to start with simpler versions of this technology. For example, app-based payment systems cost less than full computer vision setups.

Employee training matters as well. Staff need to understand new systems and assist customers during the transition period. Meanwhile, businesses should plan for occasional technical issues. Backup payment options should always remain available for reliability.

Finally, customer education plays a key role in adoption. Some shoppers may feel hesitant about automatic payments at first. Clear signage and simple onboarding can ease this concern effectively.

Conclusion

Invisible payments are reshaping how customers experience transactions everywhere. From cashierless stores to automatic ride payments, checkout-free experiences are becoming common. Businesses that adopt this technology thoughtfully can boost speed and satisfaction. However, success requires strong security, clear privacy practices, and proper customer education. As technology continues advancing, invisible payments will likely become the new standard. Companies that prepare today will lead this shift tomorrow.

How Do Invisible Payments Boost Customer Joy

Frequently Asked Questions

1. What are invisible payments?

Invisible payments let customers complete purchases without a traditional checkout. Sensors or apps handle the transaction automatically in the background.

2. Are invisible payments safe to use?

Yes, when businesses use strong encryption and fraud protection. Security measures protect customer data throughout every transaction.

3. Which industries use invisible payments today?

Retail, transportation, food delivery, and hospitality industries already use invisible payment systems successfully.

4. Do invisible payments require a smartphone?

Most invisible payment systems use a smartphone app or linked account. However, some use cameras or sensors instead.

5. Will invisible payments replace traditional checkout completely?

Not entirely, but adoption is growing quickly. Many businesses will likely offer both options for years to come.

Also Read:

How Do Invisible Payments Work in Real Life? Ultimate Guide

How Do Modern Brands Manage B2B Payments? Ultimate Guide

How Does Fintech Speed Up Logistics Payments

How Does Fintech Speed Up Logistics Payments? Ultimate Guide

Fintech for Logistics & Supply Chain Payments

Moving goods across the world is only half the challenge. Moving money through the supply chain is often harder. Fintech for logistics is solving this problem in ways that seemed impossible just a few years ago. Payments that once took weeks now settle in days or even hours.

Supply chains involve many players. Shippers, carriers, warehouses, and vendors all need to get paid on time. Delays anywhere in that chain create ripple effects everywhere else. This is where fintech for logistics steps in, connecting payment systems directly to operational data.

This article explains why traditional payment methods struggle in logistics, how fintech solves those problems, and what benefits businesses can expect. Let us explore the details.

Why Traditional Payments Struggle In Logistics

Logistics has always run on tight margins and tighter timelines. Traditional banking systems were never built for this pace.

Paper invoices still exist in many supply chains today. Someone has to manually match invoices to shipments. Errors happen often, and disputes take days to resolve. Meanwhile, carriers wait for payment while covering fuel and driver costs upfront.

Cross-border transactions add another layer of complexity. Currency conversion, compliance checks, and banking hours vary by country. As a result, international shipments often face payment delays that have nothing to do with the goods themselves. This creates cash flow pressure across the entire chain.

Small carriers and independent truckers feel this pain the most. Waiting thirty or sixty days for payment can strain their operations badly. Consequently, many either raise prices or refuse certain jobs altogether. This limits capacity precisely when demand is highest.

Traditional systems also lack visibility. Finance teams often cannot see where a payment sits in the approval process. This lack of transparency leads to frustration on both sides of every transaction. Fintech for logistics directly addresses each of these pain points.

How Fintech For Logistics Solves Payment Problems

Fintech for logistics connects payment platforms directly to shipment and tracking data. Payments trigger automatically once delivery is confirmed.

This automation removes much of the manual work involved in invoice matching. Systems verify delivery status instantly using GPS and digital proof of delivery. Therefore, payments release faster with fewer disputes and less paperwork.

Real-time payment rails also play a major role. Instead of waiting for traditional bank transfers, funds move within hours through modern payment networks. Additionally, some platforms offer instant factoring, letting carriers get paid immediately for a small fee. This flexibility helps smaller operators manage cash flow more predictably.

Cross-border payments benefit significantly from fintech innovation too. Digital platforms handle currency conversion and compliance checks automatically. This reduces the delays that once made international logistics payments so frustrating. Similarly, built-in fraud detection protects both shippers and carriers from costly errors.

Data visibility improves dramatically as well. Finance teams can track every payment in real time through a single dashboard. They see exactly where funds are in the process at any given moment. This transparency builds trust between all parties involved in the transaction.

Key Benefits For Businesses Across The Supply Chain

Faster payments create advantages that extend well beyond simple convenience. The impact touches nearly every part of a logistics operation.

Improved cash flow tops the list for most companies. Carriers can accept more jobs when they are not waiting weeks for payment. Shippers benefit from stronger, more reliable carrier relationships as a result. Everyone in the chain operates with less financial stress.

Cost savings follow closely behind. Automated systems reduce the manual labor needed for invoice processing and reconciliation. Fewer errors mean fewer costly disputes and less time spent on corrections. Over time, these savings add up significantly for large operations.

Stronger partnerships also emerge from reliable, fast payments. Vendors and carriers prefer working with companies that pay consistently and quickly. This reputation can become a genuine competitive advantage in a tight labor market. Businesses that pay reliably often get priority access to capacity during peak seasons.

Better data also supports smarter decision-making. Finance leaders gain clear visibility into spending patterns across routes, vendors, and regions. This information helps identify cost-saving opportunities that were previously hidden in disconnected systems. Consequently, companies can negotiate better rates using real payment history as leverage.

Risk management improves too. Fintech platforms often include built-in fraud detection and compliance monitoring. This protects businesses from payment fraud, which remains a persistent risk in complex global supply chains.

Choosing The Right Fintech Partner For Logistics

Not every fintech platform fits every logistics business. Choosing the right partner requires careful evaluation.

Start by examining integration capabilities. The platform should connect easily with your existing transportation management and accounting systems. Poor integration creates new manual work instead of removing it. Therefore, this should be a top priority during evaluation.

Next, consider payment speed and flexibility. Look for platforms offering multiple payout options, including instant transfers for time-sensitive situations. Additionally, check whether the platform supports the currencies and regions relevant to your operations.

Security and compliance also deserve close attention. Verify that the provider follows strong data protection standards and relevant financial regulations. This matters even more for companies handling cross-border transactions regularly.

Finally, evaluate customer support and onboarding quality. A platform with excellent technology but poor support can slow your transition significantly. Ask potential partners about implementation timelines and available training resources before committing.

Working with experienced experts can simplify this decision considerably. Build your authority with Digital Payment Guru and modernize your logistics payment infrastructure with confidence.

How Does Fintech Speed Up Logistics Payments

Conclusion

Fintech for logistics is reshaping how money moves through global supply chains. Faster payments, better visibility, and stronger partnerships are no longer optional advantages. They are becoming baseline expectations across the industry.

Companies that adopt these tools early gain real operational advantages. They build stronger carrier relationships and reduce costly payment friction. Meanwhile, those relying on outdated systems risk falling behind competitors who move faster and pay smarter.

The shift toward digital, automated logistics payments will only accelerate. Businesses that prepare now will be ready to lead their markets tomorrow.

Frequently Asked Questions

1. What is fintech for logistics? Fintech for logistics refers to digital financial tools that automate and speed up payments across shipping, freight, and supply chain operations.

2. How does fintech reduce payment delays in supply chains? It connects payments directly to shipment and delivery data, triggering automatic transfers once delivery is confirmed instead of manual processing.

3. Is fintech for logistics useful for small carriers? Yes. Instant payment and factoring options help small carriers maintain healthy cash flow without waiting weeks for standard payment cycles.

4. Does fintech for logistics help with international payments? Yes. It automates currency conversion and compliance checks, reducing delays common in cross-border logistics transactions.

5. How do I choose the right fintech platform for my logistics business? Evaluate integration ease, payment speed, security standards, and customer support before selecting a fintech partner for your supply chain.

Also Read:

How Do EdTech Start-ups Simplify Payments? Ultimate Guide

How Is Creator Infrastructure Built Today? Complete Guide

How Do EdTech Startups Simplify Payments

How Do EdTech Start-ups Simplify Payments? Ultimate Guide

Payment Gateways for EdTech Platforms: Unique Challenges

Payment gateways for EdTech platforms are not like typical online checkout systems. Education businesses deal with parents, students, institutions, and even government bodies. Each group brings different expectations and payment habits.

This guide explores the real challenges EdTech companies face with payments. You will also learn practical ways to solve these problems. By the end, you will understand what separates a good payment gateway from a great one.

Whether you run a tutoring app, an online school, or a certification platform, these lessons apply to you. Payments may feel like a small detail. In truth, they shape the whole customer experience.

Why EdTech Payments Are Different

Traditional eCommerce involves one buyer and one seller. EdTech, however, often involves three parties. A parent pays, a student learns, and the platform delivers the service. This triangle creates unique friction points.

Also, EdTech platforms often serve global audiences. A single course might attract students from ten different countries. Each country has its own preferred payment methods, currencies, and regulations.

Trust also plays a bigger role in education payments. Parents want reassurance before paying for their child’s learning. So, payment gateways for EdTech platforms must feel secure and transparent at every step.

Subscription models add one more layer of complexity. Many EdTech platforms charge monthly or yearly fees. Managing renewals, failed payments, and cancellations requires a gateway built for recurring billing.

Institutional buyers add yet one more dimension. Schools and corporate training departments often pay in bulk, sometimes through invoicing rather than instant checkout. A payment gateway built only for individual consumers may struggle with these larger, slower-moving transactions.

Age also plays an unusual role in EdTech payments. Many learners are minors who cannot legally hold a payment method themselves. This means the actual payer is rarely the actual user, which complicates identity verification and consent tracking.

Common Challenges EdTech Platforms Face

The first major challenge is handling diverse payment methods. Some regions prefer credit cards, while others rely on digital wallets or bank transfers. A limited gateway can quickly turn away potential customers.

Currency conversion creates one more hurdle. International students expect prices in their local currency. Without proper conversion tools, EdTech platforms risk confusing or losing customers during checkout.

Compliance requirements add further pressure. Education platforms that collect payments from minors, through parents, must follow strict data protection rules. Similarly, financial regulations vary widely between countries and states.

Refunds and chargebacks are also more common in education than in typical retail. Students may request refunds after a few lessons, or parents may dispute charges. A strong payment gateway must handle these cases smoothly and fairly.

Meanwhile, failed subscription renewals cause quiet revenue loss. A card might expire, or a bank might decline a charge. Without smart retry logic, EdTech platforms lose subscribers without ever knowing why.

This kind of silent churn is easy to miss without proper monitoring. Many founders only spot the pattern after months of falling renewal rates. By then, real revenue has already slipped away.

Last, fraud prevention deserves special attention. Free trials and low-cost entry offers can attract fraudulent sign-ups. Payment gateways for EdTech platforms need built-in fraud detection to protect revenue and reputation.

Seasonal demand spikes also create pressure on payment systems. Enrollment periods, exam seasons, and back-to-school campaigns can multiply transaction volume overnight. A gateway that cannot scale quickly may slow down or fail during these key windows.

Tax handling across regions adds one more layer of difficulty. Digital education services face different tax treatment in different countries. Miscalculated tax at checkout can lead to compliance issues down the line.

Key Features to Look For in EdTech

A strong EdTech payment gateway supports multiple currencies by default. This feature alone can open access to new markets without extra development work.

Support for local payment methods matters just as much. In some countries, digital wallets dominate. In others, bank transfers remain the norm. The right gateway adapts to these regional preferences on its own.

Recurring billing tools are essential for subscription-based platforms. Look for automatic retry logic, renewal reminders, and simple cancellation flows. These features reduce churn and protect monthly revenue.

Similarly, strong security certifications build trust with parents and institutions. Look for gateways that meet recognized data protection standards. This reassurance often influences a parent’s decision to complete a purchase.

Flexible refund management also matters greatly. EdTech businesses need clear rules for partial refunds, course cancellations, and dispute resolution. A gateway with built-in refund workflows saves significant administrative time.

Last, detailed reporting tools help teams track revenue accurately. Clear dashboards make it easier to spot failed payments, refund trends, and regional performance differences.

Invoicing support is one more valuable feature for platforms that sell to schools or businesses. Bulk licensing deals often require formal invoices rather than instant card payments. A gateway that handles both consumer and institutional flows saves significant operational effort.

API flexibility should not be overlooked either. Development teams need clean documentation and reliable uptime. A gateway that is difficult to integrate can delay product launches and frustrate engineering teams.

How to Choose the Right Gateway for Your Platform

Start by mapping your audience. If most students come from one country, a local gateway may work well. However, global platforms need broader currency and payment method support.

Next, consider your pricing model. Subscription-heavy platforms should prioritize gateways with strong recurring billing tools. One-time course purchases, in contrast, may need simpler checkout flows instead.

It also helps to test customer support responsiveness before committing. Payment issues need fast resolution, especially during high-traffic enrollment periods. A slow support team can hurt both revenue and reputation.

So, many EdTech companies choose gateways that integrate easily with existing learning platforms. Smooth integration reduces development time and avoids technical headaches later.

Cost structure deserves careful comparison too. Transaction fees, currency conversion charges, and monthly costs all add up. Choose a gateway that balances affordability with the features your platform truly needs.

Last, ask about scalability plans before signing a contract. Your platform may serve a few hundred students today but thousands next year. The right gateway partner grows alongside your business without forcing a painful migration later.

Building Long-Term Trust With Learners and Parents

Trust does not end at checkout. Clear billing statements help parents recognize charges and avoid confusion. Vague transaction names often lead to disputes that could have been avoided entirely.

Proactive communication also matters. Sending renewal reminders before a subscription charge helps reduce surprise cancellations. Transparency at every step builds a stronger, longer-lasting relationship with your learners.

In the end, platforms that treat payment as part of the learning experience tend to win. They keep students longer. They also earn more word-of-mouth referrals from happy parents.

How Do EdTech Startups Simplify Payments

Conclusion

Payment gateways for EdTech platforms face challenges that typical eCommerce systems rarely encounter. Multiple stakeholders, global audiences, and subscription billing all add complexity to the payment process.

The right gateway solves these problems with flexible currency support, strong security, and reliable recurring billing tools. It also builds trust with parents and institutions through transparent, secure transactions.

Choosing wisely protects both revenue and reputation. A smart payment strategy frees EdTech platforms to focus on their real mission: teaching students well, everywhere.

Ready to strengthen your platform’s payment strategy? Build your authority with Digital Payment Guru and give your EdTech business the payment infrastructure it deserves.

Frequently Asked Questions

1. Why are payment gateways for EdTech platforms different from regular gateways?

EdTech involves multiple parties, global audiences, and subscription billing. These factors require more flexible payment solutions than typical retail checkouts.

2. What payment methods should EdTech platforms support?

Support credit cards, digital wallets, and local bank transfers. Offering multiple options reduces checkout abandonment across regions.

3. How can EdTech platforms reduce failed subscription payments?

Use gateways with smart retry logic and renewal reminders. These features recover failed payments before students lose access.

4. Are payment gateways for EdTech platforms secure for minors?

Reputable gateways follow strict data protection standards. Always verify compliance certifications before choosing a provider.

5. How important is currency support for EdTech platforms?

Very important, especially for global platforms. Local currency pricing improves trust and increases conversion rates a lot.

Also Read:

How Is Creator Infrastructure Built Today? Complete Guide

How Do Founders Pass VC Code Reviews? Ultimate Guide

How Do Regulators View Payment Arbitrage

How Do Regulators View Payment Arbitrage? Complete Guide

Regulatory Arbitrage in Payments: Opportunities & Risks

Payment companies operate across many countries and many rulebooks. Some businesses use gaps between these rules to their advantage. This practice is called regulatory arbitrage in payments. It can create real opportunities for growth and speed. However, it also carries serious risks for companies that misuse it. This guide explains regulatory arbitrage in simple, clear language. You will learn where opportunities exist and where danger hides. Additionally, you will see how responsible companies approach this strategy. Whether you are a fintech founder, compliance officer, or investor, this matters to you. Payments regulation keeps shifting across regions and product types. Therefore, understanding arbitrage helps you make smarter, safer decisions. This topic sits at the center of many boardroom conversations today. Global payment volumes keep rising, and so does regulatory attention on the sector. Consequently, the stakes around this strategy have never been higher. Let us break down what this term truly means in practice.

What Is Regulatory Arbitrage in Payments?

Regulatory arbitrage happens when a company structures its business to benefit from different rules. Different countries treat payment services differently under their laws. For example, one country may require a full banking license. Another country may allow the same service under a lighter framework. A payment company might choose to operate from the lighter jurisdiction. This choice can lower costs and speed up market entry significantly. Similarly, some firms route transactions through regions with fewer reporting rules. This is not automatically illegal, but it sits in a gray area. Regulators worldwide are increasingly aware of these patterns. As a result, enforcement actions against aggressive arbitrage have grown steadily. Consequently, companies must weigh short-term gains against long-term regulatory risk. A smart strategy considers both speed and sustainability together. Many successful fintechs have grown by finding legitimate regulatory efficiencies. However, the line between efficiency and evasion can be thin. Understanding this line is the first step toward responsible growth. Boards and investors now ask pointed questions about this exact distinction.

Consider a payment company processing cross-border remittances for small businesses. It might register in a jurisdiction with lighter capital requirements. This lowers upfront costs and speeds up its market launch considerably. At the same time, it must still meet the destination country’s rules for customers there. Ignoring those local obligations turns a smart strategy into a serious liability. This example shows why context always matters more than the label alone. Two companies can use similar structures with very different outcomes. The difference usually comes down to intent, transparency, and follow-through. Regulators tend to reward companies that communicate openly about their structure. In contrast, they tend to punish companies that appear to hide activity. This distinction shapes enforcement decisions far more than most people realize.

Where Payment Companies Find Arbitrage Opportunities

Several real opportunities exist within regulatory arbitrage today. Used well, these opportunities support faster and more affordable global growth. However, opportunity without careful planning can quickly become a liability. Every advantage found through arbitrage should be documented and clearly defensible.

Licensing Arbitrage

Companies can choose favorable jurisdictions for their payment charter. Some regions offer faster approval timelines for new payment licenses. This speed can be a genuine competitive advantage for new entrants. However, the chosen license must still match the company’s actual operations. A mismatch between license scope and real activity invites regulatory scrutiny. Legal teams should review license terms annually as the business evolves.

Product Arbitrage

Similar services sometimes face very different rules across jurisdictions. For instance, some regions treat stablecoins differently than traditional e-money. Smart companies structure products to fit clearer, lower-risk categories. This does not mean hiding the true nature of a product. Instead, it means designing offerings that align naturally with sound frameworks. Product teams and legal counsel should collaborate from the earliest design stage.

Geographic Arbitrage

A single license, passported across a region, can unlock many markets. This approach reduces the cost of expanding into each country separately. Companies serving global customers benefit from this kind of efficient structure. Still, passporting rules vary, and misunderstanding them can cause serious, costly delays. Local counsel in each target market helps avoid these avoidable setbacks.

Sandbox Arbitrage

Regulatory sandboxes let startups test products under relaxed, supervised conditions. These programs allow innovation without the full weight of standard rules. Many regulators use sandboxes to encourage responsible fintech experimentation. Companies that graduate from sandboxes often build stronger long-term regulatory relationships. This early trust can smooth the path toward a full, permanent license later. Companies should treat sandbox participation as a relationship investment, not just a shortcut.

Key Risks of Regulatory Arbitrage in Payments

Regulatory arbitrage also carries real and growing risks. Consumer protection gaps rank among the most serious of these risks. A lighter regulatory framework sometimes means weaker dispute resolution for customers. This can leave users without a clear path when transactions go wrong. Companies should never let cost savings come at the expense of user safety. The biggest risk overall is sudden regulatory change in the chosen jurisdiction. A friendly regulator today might tighten rules tomorrow without much notice. Companies built entirely around one loophole face serious business risk. Another risk involves reputational damage if arbitrage looks like evasion. Customers and partners may lose trust in a company seen as rule-avoiding. Additionally, cross-border enforcement cooperation has increased significantly in recent years. Regulators now share information across borders more than ever before. This makes hiding weak compliance practices much harder than in the past. A further risk involves banking partner relationships across the industry. Banks often refuse to work with payment firms seen as high-risk. This can suddenly cut off a company’s access to core banking services. Finally, aggressive arbitrage can trigger costly legal battles and heavy fines. These costs often outweigh any short-term savings gained earlier in the process. Leaders must weigh these risks honestly before choosing an arbitrage-heavy strategy. Insurance and legal costs also tend to rise sharply after enforcement actions begin. Talent retention suffers too, since skilled compliance staff avoid risky employers. Investors also price this risk into funding rounds for exposed companies. A firm with unclear regulatory footing often receives lower valuations. Furthermore, payment processors and card networks may terminate contracts without much warning. Losing a key network relationship can halt operations almost overnight. These cascading effects show why regulatory risk deserves board-level attention, not just legal review. Boards that treat compliance as a strategic topic, not an afterthought, manage this risk far better.

How to Approach Regulatory Arbitrage Responsibly

Responsible companies treat regulatory arbitrage as one tool, not a whole strategy. First, they build compliance into product design from day one. This means working with regulators instead of only trying to avoid them. Second, they diversify licenses across multiple strong, well-regarded jurisdictions. This reduces dependence on any single regulatory environment or relationship. Third, they invest in strong anti-money laundering and reporting systems everywhere. Good compliance infrastructure protects the company regardless of where rules shift. Fourth, they monitor regulatory news across every market they actively serve. Early warning allows time to adjust before problems grow genuinely serious. Fifth, they work with experienced legal and compliance advisors continuously. These experts help separate real opportunity from real, costly danger. Companies that follow this balanced approach grow steadily and sustainably over time. They avoid the boom-and-bust cycle common among aggressive arbitrage players. This path takes more effort but produces far more durable results over time. Regular internal audits also help confirm that practice matches stated policy. Transparent reporting to regulators, even when not strictly required, builds valuable goodwill. Sixth, mature companies build a clear escalation path for compliance concerns. Staff at every level should feel safe raising questions without fear. Seventh, leadership reviews regulatory strategy alongside business strategy, not separately. This integration prevents growth targets from quietly overriding compliance judgment. Companies that embed this discipline into daily operations rarely face sudden regulatory shocks.

How Do Regulators View Payment Arbitrage

Conclusion

Regulatory arbitrage in payments offers real, legitimate opportunities for growth. It also carries risks that can threaten a company’s entire future. The smartest payment leaders treat arbitrage as one input among many decisions. They combine it with strong compliance, diversified licensing, and honest risk assessment. This balanced approach protects both growth and reputation over time. As global payment rules continue evolving, this balance will only matter more. Companies that master this balance will lead the next wave of payment innovation. Getting expert guidance early often saves far more than it costs later. A trusted advisor can help you spot genuine opportunities before competitors do. They can also help you avoid the costly missteps that damage long-term trust. In payments, reputation and compliance often matter as much as speed to market. The companies that respect this balance tend to outlast the ones that do not.

Build your authority with Digital Payment Guru. Get expert guidance on navigating payment regulation with confidence and clarity.

Frequently Asked Questions

1. Is regulatory arbitrage in payments legal?

It can be legal when structured transparently and within the rules of every jurisdiction involved. Problems arise when companies hide activity or ignore local customer protection laws.

2. What is the biggest risk of regulatory arbitrage?

Sudden regulatory change is the biggest risk. A jurisdiction with light rules today may tighten them quickly, leaving a company’s whole model exposed.

3. How does licensing arbitrage work in payments?

Companies choose jurisdictions with faster approvals or lighter licensing requirements. This speeds up market entry, but the license must still match real business activity.

4. Can regulatory sandboxes help fintech startups?

Yes, sandboxes let startups test products under supervised, relaxed conditions. This builds regulatory trust and often smooths the path to a full license later.

5. How can payment companies reduce regulatory risk?

Diversifying licenses, investing in compliance systems, and monitoring regulatory news all help. Working with experienced advisors also reduces long-term regulatory risk significantly.

Also Read:

How Financial Regulations in India Shape Fintech Growth?

How Do Founders Pass VC Code Reviews? Ultimate Guide

How to Lower Payment Gateway Fees with One Simple Tool

How to Lower Payment Gateway Fees with One Simple Tool

You run a business that accepts online payments. Therefore, payment processing fees are a major expense. However, these fees are often complex. They can hide many different costs. Truly, many businesses pay too much without realizing it. This is where the Payment Gateway Cost Calculator becomes essential. This tool helps you see your true costs clearly.

Some business owners just accept the fees they are given. But, this can cost them thousands of dollars yearly. Consequently, understanding the total cost is vital for saving money. Always remember, a Cost Calculator brings transparency to the complex world of transaction fees. By using this simple tool, you can accurately compare providers. This helps you choose the best gateway for your specific volume. It also maximizes your profit margins easily.

How to Lower Payment Gateway Fees with One Simple Tool

The Fee Maze: Why Payment Processing is Confusing

First, let’s look at the problem. Why are payment processing fees so confusing for businesses? Gateways charge more than just a simple percentage. They use many different fee types. Clearly, this creates a complex fee structure. Therefore, understanding the fee maze is the first step to finding a solution.

Hidden Costs That Reduce Your Profit

These common fees often hide the true cost of a payment gateway:

  • Transaction Fees: A percentage and a fixed amount per sale (e.g., 2.9% + $0.30).
  • Interchange Fees: These go to the bank that issued the customer’s card.
  • Assessment Fees: These go to the card brands (Visa, Mastercard).
  • Monthly Fees: A fixed fee charged every month, regardless of sales volume.
  • Setup Fees: A one-time charge to start the service.
  • Chargeback Fees: A penalty fee when a customer disputes a transaction.
  • Refund Fees: Some providers charge a small fee when you process a refund.

A Payment Gateway Cost Calculator helps you put all these numbers together. It shows you the total effective rate you are actually paying.


What is a Cost Calculator? Your Transparency Tool

So, what exactly is a Payment Gateway Cost Calculator? It is a simple online tool. You enter your specific business data. Then, the tool estimates your total monthly or yearly processing costs. Truly, it provides a transparent, apples-to-apples comparison of providers. It ensures you are not surprised by hidden fees later.

How the Calculator Delivers Clarity

Here is how the Cost Calculator helps your business:

  1. Total Cost View: It sums up all fee types (monthly, per transaction, chargebacks) into one final number.
  2. Comparison Power: You can input the fee structures of different gateways. You can then compare them easily side-by-side.
  3. Volume Sensitivity: It shows how your effective fee rate changes as your sales volume grows or shrinks.
  4. Negotiation Leverage: Knowing your expected total cost gives you power to negotiate with providers.
  5. Budgeting Accuracy: It gives you a highly accurate prediction for your monthly payment processing budget.
  6. Finding the Right Plan: It helps determine if a flat-rate plan or an interchange-plus plan is better for you.

Truly, the Cost Calculator changes the game. It moves the power from the payment processor back to the business owner.


Pillar 1: Key Data Inputs for Accurate Cost Calculation

To get accurate results from any Payment Gateway Cost Calculator, you must input the correct data. Clearly, the calculator is only as good as the information you provide. Therefore, gather these key figures before you start using the tool.

Essential Business Metrics Needed by the Tool

Firstly, input your average monthly sales volume. This is the total dollar amount of sales you process each month. This is the most important number. Secondly, input your average transaction size. This is the dollar amount of a typical single sale. This number affects fixed per-transaction fees.

Furthermore, enter your expected number of transactions per month. Do not just estimate this. Divide your total sales volume by your average transaction size. Also, note your chargeback rate. If you average two chargebacks per month, enter that number. This helps estimate chargeback fee costs. Lastly, enter the fee structure of the provider you are analyzing. Input the percentage fee, the fixed fee, and the monthly fee. Truly, providing accurate, specific data ensures the calculator gives you a reliable estimate. This prevents any bad surprises later.


Pillar 2: Comparing Fee Structures Side-by-Side

The biggest value of the calculator is its ability to compare different fee models. Many businesses incorrectly assume one fee structure is better than another. Clearly, your business volume dictates the best plan. Therefore, use the calculator to compare options directly.

Flat Rate vs. Interchange-Plus Fees

Firstly, test the flat rate model. This is simple. You pay one percentage and one fixed fee for every transaction (e.g., 2.9% + $0.30). This is usually best for businesses with low volume and high average sales prices. Secondly, test the interchange-plus model. This is more complex. You pay the actual interchange fee plus a small markup to the gateway. This is often better for high-volume businesses.

Furthermore, use the calculator to find the crossover point. Input both models. See at what sales volume the cheaper plan changes. This helps you select the right plan for your current size. Also, include the hardware cost. If a provider requires a special terminal, include that one-time cost in your calculation. Lastly, look at the monthly fees. If your sales volume is very low, a provider with zero monthly fees might save you more money, even if the per-transaction fee is slightly higher. Truly, the calculator takes the guesswork out of fee comparison. It shows the most cost-effective solution based on your real-world sales data.


Pillar 3: Reducing Hidden Costs and Increasing Profit

The Cost Calculator is not just for comparison. It is also a powerful tool for strategic profit management. You can use it to identify and reduce hidden costs over time. Clearly, every dollar saved in fees is a dollar added to your profit. Therefore, use the tool to regularly audit your costs.

Auditing Your Costs for Maximum Savings

Firstly, use the calculator for quarterly audits. Every three months, input your current processing data into the calculator. Compare the total cost it calculates to your actual bank statement charges. This helps you spot overcharges. Secondly, analyze chargeback cost impact. Use the calculator to see how increasing your chargeback rate impacts your overall effective rate. This emphasizes the need for better fraud prevention.

Furthermore, use the tool to model pricing changes. If you are considering raising your average sale price, see how that change impacts your percentage fees. Also, model refund fee costs. If your refund rate is high, use the calculator to show the total money you lose on refund fees. This might prompt you to improve product quality. Lastly, leverage the data for negotiation. If the calculator shows you are paying 0.5% more than the market average, use that data to ask your current provider for a lower rate. Truly, the Payment Gateway Cost Calculator acts as an ongoing financial manager. It constantly works to identify potential savings for your business.


Best Practices: Using the Calculator Effectively

To get the most value from a Payment Gateway Cost Calculator, you must use it consistently and correctly. It is a decision-making tool, not just a one-time gimmick. Clearly, adopting a smart approach ensures long-term cost savings. Therefore, integrate the calculator into your financial review process.

Tips for Maximizing the Calculator’s Value

Firstly, use multiple calculators. Compare results from two or three different cost calculators. This helps ensure accuracy. Secondly, always read the fine print of the provider’s fee schedule. The calculator relies on you accurately inputting all fees, including small, obscure ones.

Furthermore, model future growth. Input your current volume. Also, input a projected volume 12 months from now. See which provider scales best as your sales increase. Also, focus on the effective rate. This is the total dollar cost of processing divided by the total dollar sales. This is the only true measure of cost. Lastly, do not choose based on fees alone. Consider customer service, security features, and ease of integration alongside the cost. Truly, using the Cost Calculator wisely makes you a confident decision-maker. It ensures you choose a gateway that supports your financial health now and in the future.


Frequently Asked Questions (FAQs)

Q1: Can a Cost Calculator predict my exact monthly bill?

No, it cannot predict the exact bill. It gives a highly accurate estimate. The exact final bill depends on variable factors. These include the mix of card types your customers use and the number of chargebacks you receive.

Q2: Is the interchange-plus model always better for high-volume businesses?

It is usually better, but not always. The interchange-plus model gives high-volume businesses more transparency and often a lower effective rate. However, a business must have very high sales volume to benefit significantly.

Q3: Do free payment gateways really have zero cost?

No. Gateways that advertise “no monthly fees” still charge the per-transaction fees (a percentage and a fixed amount). This is how they make money. You must always use the calculator to find the effective rate.

Q4: If I switch to a cheaper gateway, will the integration be difficult?

Switching gateways can involve development work. The complexity depends on your e-commerce platform. Using a calculator to ensure the cost savings are substantial makes the effort worthwhile.

Q5: What is the single most important number to enter into the calculator?

The single most important number is the average transaction size. The fixed fee component (e.g., $0.30) has a much larger impact on small transactions than on large ones.

Also Read: The Key to Payment Gateways: Perfect Landing Pages

Â