Invisible Payments: The Rise of Pay Without Checkout Experiences
Introduction
Imagine leaving a store without scanning a single item. No line, no card swipe, no waiting. This is the idea behind invisible payments. These systems let customers pay without checkout, using sensors, apps, or stored payment details. Furthermore, this trend is growing fast across retail, transportation, and food service. Businesses are adopting invisible payments to reduce friction and boost customer satisfaction. In this article, we explore how invisible payments work. We will also look at their benefits, challenges, and future potential. Whether you run a store or simply enjoy smoother shopping, this guide has useful insights for you.
Main Section 1: What Are Invisible Payments?
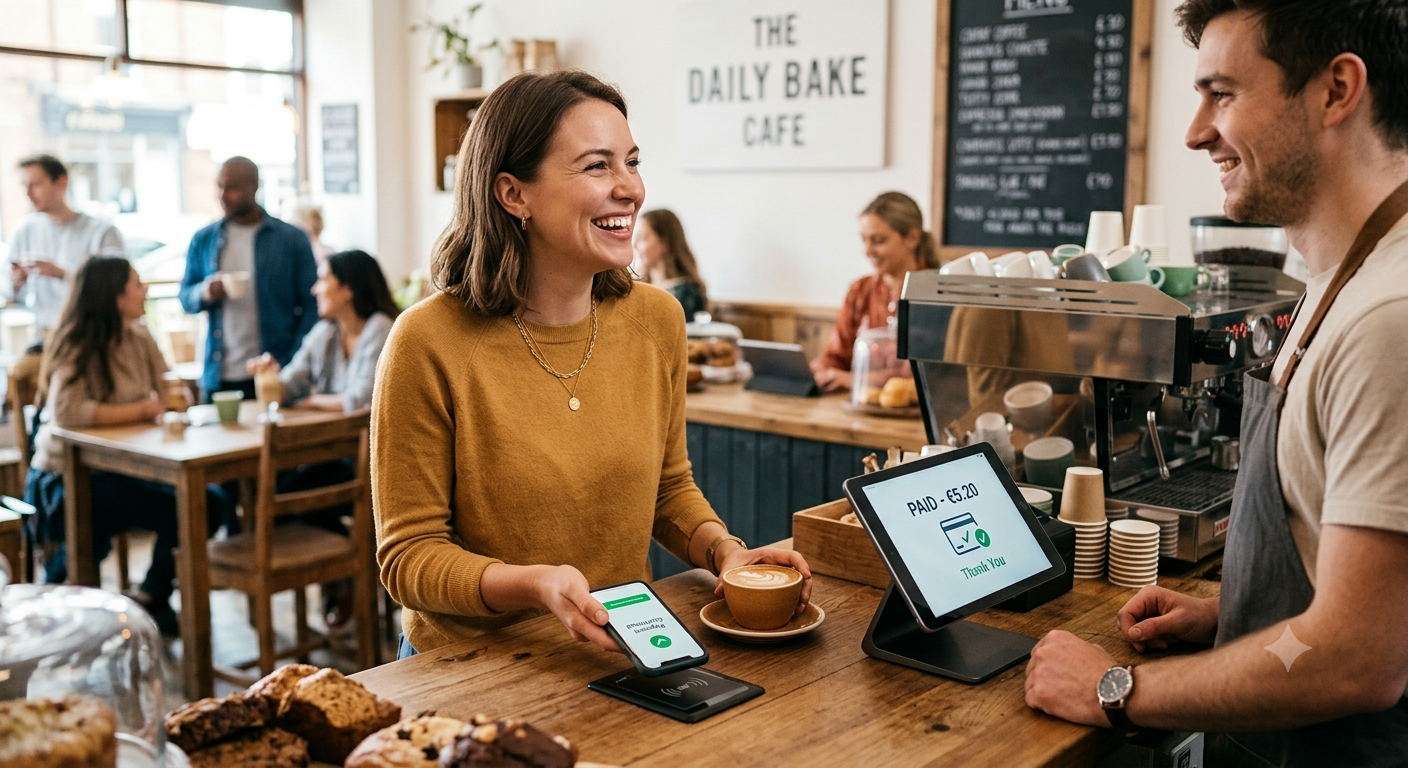
Invisible payments remove the traditional checkout step entirely. Customers link their payment method to an app or account beforehand. Then, sensors or scanners detect what they take or use. Payment happens automatically in the background. As a result, there is no register, no line, and no manual transaction.
This concept already exists in several familiar forms. Ride-sharing apps charge riders automatically after each trip. Similarly, some grocery stores use camera systems to track purchases. Toll roads have used similar technology for years through automatic vehicle scanning. Each example shares one goal: removing friction from the payment moment.
Invisible payments rely on a mix of technologies. These include mobile apps, RFID tags, computer vision, and secure cloud accounts. Consequently, the customer experience feels almost magical. However, strong technology and data security work behind the scenes to make it possible.
Main Section 2: Why Invisible Payments Are Growing So Quickly
Consumer expectations have shifted dramatically in recent years. People want speed and simplicity in every transaction. Long checkout lines feel outdated compared to instant digital experiences. Therefore, businesses are racing to remove this pain point.
Mobile technology has also matured significantly. Most customers now carry smartphones with secure payment apps installed. This makes background payments easier to implement safely. Meanwhile, advances in computer vision and sensor technology have dropped in cost. This allows more businesses to afford invisible payment systems.
Additionally, the pandemic accelerated contactless payment adoption worldwide. Many customers now prefer minimal physical interaction during purchases. Invisible payments take this preference one step further. There is no card tap and no manual entry required at all.
Retailers also benefit financially from faster transactions. Shorter wait times often lead to higher customer satisfaction scores. In turn, satisfied customers tend to spend more and return more often. This creates a strong business case for adopting invisible payment technology.
Main Section 3: Real-World Examples of Pay Without Checkout
Several industries already use invisible payment models successfully. Cashierless convenience stores let shoppers grab items and simply walk out. Cameras and weight sensors track every item automatically. Payment then processes through the customer’s linked account.
Ride-hailing and food delivery apps offer another clear example. Users never exchange cash or cards during their trip or order. Instead, payment happens instantly once the service is complete. This model has become the standard across most delivery platforms today.
Public transportation systems have also embraced invisible payments. Contactless transit cards and tap-to-ride systems reduce boarding delays. Some cities are even testing facial recognition for fare collection. Similarly, smart parking systems now charge drivers automatically upon exit.
Hotels and gyms are exploring similar technology too. Guests can access rooms and pay for extra services without visiting a front desk. As these examples show, invisible payments extend far beyond retail stores.
Main Section 4: Challenges and Considerations for Businesses
Despite clear benefits, invisible payments come with real challenges. Security remains the top concern for most businesses and customers. Storing payment details requires strong encryption and fraud protection systems. Without proper safeguards, businesses risk data breaches and customer trust loss.
Privacy is another important consideration. Camera-based tracking systems collect detailed shopper behavior data. Consequently, businesses must clearly explain how this data gets used. Transparent privacy policies help build customer confidence in these systems.
Implementation costs can also be significant. Sensors, cameras, and software integration require upfront investment. Smaller businesses may need to start with simpler versions of this technology. For example, app-based payment systems cost less than full computer vision setups.
Employee training matters as well. Staff need to understand new systems and assist customers during the transition period. Meanwhile, businesses should plan for occasional technical issues. Backup payment options should always remain available for reliability.
Finally, customer education plays a key role in adoption. Some shoppers may feel hesitant about automatic payments at first. Clear signage and simple onboarding can ease this concern effectively.
Conclusion
Invisible payments are reshaping how customers experience transactions everywhere. From cashierless stores to automatic ride payments, checkout-free experiences are becoming common. Businesses that adopt this technology thoughtfully can boost speed and satisfaction. However, success requires strong security, clear privacy practices, and proper customer education. As technology continues advancing, invisible payments will likely become the new standard. Companies that prepare today will lead this shift tomorrow.
Frequently Asked Questions
1. What are invisible payments?
Invisible payments let customers complete purchases without a traditional checkout. Sensors or apps handle the transaction automatically in the background.
2. Are invisible payments safe to use?
Yes, when businesses use strong encryption and fraud protection. Security measures protect customer data throughout every transaction.
3. Which industries use invisible payments today?
Retail, transportation, food delivery, and hospitality industries already use invisible payment systems successfully.
4. Do invisible payments require a smartphone?
Most invisible payment systems use a smartphone app or linked account. However, some use cameras or sensors instead.
5. Will invisible payments replace traditional checkout completely?
Not entirely, but adoption is growing quickly. Many businesses will likely offer both options for years to come.