How Do You Handle CTO Transitions Without Friction

How Do You Handle CTO Transitions Without Friction? Ultimate Guide

When Your Co-Founder CTO Steps Down: Maintaining Product Momentum During Executive Technology Transitions

Losing a technical co-founder is one of the hardest moments a startup can face. The CTO often holds deep product knowledge, technical vision, and team trust. When they step down, uncertainty spreads quickly.

However, this moment does not have to derail your company. With the right approach, founders can maintain product momentum and keep the team focused. This guide explains how to manage a co-founder CTO transition without losing direction.

We will cover communication, technical continuity, and rebuilding confidence across your team and stakeholders.

Why CTO Transitions Feel So Disruptive

A co-founder CTO is not just an employee. They often carry unwritten knowledge about the codebase, architecture decisions, and product history. This makes their exit feel especially disruptive.

Engineering teams may worry about direction. Without clear leadership, priorities can become unclear, slowing down development significantly. Meanwhile, other departments may question the company’s overall stability.

Investors also pay close attention to leadership changes. A sudden CTO exit can raise concerns about internal conflict or company health, even when the departure is amicable. Managing this perception carefully matters just as much as managing the technical transition.

Customers, too, may notice delays if product releases slow down. Therefore, addressing the transition quickly and transparently helps protect relationships across every stakeholder group.

Immediate Steps After a Co-Founder CTO Steps Down

The first priority is communication. Inform your engineering team directly and honestly. Avoid vague statements that create more questions than answers.

Next, identify an interim technical leader immediately. This could be a senior engineer, another co-founder, or an external advisor. Having someone visible in charge prevents confusion during the transition period.

Document critical technical knowledge as soon as possible. Schedule sessions with the departing CTO, if possible, to capture architecture decisions, system dependencies, and ongoing project details before they leave.

Review your product roadmap next. Some projects may need to pause temporarily while priorities are reassessed. Being honest about short-term delays is better than overpromising and missing deadlines later.

Finally, communicate with investors proactively. A clear, confident explanation of your transition plan reassures stakeholders far more than silence or delayed updates.

Maintaining Product Momentum During the Transition in CTO

Momentum is easy to lose during leadership gaps. To prevent this, focus on smaller, achievable milestones instead of large, complex projects during the transition period.

Empower your engineering team to make decisions within clear boundaries. Micromanaging during uncertainty often slows progress further. Instead, trust your team’s expertise while providing clear priorities.

Consider bringing in a fractional or interim CTO if the transition will take time. This provides technical guidance without rushing a permanent hiring decision under pressure.

Regular check-ins help maintain visibility into progress. Weekly updates, even brief ones, keep everyone aligned and reduce uncertainty about project status.

It also helps to celebrate small wins publicly during this period. Highlighting completed features or resolved issues reassures the team that progress continues despite the leadership change.

Finding the Right Long-Term Technical Leadership in CTO

Rushing to hire a permanent CTO often leads to poor fit. Instead, take time to clearly define what your company needs from its next technical leader.

Consider whether you need someone focused on scaling infrastructure, building new products, or managing a growing engineering team. These are very different skill sets, and clarity here prevents costly hiring mistakes.

Involve your engineering team in the hiring process where appropriate. Their input helps identify candidates who will fit well within existing team culture and technical practices.

External advisors or board members can also provide valuable guidance during this search. Their outside perspective often helps founders avoid rushed decisions driven by short-term pressure.

Once you find the right candidate, plan a thoughtful onboarding process. Introduce them properly to the team, existing systems, and ongoing projects to set them up for success from day one.

Rebuilding Team and Stakeholder Confidence

Trust takes time to rebuild after a major leadership change. Consistent, transparent communication is the most effective tool founders have during this period.

Share regular updates about progress, even when there is no major news to report. Silence often creates more anxiety than honest, incremental updates.

Recognize the emotional impact on your team as well. A co-founder leaving can feel personal, even for employees who were not close to them directly. Acknowledging this openly shows strong, empathetic leadership.

With investors, focus on demonstrating continued execution. Hitting product milestones, even small ones, proves that the company remains stable and capable despite the transition.

Over time, consistent delivery rebuilds confidence more effectively than any single announcement or reassurance ever could.

Protecting Engineering Culture Through the Change

Engineering culture often reflects the personality of its technical founder. When that person leaves, culture can shift in subtle but important ways.

Pay attention to team rituals that mattered under the previous leadership. Code review practices, planning meetings, and communication norms often carry the departing CTO’s influence. Decide deliberately which practices to keep and which may need adjustment.

Involve senior engineers in preserving what worked well. They often understand the day-to-day culture better than founders who are less involved in technical details. Their input helps maintain continuity even as leadership changes.

At the same time, avoid forcing every practice to stay exactly the same. New leadership, even interim leadership, may bring valuable improvements. Balance respect for existing culture with openness to healthy evolution.

Clear documentation also protects culture during transitions. Written guidelines on coding standards, deployment processes, and team norms reduce reliance on any single person’s institutional memory going forward.

Learning from Companies That Handled This Well

Many successful companies have navigated co-founder CTO transitions without losing momentum. A common thread among them is early, proactive planning rather than reactive scrambling.

These companies often maintain detailed technical documentation continuously, not just during a crisis. This habit alone significantly reduces the disruption caused by any sudden leadership change.

They also tend to build strong second-tier technical leadership early. Senior engineers who can step up temporarily provide a natural safety net during unexpected transitions.

Clear, calm communication during the actual transition period is another shared trait. Founders who address concerns directly, rather than avoiding difficult conversations, tend to retain team trust more effectively.

Finally, these companies treat the transition as a growth opportunity rather than purely a setback. New leadership sometimes brings fresh perspective that strengthens the product and team culture over time.
How Do You Handle CTO Transitions Without Friction

Conclusion

A co-founder CTO stepping down is undoubtedly challenging, but it does not have to derail your company’s progress. Clear communication, strong interim leadership, and a thoughtful hiring process can help maintain product momentum throughout the transition.

Focus on transparency with your team, investors, and customers. With the right approach, your company can emerge from this transition stronger and more resilient than before.

Frequently Asked Questions

1. What should founders do immediately after a co-founder CTO leaves? Communicate honestly with the team, appoint interim technical leadership, and document critical technical knowledge before the transition is complete.

2. Should we rush to hire a new CTO? No. Taking time to define your exact needs leads to better long-term hiring decisions than rushing under pressure.

3. How do we maintain investor confidence during a CTO transition? Proactive, transparent communication and continued product execution help maintain investor trust during leadership changes.

4. Can an interim CTO help during this period? Yes, a fractional or interim CTO can provide technical guidance while you search for a permanent replacement.

5. How long does a typical CTO transition take? This varies widely, but most startups need several months to fully stabilize leadership and hire the right long-term replacement.

Also Read:

How Does a Virtual CTO Compare to Full-Time CTOs? Ultimate Guide

How Do You Implement AI Dynamic Pricing Today? Ultimate Guide
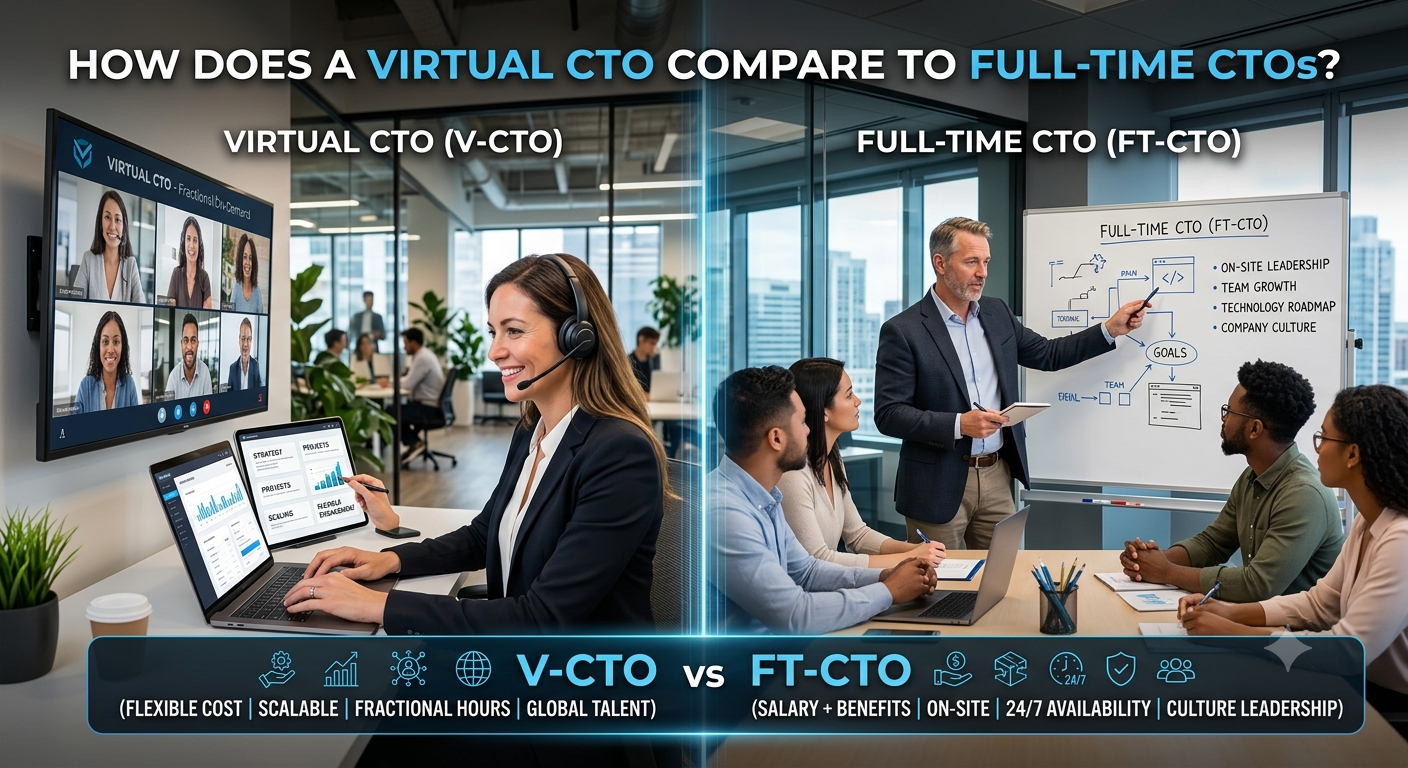
How Does a Virtual CTO Compare to Full-Time CTOs

How Does a Virtual CTO Compare to Full-Time CTOs? Ultimate Guide

Virtual CTO for FinTech Startups: Architecting Banking API Integrations With Zero Downtime

Fintech founders face a tough puzzle. You must launch fast, stay secure, and never let payments fail. Yet many startups cannot afford a full-time chief technology officer. Therefore, a virtual CTO for fintech startups can be a smart answer. This expert guides your technology plan on a flexible basis. One of the hardest tasks is connecting to banks through APIs without any downtime. This guide explains how a virtual CTO approaches that job. You will also learn the design habits that keep money moving.

What Is a Virtual CTO for FinTech Startups?

A virtual CTO is a senior technology leader who works with you part time or on contract. Some people call this role a fractional CTO. The person sets your tech strategy, guides your engineers, and reviews key choices. You pay only for the time you need. That makes the model a smart fit for early-stage teams.

Fintech adds special pressure to this role. Your product handles real money and sensitive data. Regulators watch closely, and customers lose trust fast after an outage. A virtual CTO who knows fintech understands these risks. They bring experience from many projects, so you avoid common traps.

Typical duties are broad. They pick the tech stack and design the system architecture. They set security standards and plan for compliance rules such as PCI DSS. Hiring and coaching developers is part of the job too. Most of all, they connect tech choices to business goals.

Compare this with a full-time CTO. A full-time hire costs more and may take months to find. A virtual CTO can start within weeks. As your company grows, you can move to a full-time leader with a clean plan already in place.

Consider a small payments startup with five engineers. The team knows how to build features but lacks bank experience. A virtual CTO reviews the plan, spots weak points, and sets clear standards. Developers gain confidence, and the founder gains a trusted adviser. Moreover, investors like to see this level of technical care.

Why Banking API Integrations Are Hard

Banking APIs let your app talk to banks and payment networks. They power account checks, payments, and balance data. Open banking rules in many regions make these APIs more common. However, each bank works differently. Formats, limits, and rules vary widely.

Banks also change systems without much warning. An API may slow down, return odd errors, or go offline for maintenance. Your product must handle all of this smoothly. A single weak link can freeze payments for thousands of users.

Security adds more weight. You must protect tokens, keys, and customer data at every step. Rules require strong authentication and careful logging. Mistakes can lead to fines and lost trust.

For these reasons, integration cannot be an afterthought. It needs a clear architecture from day one. That is exactly where a virtual CTO adds value.

Cost is another factor. Every hour of downtime can mean failed payments and angry customers. Support tickets rise, and partners start to worry. Additionally, repeated outages may put your bank relationship at risk. Prevention is always cheaper than recovery, and it keeps your team calm.

How a Virtual CTO Designs for Zero Downtime

Zero downtime means your service stays available even when parts fail or change. No system is perfect, but good design gets very close. Here are the core ideas a virtual CTO uses.

Build a Clean API Gateway Layer

A gateway sits between your app and every bank API. Your core product talks only to the gateway. The gateway handles each bank’s format, rules, and quirks. If a bank changes something, you fix one place instead of many. This also makes adding new banks much faster.

Use Retries, Timeouts, and Circuit Breakers

Networks fail often, so plan for that. Smart retries try again after a short pause. Timeouts stop your system from waiting forever. A circuit breaker cuts off a failing service for a moment so it cannot drag everything down. Together, these tools keep small problems small.

Make Payments Safe to Repeat

However, retries can cause double payments if you are careless. The fix is called idempotency. Each payment request carries a unique key. If the same request arrives twice, the system processes it only once. This protects customers and your reputation.

Add Backup Routes and Queues

Never depend on one bank connection for critical flows. A backup provider can take over when the main one fails. Message queues store requests safely during a slowdown. As a result, work continues once the service recovers. Customers see a short delay instead of an error.

Data consistency deserves attention too. When a payment moves between systems, every record must match. Reconciliation jobs compare your ledger with bank statements each day. Any gap triggers an alert. This habit catches quiet errors before customers notice them.

Release Without Stopping the Service

Deployments often cause outages. Blue-green deployment avoids this. You run the new version next to the old one and switch traffic only after tests pass. If something breaks, you switch back in seconds. Feature flags let you turn new code on for a few users first.

Testing, Monitoring, and Compliance

However, design alone is not enough. Teams must test and watch the system all the time. A virtual CTO builds these habits into your culture.

Start with sandbox testing. For example, most banks offer test environments. Run real scenarios there, including failures and slow responses. Load tests show how your system behaves at peak traffic. Chaos tests, which break parts on purpose, reveal hidden weak spots.

Monitoring comes next. Track response times, error rates, and payment success rates. Set alerts that reach the right person quickly, day or night. Dashboards should show the health of every bank connection at a glance. Clear logs help your team find causes in minutes, not hours.

Meanwhile, compliance needs equal care. Encrypt data in transit and at rest. Limit access with roles and strong authentication. Keep audit trails for every payment action. Plan regular security reviews and penetration tests. These steps satisfy regulators and calm nervous partners.

Finally, prepare for incidents. Write a simple runbook that explains who does what during an outage. Practice it with your team. After each incident, hold a blameless review and fix the root cause. Over time, your platform becomes tougher and easier to trust.

How to Work With a Virtual CTO for FinTech Startups

Set clear goals before you start. Do you need an architecture plan, a team review, or a compliance roadmap? Agree on deliverables and a schedule. Decide how you will measure success after three months. Ask for regular reports in plain language.

Look for real fintech experience. Ask about past banking API projects and how they handled outages. Check references and past results. Ask to see sample architecture notes or reports. A good virtual CTO explains complex ideas simply and listens to your business needs.

Treat the relationship as a partnership. Give access to your team, your data, and your roadmap. Involve your developers in decisions so knowledge stays in-house. Review progress each month. The best outcome is a stronger internal team that can run without constant outside help.

Conclusion: Keep Payments Running With the Right Tech Leadership

A virtual CTO for fintech startups gives you expert leadership without the cost of a full-time hire. Clean gateways, safe retries, backup routes, and careful releases help banking API integrations run with zero downtime. Strong testing, monitoring, and compliance make the system even more reliable. If your startup is growing fast, now is a great time to get expert guidance. Solid technology today protects your customers and your future. Take the first step by reviewing where your current integrations might fail.

How Does a Virtual CTO Compare to Full-Time CTOs

Frequently Asked Questions

What does a virtual CTO for fintech startups do?

A virtual CTO sets technology strategy, designs architecture, and guides engineers on a part-time basis. In fintech, they also focus on security, compliance, and banking API integration.

How is a virtual CTO different from a full-time CTO?

A virtual CTO works flexibly and costs less. A full-time CTO is embedded daily in your company. Many startups begin with virtual leadership and hire full-time later.

How can banking API integrations have zero downtime?

Use a gateway layer, retries, circuit breakers, backup providers, and blue-green releases. Add strong monitoring so problems are caught early.

When should a fintech startup hire a virtual CTO?

Hire one when you plan your first product build, prepare for a bank partnership, or face scaling problems. Early guidance prevents costly rework.

What is idempotency in payment APIs?

Idempotency means the same request gives the same result, even if sent twice. It stops duplicate charges when a retry happens.

Also Read:

How Do You Implement AI Dynamic Pricing Today? Ultimate Guide
How Do Modern Brands Manage B2B Payments? Ultimate Guide

How Smart Payment Routing Logic Really Works: Complete Guide

How Smart Payment Routing Logic Really Works: Complete Guide

Every failed payment costs money. It costs the transaction, the customer, and sometimes the relationship. Smart payment routing logic changes that. It sends each transaction through the best possible path — automatically and in real time.

This blog explains how routing logic works, why it matters, and how businesses use it to dramatically improve payment success rates.

What Is Payment Routing Logic?

Payment routing logic is the set of rules that determines which payment processor handles a given transaction. Every payment involves multiple parties — the merchant, the payment gateway, the processor, the card network, and the issuing bank. When a transaction fails, it usually fails at one of these points.

Smart routing logic evaluates each transaction before sending it. Furthermore, it considers factors like card type, geography, transaction size, and processor performance history. Based on these factors, it selects the processor most likely to approve the payment.

Think of it like GPS for payments. Instead of always taking the same route, it calculates the fastest, most reliable path in real time. Consequently, more payments reach their destination successfully.

How Smart Payment Routing Logic Really Works: Complete Guide

Why Payment Failures Happen

Understanding failures is essential before solving them. Payments fail for several reasons. Soft declines happen when the issuing bank temporarily rejects a transaction. These include insufficient funds, suspected fraud flags, or processor downtime. Importantly, soft declines can often be recovered with a retry on a different processor.

Hard declines are permanent rejections. Expired cards, closed accounts, and confirmed fraud fall into this category. No amount of rerouting will recover these. Processor-side failures occur when a payment gateway or processor experiences outages or connectivity issues. Consequently, perfectly valid transactions get rejected for technical reasons unrelated to the customer.

Network routing issues happen when card networks route transactions sub-optimally. Different networks have different approval rates for different card types and geographies. Smart routing logic addresses the first and third categories most effectively. As a result, it can recover a significant percentage of failed transactions.

How Smart Routing Logic Works

Smart routing systems operate in real time. The decision happens in milliseconds — before the customer even sees a response. Here is the basic flow:

Step 1: Transaction data collection.

The system collects key data points — card BIN (Bank Identification Number), transaction amount, currency, country, device type, and merchant category.

Step 2: Rule-based evaluation.

Pre-configured rules filter the available processors. For example, certain processors handle international cards better. Others excel with high-value transactions. Therefore, the system narrows options based on these rules.

Step 3: Machine learning scoring.

Advanced systems apply ML models trained on historical approval data. They score each processor for this specific transaction type. Furthermore, they update these scores continuously as new data arrives.

Step 4: Processor selection.

The system routes to the highest-scoring processor. If that processor fails, automatic failover triggers instantly and retries through the next best option.

Step 5: Feedback loop.

The outcome — approval or decline — feeds back into the model. Consequently, the system learns and improves with every transaction.

Key Factors in Routing Decisions

No two transactions are identical. Smart routing systems evaluate dozens of variables simultaneously. Here are the most impactful ones.

Processor performance by card type: Visa approvals may be higher on one processor while Mastercard performs better on another. Routing logic matches card type to the best-performing processor.

Geographic routing: International transactions often fail because processors lack relationships with certain issuing banks. Therefore, routing to a processor with strong regional coverage improves approval rates significantly.

Transaction amount thresholds: High-value transactions carry higher fraud risk. Some processors have lower approval rates for large amounts. Routing logic directs these to processors with better high-value performance.

Processor uptime data: If a processor has experienced downtime in the last hour, the system deprioritizes it. This prevents routing to a degraded system.

Time of day patterns: Approval rates vary by time of day and day of week. Smart systems factor in temporal patterns to optimize routing timing.

Cascading Failover: Recovering Failed Transactions

Cascading failover is one of the most powerful features of smart routing. It automatically retries declined transactions through alternative processors. Here is how it works in practice. A transaction is sent to Processor A. Processor A declines it due to a technical issue. Instead of showing the customer an error, the system silently retries through Processor B. If Processor B succeeds, the customer never knows anything went wrong.

This recovery mechanism can save between 3% and 15% of transactions that would otherwise be lost. For high-volume businesses, that represents significant recovered revenue. However, cascading must be configured carefully. Not all declines should trigger a cascade. Hard declines — fraud flags, closed accounts — should not be retried. Retrying these can increase fraud risk or invite additional decline fees. Therefore, routing logic must distinguish between recoverable and non-recoverable failures before triggering a cascade.

Cost Optimization Through Routing

Smart routing does more than improve approval rates. It also optimizes processing costs. Different processors charge different interchange fees. Additionally, fees vary by card type, transaction type, and volume tier. A smart routing system can factor in cost alongside approval probability.

For example, two processors may have similar approval rates for a given transaction. However, one charges 0.1% less in interchange. Routing to the cheaper processor — without sacrificing approval likelihood — reduces processing costs over millions of transactions.

Currency routing is another cost lever. Processing payments in the cardholder’s local currency often reduces decline rates and avoids dynamic currency conversion fees. Consequently, routing systems can detect cardholder currency preferences and route accordingly.

Furthermore, some processors offer volume discounts. Routing logic can be configured to consolidate volume on preferred processors to hit discount thresholds faster.

How to Implement Smart Routing

Implementation depends on your current payment infrastructure. Here are the main approaches.

Option 1: Payment orchestration platforms.

Platforms like Spreedly, Primer, and Gr4vy sit on top of your existing processors. They provide routing logic, failover, and analytics without requiring you to rebuild your payment stack. This is the fastest path for most businesses.

Option 2: Build in-house routing logic.

Larger businesses with engineering resources sometimes build custom routing layers. This offers maximum control but requires significant investment. Furthermore, it demands ongoing maintenance as processor APIs and performance data change.

Option 3: Use a payment processor with built-in smart routing.

Some processors — like Stripe with its Smart Retries feature or Adyen with its revenue optimization tools — offer routing logic as part of their service. This is the simplest option. However, it limits routing to processors within that ecosystem.

Regardless of approach, start with clear goals. Define the metrics you want to improve — approval rate, cost per transaction, or chargebacks. Then, configure routing rules that address those specific goals.

Measuring the Impact of Smart Routing

Implementing routing logic without measurement is guesswork. These metrics tell you whether it is working.

Authorization rate: The percentage of attempted transactions that are approved. This is the primary metric. A well-tuned routing system should lift this by 2% to 10% depending on your baseline.

Decline recovery rate: Of all declined transactions, how many does your failover system recover? This measures the effectiveness of your cascading logic specifically.

Cost per transaction: Are you routing efficiently from a cost perspective? Track this alongside approval rate to ensure you are not sacrificing margins for volume.

Processor reliability score: How often does each processor fail or underperform? Use this to continuously refine your routing hierarchy.

Chargeback rate by processor: Some processors have better fraud detection tools. Routing high-risk transactions to those processors can reduce chargebacks. Track this metric to validate that hypothesis.

Review these metrics monthly. Furthermore, A/B test routing configurations to identify improvements. Treat routing logic as a product — iterate and optimize continuously.

The Future of Payment Routing

Payment routing is evolving rapidly. Several trends are shaping its future. AI-driven routing: Machine learning models are becoming more sophisticated. They now factor in hundreds of variables simultaneously and update in near real time. As a result, routing decisions are becoming more accurate than any rule-based system could achieve.

Open banking integration: With open banking APIs, routing logic can access real-time account data. This allows systems to route to the most appropriate payment rail — card, bank transfer, or digital wallet — based on what will most likely succeed.

Real-time payments: As instant payment networks like RTP and FedNow expand, routing systems will need to handle new rails alongside traditional card networks. Consequently, routing logic must become more sophisticated to manage this complexity.

Biometric authentication: Payments combined with biometric verification reduce fraud flags and improve approval rates. Routing systems will increasingly factor in authentication method when making routing decisions.

The businesses that invest in smart routing infrastructure today will be better positioned for these shifts. Furthermore, the cost of not optimizing — lost revenue, higher processing costs, worse customer experience — only grows with transaction volume.

Conclusion

Payment routing logic is not a luxury for large enterprises. It is a necessity for any business that processes payments at scale.

Every declined transaction is recoverable revenue. Every inefficient routing decision is a cost you are paying unnecessarily. Smart routing — with cascading failover, cost optimization, and machine learning — addresses all of these issues simultaneously. It improves approval rates, reduces costs, and delivers a better checkout experience.

Start with the metrics that matter most to your business. Then, choose a routing approach that fits your technical resources. Above all, treat routing as an ongoing investment — not a one-time setup.

The difference between a 92% and a 97% approval rate is enormous at scale. Smart payment routing logic is how you close that gap.

Read More:

AWS-SDK for Payments: What Businesses Must Know Full Guide

From Gateways to Payment Orchestration in Easy Steps

Why Indian fintechs Lead in API First Tech