How Should Businesses Reprice Their Products After UPI MDR Changes?...
Read More
How Should Businesses Reprice Their Products After UPI MDR Changes?...
Read More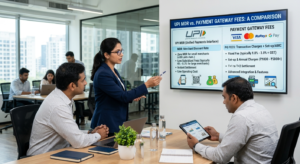
UPI MDR vs Payment Gateway Charges: What Will Actually Cost...
Read More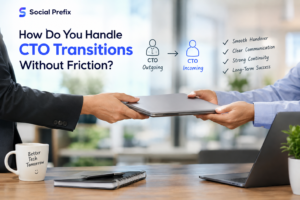
When Your Co-Founder CTO Steps Down: Maintaining Product Momentum During...
Read More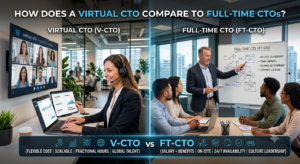
Virtual CTO for FinTech Startups: Architecting Banking API Integrations With...
Read More
Embedded Payments in SaaS Platforms: A Growing Opportunity Introduction SaaS platforms no longer just manage workflows. Many now move money directly inside their products. Embedded payments in SaaS platforms let customers pay, get paid, and manage funds without leaving the app. This shift is creating a growing opportunity for software companies of every size. Businesses that add payment features often see stronger revenue and stickier customers. However, adding payments the right way takes careful planning. This guide explains what embedded payments are, why they matter, and how to bring them into your platform successfully. We will also cover the benefits beyond revenue, the different paths companies can take, and the compliance steps that protect both the business and its customers. What Embedded Payments Actually Mean for SaaS Embedded payments allow a SaaS product to process transactions natively. Instead of sending users to a separate payment provider, the software handles it directly. This includes invoicing, card processing, payouts, and even lending features in some cases. For example, a scheduling app might let salons charge clients automatically after each appointment. Similarly, a construction management tool might let contractors pay suppliers from within the platform. In contrast, older SaaS tools simply linked out to third-party checkout pages. This difference matters because embedded payments in SaaS platforms remove friction. Users complete more actions without switching tools. As a result, they stay engaged with the software for longer periods. Beyond simple transactions, some platforms now offer embedded lending or instant payouts. These features go a step further than basic payment processing. They turn the software into a genuine financial partner for its users, not just a workflow tool. Some SaaS platforms also embed expense cards or virtual accounts for their customers. These features let businesses manage cash flow entirely within the software they already use daily. This deeper integration makes the platform far harder to replace. It is worth noting that embedded payments differ from simple payment gateways. A gateway just processes a transaction and passes the funds along. Embedded payments, in contrast, weave the entire financial workflow into the product experience itself. Payouts are another area worth understanding. Many platforms now offer instant or next-day payouts to their users, rather than the standard multi-day wait. This speed becomes a real competitive advantage for platforms serving freelancers or small businesses that rely on fast cash flow. Marketplaces provide one of the clearest examples of embedded payments in action. A marketplace platform collects payment from a buyer, holds it briefly, then splits and pays out multiple sellers automatically. This entire process happens without any manual intervention from the platform operator. Vertical SaaS companies, which serve a single industry deeply, often benefit most from this model. A platform built specifically for veterinary clinics or auto repair shops already understands its customers’ payment habits better than a generic tool ever could. Why This Market Is Growing So Quickly Several forces are driving demand for embedded payments in SaaS platforms. First, customers expect all-in-one solutions rather than juggling separate tools. Second, payment infrastructure providers now make integration far easier than before. Additionally, SaaS companies are searching for new revenue streams beyond subscription fees. Payment processing offers a natural, high-margin addition. Meanwhile, investors increasingly favor SaaS platforms with embedded finance because it improves both revenue and customer lock-in. Consequently, industries like healthcare, real estate, and field services are adopting embedded payments quickly. These sectors already rely on software daily, making payments a natural next step. Analysts also point to falling integration costs as a key driver. Payment infrastructure companies now offer ready-made tools that once required years of in-house development. This shift lowers the barrier for smaller SaaS companies to compete with larger players. Market research consistently shows embedded finance revenue growing much faster than traditional software licensing. This trend is pushing even conservative SaaS companies to explore payments sooner than they originally planned. Competitive pressure plays a role too. Once one platform in a niche adds embedded payments, competitors often feel forced to follow. Otherwise, they risk losing customers who prefer an all-in-one solution over a fragmented set of tools. Consumer behavior is shifting as well. Business owners increasingly expect the software they already trust to also handle their money securely. This expectation makes embedded payments feel less like an add-on and more like a baseline requirement. Regulatory changes have also opened the door wider. Many regions now offer clearer licensing paths for software companies that want to offer payment services. This clarity reduces legal uncertainty and encourages more SaaS companies to move forward with confidence. The rise of application programming interfaces built specifically for finance has also lowered technical barriers. Development teams can now connect to sophisticated payment infrastructure in weeks rather than the years such projects once required. Business Benefits Beyond Extra Revenue Revenue is the most obvious benefit, but it is not the only one. Embedded payments in SaaS platforms also improve customer retention. When payment data lives inside the platform, switching to a competitor becomes harder. Furthermore, embedded payments give companies richer data about customer behavior. This data can improve product decisions and personalize offers. In contrast, platforms without payment data often work with incomplete customer insights. Customer support also improves in many cases. Support teams can resolve billing issues directly, without redirecting users elsewhere. This creates a smoother overall experience and builds trust in the brand. Finally, embedded payments can strengthen a company’s valuation. Investors often view payment revenue as more predictable and scalable than subscription fees alone. This perception can support stronger funding rounds or acquisition offers down the line. Cross-selling also becomes easier once payments are embedded. A platform that already handles a customer’s money is well positioned to introduce related financial products, such as savings tools or short-term credit. Employee productivity can improve as well. Finance teams inside customer companies spend less time reconciling payments across multiple systems. This time saving becomes a strong selling point during renewal conversations. Brand perception also shifts in a positive direction. A platform that
Fintech for Logistics & Supply Chain Payments Moving goods across the world is only half the challenge. Moving money through the supply chain is often harder. Fintech for logistics is solving this problem in ways that seemed impossible just a few years ago. Payments that once took weeks now settle in days or even hours. Supply chains involve many players. Shippers, carriers, warehouses, and vendors all need to get paid on time. Delays anywhere in that chain create ripple effects everywhere else. This is where fintech for logistics steps in, connecting payment systems directly to operational data. This article explains why traditional payment methods struggle in logistics, how fintech solves those problems, and what benefits businesses can expect. Let us explore the details. Why Traditional Payments Struggle In Logistics Logistics has always run on tight margins and tighter timelines. Traditional banking systems were never built for this pace. Paper invoices still exist in many supply chains today. Someone has to manually match invoices to shipments. Errors happen often, and disputes take days to resolve. Meanwhile, carriers wait for payment while covering fuel and driver costs upfront. Cross-border transactions add another layer of complexity. Currency conversion, compliance checks, and banking hours vary by country. As a result, international shipments often face payment delays that have nothing to do with the goods themselves. This creates cash flow pressure across the entire chain. Small carriers and independent truckers feel this pain the most. Waiting thirty or sixty days for payment can strain their operations badly. Consequently, many either raise prices or refuse certain jobs altogether. This limits capacity precisely when demand is highest. Traditional systems also lack visibility. Finance teams often cannot see where a payment sits in the approval process. This lack of transparency leads to frustration on both sides of every transaction. Fintech for logistics directly addresses each of these pain points. How Fintech For Logistics Solves Payment Problems Fintech for logistics connects payment platforms directly to shipment and tracking data. Payments trigger automatically once delivery is confirmed. This automation removes much of the manual work involved in invoice matching. Systems verify delivery status instantly using GPS and digital proof of delivery. Therefore, payments release faster with fewer disputes and less paperwork. Real-time payment rails also play a major role. Instead of waiting for traditional bank transfers, funds move within hours through modern payment networks. Additionally, some platforms offer instant factoring, letting carriers get paid immediately for a small fee. This flexibility helps smaller operators manage cash flow more predictably. Cross-border payments benefit significantly from fintech innovation too. Digital platforms handle currency conversion and compliance checks automatically. This reduces the delays that once made international logistics payments so frustrating. Similarly, built-in fraud detection protects both shippers and carriers from costly errors. Data visibility improves dramatically as well. Finance teams can track every payment in real time through a single dashboard. They see exactly where funds are in the process at any given moment. This transparency builds trust between all parties involved in the transaction. Key Benefits For Businesses Across The Supply Chain Faster payments create advantages that extend well beyond simple convenience. The impact touches nearly every part of a logistics operation. Improved cash flow tops the list for most companies. Carriers can accept more jobs when they are not waiting weeks for payment. Shippers benefit from stronger, more reliable carrier relationships as a result. Everyone in the chain operates with less financial stress. Cost savings follow closely behind. Automated systems reduce the manual labor needed for invoice processing and reconciliation. Fewer errors mean fewer costly disputes and less time spent on corrections. Over time, these savings add up significantly for large operations. Stronger partnerships also emerge from reliable, fast payments. Vendors and carriers prefer working with companies that pay consistently and quickly. This reputation can become a genuine competitive advantage in a tight labor market. Businesses that pay reliably often get priority access to capacity during peak seasons. Better data also supports smarter decision-making. Finance leaders gain clear visibility into spending patterns across routes, vendors, and regions. This information helps identify cost-saving opportunities that were previously hidden in disconnected systems. Consequently, companies can negotiate better rates using real payment history as leverage. Risk management improves too. Fintech platforms often include built-in fraud detection and compliance monitoring. This protects businesses from payment fraud, which remains a persistent risk in complex global supply chains. Choosing The Right Fintech Partner For Logistics Not every fintech platform fits every logistics business. Choosing the right partner requires careful evaluation. Start by examining integration capabilities. The platform should connect easily with your existing transportation management and accounting systems. Poor integration creates new manual work instead of removing it. Therefore, this should be a top priority during evaluation. Next, consider payment speed and flexibility. Look for platforms offering multiple payout options, including instant transfers for time-sensitive situations. Additionally, check whether the platform supports the currencies and regions relevant to your operations. Security and compliance also deserve close attention. Verify that the provider follows strong data protection standards and relevant financial regulations. This matters even more for companies handling cross-border transactions regularly. Finally, evaluate customer support and onboarding quality. A platform with excellent technology but poor support can slow your transition significantly. Ask potential partners about implementation timelines and available training resources before committing. Working with experienced experts can simplify this decision considerably. Build your authority with Digital Payment Guru and modernize your logistics payment infrastructure with confidence. Conclusion Fintech for logistics is reshaping how money moves through global supply chains. Faster payments, better visibility, and stronger partnerships are no longer optional advantages. They are becoming baseline expectations across the industry. Companies that adopt these tools early gain real operational advantages. They build stronger carrier relationships and reduce costly payment friction. Meanwhile, those relying on outdated systems risk falling behind competitors who move faster and pay smarter. The shift toward digital, automated logistics payments will only accelerate. Businesses that prepare now will be ready to lead their
Payment Gateways for EdTech Platforms: Unique Challenges Payment gateways for EdTech platforms are not like typical online checkout systems. Education businesses deal with parents, students, institutions, and even government bodies. Each group brings different expectations and payment habits. This guide explores the real challenges EdTech companies face with payments. You will also learn practical ways to solve these problems. By the end, you will understand what separates a good payment gateway from a great one. Whether you run a tutoring app, an online school, or a certification platform, these lessons apply to you. Payments may feel like a small detail. In truth, they shape the whole customer experience. Why EdTech Payments Are Different Traditional eCommerce involves one buyer and one seller. EdTech, however, often involves three parties. A parent pays, a student learns, and the platform delivers the service. This triangle creates unique friction points. Also, EdTech platforms often serve global audiences. A single course might attract students from ten different countries. Each country has its own preferred payment methods, currencies, and regulations. Trust also plays a bigger role in education payments. Parents want reassurance before paying for their child’s learning. So, payment gateways for EdTech platforms must feel secure and transparent at every step. Subscription models add one more layer of complexity. Many EdTech platforms charge monthly or yearly fees. Managing renewals, failed payments, and cancellations requires a gateway built for recurring billing. Institutional buyers add yet one more dimension. Schools and corporate training departments often pay in bulk, sometimes through invoicing rather than instant checkout. A payment gateway built only for individual consumers may struggle with these larger, slower-moving transactions. Age also plays an unusual role in EdTech payments. Many learners are minors who cannot legally hold a payment method themselves. This means the actual payer is rarely the actual user, which complicates identity verification and consent tracking. Common Challenges EdTech Platforms Face The first major challenge is handling diverse payment methods. Some regions prefer credit cards, while others rely on digital wallets or bank transfers. A limited gateway can quickly turn away potential customers. Currency conversion creates one more hurdle. International students expect prices in their local currency. Without proper conversion tools, EdTech platforms risk confusing or losing customers during checkout. Compliance requirements add further pressure. Education platforms that collect payments from minors, through parents, must follow strict data protection rules. Similarly, financial regulations vary widely between countries and states. Refunds and chargebacks are also more common in education than in typical retail. Students may request refunds after a few lessons, or parents may dispute charges. A strong payment gateway must handle these cases smoothly and fairly. Meanwhile, failed subscription renewals cause quiet revenue loss. A card might expire, or a bank might decline a charge. Without smart retry logic, EdTech platforms lose subscribers without ever knowing why. This kind of silent churn is easy to miss without proper monitoring. Many founders only spot the pattern after months of falling renewal rates. By then, real revenue has already slipped away. Last, fraud prevention deserves special attention. Free trials and low-cost entry offers can attract fraudulent sign-ups. Payment gateways for EdTech platforms need built-in fraud detection to protect revenue and reputation. Seasonal demand spikes also create pressure on payment systems. Enrollment periods, exam seasons, and back-to-school campaigns can multiply transaction volume overnight. A gateway that cannot scale quickly may slow down or fail during these key windows. Tax handling across regions adds one more layer of difficulty. Digital education services face different tax treatment in different countries. Miscalculated tax at checkout can lead to compliance issues down the line. Key Features to Look For in EdTech A strong EdTech payment gateway supports multiple currencies by default. This feature alone can open access to new markets without extra development work. Support for local payment methods matters just as much. In some countries, digital wallets dominate. In others, bank transfers remain the norm. The right gateway adapts to these regional preferences on its own. Recurring billing tools are essential for subscription-based platforms. Look for automatic retry logic, renewal reminders, and simple cancellation flows. These features reduce churn and protect monthly revenue. Similarly, strong security certifications build trust with parents and institutions. Look for gateways that meet recognized data protection standards. This reassurance often influences a parent’s decision to complete a purchase. Flexible refund management also matters greatly. EdTech businesses need clear rules for partial refunds, course cancellations, and dispute resolution. A gateway with built-in refund workflows saves significant administrative time. Last, detailed reporting tools help teams track revenue accurately. Clear dashboards make it easier to spot failed payments, refund trends, and regional performance differences. Invoicing support is one more valuable feature for platforms that sell to schools or businesses. Bulk licensing deals often require formal invoices rather than instant card payments. A gateway that handles both consumer and institutional flows saves significant operational effort. API flexibility should not be overlooked either. Development teams need clean documentation and reliable uptime. A gateway that is difficult to integrate can delay product launches and frustrate engineering teams. How to Choose the Right Gateway for Your Platform Start by mapping your audience. If most students come from one country, a local gateway may work well. However, global platforms need broader currency and payment method support. Next, consider your pricing model. Subscription-heavy platforms should prioritize gateways with strong recurring billing tools. One-time course purchases, in contrast, may need simpler checkout flows instead. It also helps to test customer support responsiveness before committing. Payment issues need fast resolution, especially during high-traffic enrollment periods. A slow support team can hurt both revenue and reputation. So, many EdTech companies choose gateways that integrate easily with existing learning platforms. Smooth integration reduces development time and avoids technical headaches later. Cost structure deserves careful comparison too. Transaction fees, currency conversion charges, and monthly costs all add up. Choose a gateway that balances affordability with the features your platform truly needs. Last, ask about scalability plans before signing a contract.
Payments for Creator Economy: Monetization Infrastructure Explained The creator economy has grown into a massive market. Millions of people now earn income from content, courses, and communities. However, few people understand what happens behind the scenes when a creator gets paid. This article explains creator economy payments in plain language. You will learn how money moves from fans to creators, what infrastructure makes this possible, and why compliance matters so much. Whether you run a platform or simply want to understand your payouts, this guide will help. Let’s start with the basics of monetization infrastructure. What Is Monetization Infrastructure for Creator? Monetization infrastructure refers to the systems that move money from a paying customer to a creator. This includes payment processors, payout rails, currency conversion, and tax reporting tools. Together, these pieces form the financial backbone of any creator platform. Think about a simple example. A fan buys a course from an online educator. That payment first passes through a processor, which checks the card details and approves the charge. Next, the platform takes its fee. Finally, the remaining amount moves to the creator’s account, often after a short delay. This process looks simple from the outside. In reality, it involves several connected systems working together. Each one must handle security, currency differences, and local regulations correctly. Additionally, monetization infrastructure must support multiple payment types. Creators today accept subscriptions, one-time purchases, tips, and affiliate commissions. A platform that only supports one payment type limits its own growth. How Money Moves From Fan to Creator Understanding the payment flow helps explain why some payouts feel instant while others take days. Generally, the process includes four steps: collection, processing, holding, and disbursement. Collection happens when a fan pays through a card, wallet, or bank transfer. The platform’s payment processor captures this transaction securely. Strong encryption protects sensitive data during this step. Processing follows next. The processor verifies the transaction and checks for fraud. This step protects both the platform and the creator from chargebacks and scams. After processing, funds often sit in a holding period. Platforms do this to manage refund risk and cash flow. Meanwhile, creators sometimes see this delay as frustrating, so clear communication about payout timing matters. Finally, disbursement sends money to the creator. This can happen through direct deposit, digital wallets, or international transfer services. Speed depends heavily on the payout method and the creator’s home country. Why Global Payouts Are So Difficult Many creators live outside the countries where their platforms are based. As a result, global payouts introduce real complexity. Currency conversion, banking regulations, and tax rules all differ by region. Currency conversion alone creates friction. A platform based in the United States might need to pay a creator in Nigeria or the Philippines. Exchange rates fluctuate constantly, and hidden fees can quietly reduce a creator’s earnings. Furthermore, banking infrastructure varies widely between countries. Some regions have fast, reliable digital payment rails. Others rely on slower systems that add days to every payout. Platforms must choose partners carefully to avoid frustrating their global creator base. Tax compliance adds another layer. Different countries require different reporting forms and withholding rules. A platform that ignores this risks legal trouble and creator distrust. Consequently, most serious platforms invest heavily in compliance tools and local payment partnerships. Despite these challenges, solving global payouts well creates a real competitive advantage. Creators tend to stay loyal to platforms that pay them quickly, fairly, and predictably. Building a Trustworthy Payment Experience Trust drives everything in the creator economy. Creators need confidence that they will get paid accurately and on time. Fans need confidence that their payment details stay secure. Transparency builds this trust. Platforms should clearly explain fees, payout schedules, and any holding periods. Hidden costs damage relationships quickly, especially among creators who compare notes publicly online. Security matters just as much. Payment infrastructure should follow strong industry standards, including encryption and fraud detection. A single security breach can destroy years of built-up trust in a platform. Support also plays a role many platforms overlook. When a payout fails or gets delayed, creators want quick answers. A responsive support team, backed by clear payment records, prevents small issues from becoming public complaints. Finally, flexibility improves the overall experience. Offering multiple payout options lets creators choose what works best for their location and preferences. This flexibility often becomes a deciding factor when creators pick between competing platforms. Conclusion Creator economy payments involve far more than a simple transaction. Behind every payout sits a network of processors, compliance checks, and payout rails working together. Understanding this infrastructure helps both platform builders and creators make smarter decisions. As the creator economy keeps growing, strong monetization infrastructure will only become more important. Platforms that invest in fast, transparent, and secure payments will earn creator loyalty. Those that ignore these details risk losing top talent to competitors. If you want to build payment infrastructure that creators trust, Build your authority with Digital Payment Guru. Their team specializes in monetization systems designed for the modern creator economy. Frequently Asked Questions 1. What is monetization infrastructure in the creator economy? Monetization infrastructure is the combination of payment processors, payout systems, and compliance tools that move money from customers to creators safely and efficiently. 2. Why do creator payouts sometimes take several days? Payouts often include a holding period for fraud and refund protection. International transfers can also add time due to banking and currency conversion processes. 3. How do platforms handle international creator payments? Platforms typically partner with global payment providers that support local currencies, banking rails, and tax compliance requirements in different countries. 4. What fees are common in creator economy payments? Common fees include processing fees, platform commissions, and currency conversion costs. Transparent platforms disclose these fees clearly before payout. 5. Why is compliance important for creator payment systems? Compliance protects platforms from legal risk and ensures creators receive accurate tax documentation. It also builds long-term trust between platforms and their creator communities. Also Read: How Does
How Governments Are Using Payments Data For Economic Monitoring Governments have always needed accurate information to make good decisions. Traditionally, economic reports arrived weeks or months after events happened. This delay made it hard to respond quickly to problems. Today, payments data is changing that reality. As digital transactions grow, governments can now track economic activity almost in real time. This article explores how payments data supports economic monitoring and why it matters for policy makers, businesses, and everyday citizens. What Is Payments Data And Why It Matters Payments data includes information generated whenever money moves electronically. This covers card transactions, bank transfers, mobile payments, and digital wallets. Each transaction leaves a digital trail that reveals patterns in spending and saving. Unlike traditional economic surveys, payments data updates constantly. Consequently, it offers a faster and more accurate picture of economic activity. Governments increasingly rely on this information to guide important decisions. From Delayed Reports To Real-Time Insight Older economic indicators, such as quarterly GDP reports, take time to compile. By the time officials see the numbers, conditions may have already changed. Payments data closes this gap significantly. For example, a sudden drop in retail transactions can signal an economic slowdown within days. This allows policy makers to respond faster than ever before. Speed matters, especially during periods of economic uncertainty. How Governments Use Payments Data In Practice Several government functions now depend heavily on payments data analysis. Tracking Consumer Spending Patterns Consumer spending drives a large portion of most economies. Payments data shows exactly where and how people are spending money. This helps governments understand which sectors are thriving and which are struggling. Additionally, spending patterns can reveal regional differences. A city experiencing rapid growth may show very different trends than a rural area. This detail supports more targeted economic policies. Monitoring Inflation In Real Time Traditional inflation measurements rely on periodic price surveys. Payments data offers an alternative approach by tracking transaction values across categories. This provides a faster read on rising or falling prices. As a result, central banks can react more quickly to inflation risks. Faster reactions often lead to more stable economic outcomes for citizens. Supporting Financial Inclusion Efforts Governments also use payments data to measure financial inclusion. By analyzing who uses digital payments and who does not, policy makers can identify underserved communities. This insight guides programs designed to expand access to banking services. Furthermore, this data helps track the effectiveness of financial inclusion initiatives over time. Officials can see whether new policies actually increase digital payment adoption. Detecting Fraud And Economic Crime Large-scale payments data also helps detect suspicious activity. Unusual transaction patterns can signal fraud, money laundering, or tax evasion. Governments use advanced analytics to flag these patterns quickly. This protects public funds and strengthens trust in financial systems. Similarly, it helps ensure that economic policies are based on accurate, untampered data. The Technology Behind Payments Data Monitoring Modern payments monitoring relies on advanced technology infrastructure. Understanding these tools helps explain why this shift is happening now. Application Programming Interfaces APIs allow different financial systems to share data securely. Banks, payment processors, and government agencies use APIs to exchange transaction information efficiently. This connectivity makes real-time monitoring possible at scale. Data Analytics And Machine Learning Raw payments data alone is not very useful. Analytics tools transform this data into meaningful insights. Machine learning models can detect trends and anomalies that humans might miss. Moreover, these models improve over time as they process more data. This means accuracy tends to increase the longer a system operates. Data Privacy And Security Measures Handling sensitive financial information requires strong privacy protections. Governments must balance the benefits of data access with citizens’ right to privacy. Encryption, anonymization, and strict access controls are standard practices in this space. Benefits Of Payments Data For Economic Policy The advantages of using payments data extend well beyond faster reporting. Better Crisis Response During economic shocks, timely information becomes critical. Payments data allowed some governments to respond faster during recent global disruptions. Quick access to spending trends helped shape emergency support programs. More Targeted Policy Making General economic policies do not always fit every region equally. Payments data allows for more localized decision making. Governments can direct resources where they are needed most, rather than applying one-size-fits-all solutions. Improved Public Trust Transparent, data-driven policy decisions can improve public confidence. When citizens see that decisions are based on solid evidence, trust in government institutions tends to grow. This is especially true during uncertain economic periods. Challenges Governments Face With Payments Data Despite its benefits, this approach comes with real challenges that deserve attention. Data Quality And Standardization Not all payment systems collect data the same way. Different formats and standards can make it difficult to combine information from multiple sources. Governments must invest in standardization efforts to make data truly useful. Balancing Access With Privacy There is an ongoing debate about how much financial data governments should access. Citizens rightly worry about surveillance and misuse of personal information. Clear regulations and oversight are essential to maintain public trust. Technical Infrastructure Gaps Not every country has the infrastructure needed to collect and analyze payments data effectively. Building this capacity requires investment in technology and skilled personnel. This is a significant barrier for many developing economies. Case Examples Of Payments Data In Action Several real-world scenarios show how valuable this data can be. Examining these examples helps clarify the practical value of payments monitoring. Retail Sector Recovery Tracking After major economic disruptions, governments often need to know how quickly retail activity recovers. Payments data provides daily snapshots of sales across industries. This allows officials to adjust support programs based on actual recovery speed, rather than waiting for delayed survey results. Regional Economic Comparisons Large countries often see uneven economic recovery across regions. By comparing payments data between cities and states, governments can identify which areas need additional support. This targeted approach tends to produce better outcomes than broad national policies applied equally everywhere. Small
Regulatory Arbitrage in Payments: Opportunities & Risks Payment companies operate across many countries and many rulebooks. Some businesses use gaps between these rules to their advantage. This practice is called regulatory arbitrage in payments. It can create real opportunities for growth and speed. However, it also carries serious risks for companies that misuse it. This guide explains regulatory arbitrage in simple, clear language. You will learn where opportunities exist and where danger hides. Additionally, you will see how responsible companies approach this strategy. Whether you are a fintech founder, compliance officer, or investor, this matters to you. Payments regulation keeps shifting across regions and product types. Therefore, understanding arbitrage helps you make smarter, safer decisions. This topic sits at the center of many boardroom conversations today. Global payment volumes keep rising, and so does regulatory attention on the sector. Consequently, the stakes around this strategy have never been higher. Let us break down what this term truly means in practice. What Is Regulatory Arbitrage in Payments? Regulatory arbitrage happens when a company structures its business to benefit from different rules. Different countries treat payment services differently under their laws. For example, one country may require a full banking license. Another country may allow the same service under a lighter framework. A payment company might choose to operate from the lighter jurisdiction. This choice can lower costs and speed up market entry significantly. Similarly, some firms route transactions through regions with fewer reporting rules. This is not automatically illegal, but it sits in a gray area. Regulators worldwide are increasingly aware of these patterns. As a result, enforcement actions against aggressive arbitrage have grown steadily. Consequently, companies must weigh short-term gains against long-term regulatory risk. A smart strategy considers both speed and sustainability together. Many successful fintechs have grown by finding legitimate regulatory efficiencies. However, the line between efficiency and evasion can be thin. Understanding this line is the first step toward responsible growth. Boards and investors now ask pointed questions about this exact distinction. Consider a payment company processing cross-border remittances for small businesses. It might register in a jurisdiction with lighter capital requirements. This lowers upfront costs and speeds up its market launch considerably. At the same time, it must still meet the destination country’s rules for customers there. Ignoring those local obligations turns a smart strategy into a serious liability. This example shows why context always matters more than the label alone. Two companies can use similar structures with very different outcomes. The difference usually comes down to intent, transparency, and follow-through. Regulators tend to reward companies that communicate openly about their structure. In contrast, they tend to punish companies that appear to hide activity. This distinction shapes enforcement decisions far more than most people realize. Where Payment Companies Find Arbitrage Opportunities Several real opportunities exist within regulatory arbitrage today. Used well, these opportunities support faster and more affordable global growth. However, opportunity without careful planning can quickly become a liability. Every advantage found through arbitrage should be documented and clearly defensible. Licensing Arbitrage Companies can choose favorable jurisdictions for their payment charter. Some regions offer faster approval timelines for new payment licenses. This speed can be a genuine competitive advantage for new entrants. However, the chosen license must still match the company’s actual operations. A mismatch between license scope and real activity invites regulatory scrutiny. Legal teams should review license terms annually as the business evolves. Product Arbitrage Similar services sometimes face very different rules across jurisdictions. For instance, some regions treat stablecoins differently than traditional e-money. Smart companies structure products to fit clearer, lower-risk categories. This does not mean hiding the true nature of a product. Instead, it means designing offerings that align naturally with sound frameworks. Product teams and legal counsel should collaborate from the earliest design stage. Geographic Arbitrage A single license, passported across a region, can unlock many markets. This approach reduces the cost of expanding into each country separately. Companies serving global customers benefit from this kind of efficient structure. Still, passporting rules vary, and misunderstanding them can cause serious, costly delays. Local counsel in each target market helps avoid these avoidable setbacks. Sandbox Arbitrage Regulatory sandboxes let startups test products under relaxed, supervised conditions. These programs allow innovation without the full weight of standard rules. Many regulators use sandboxes to encourage responsible fintech experimentation. Companies that graduate from sandboxes often build stronger long-term regulatory relationships. This early trust can smooth the path toward a full, permanent license later. Companies should treat sandbox participation as a relationship investment, not just a shortcut. Key Risks of Regulatory Arbitrage in Payments Regulatory arbitrage also carries real and growing risks. Consumer protection gaps rank among the most serious of these risks. A lighter regulatory framework sometimes means weaker dispute resolution for customers. This can leave users without a clear path when transactions go wrong. Companies should never let cost savings come at the expense of user safety. The biggest risk overall is sudden regulatory change in the chosen jurisdiction. A friendly regulator today might tighten rules tomorrow without much notice. Companies built entirely around one loophole face serious business risk. Another risk involves reputational damage if arbitrage looks like evasion. Customers and partners may lose trust in a company seen as rule-avoiding. Additionally, cross-border enforcement cooperation has increased significantly in recent years. Regulators now share information across borders more than ever before. This makes hiding weak compliance practices much harder than in the past. A further risk involves banking partner relationships across the industry. Banks often refuse to work with payment firms seen as high-risk. This can suddenly cut off a company’s access to core banking services. Finally, aggressive arbitrage can trigger costly legal battles and heavy fines. These costs often outweigh any short-term savings gained earlier in the process. Leaders must weigh these risks honestly before choosing an arbitrage-heavy strategy. Insurance and legal costs also tend to rise sharply after enforcement actions begin. Talent retention suffers too, since skilled compliance staff avoid risky