How Do Founders Pass VC Code Reviews

How Do Founders Pass VC Code Reviews? Ultimate Guide

VC Due Diligence Prep: 7 Architecture and Codebase Red Flags That Freeze Series A/B Funding (And How to Fix Them)

VC due diligence can make or break a funding round. Founders often spend months perfecting their pitch deck. However, many overlook the technical review that follows. This is where deals frequently stall or collapse entirely.

Picture a founder who has just wrapped up a strong pitch meeting. The investor seems interested and asks to move forward with due diligence. Weeks later, the deal quietly stalls. Often, the real reason is not the business model or the market opportunity. Instead, it is something buried in the codebase that nobody flagged early enough.

Investors want confidence that your product can scale. They want proof that your team can move fast without breaking things. If your architecture or codebase raises concerns, VC due diligence can freeze your Series A or Series B round. This guide walks through seven common red flags. It also explains how founders can fix them before investors ever ask.

Each red flag below reflects a pattern seen repeatedly across failed and delayed funding rounds. None of them are unusual or unique to a single industry. Instead, they represent common growing pains that many startups face as they scale from a small team to a larger, more complex organization.

Why VC Due Diligence Goes Deeper Than the Pitch

Many founders assume due diligence mainly covers financials and market size. In reality, technical due diligence has become just as important. Investors increasingly bring in engineering experts to review your codebase. They examine scalability, security, and long-term maintainability. Some funds now employ dedicated technical partners solely for this purpose, reflecting how much weight engineering quality carries in modern funding decisions.

This shift makes sense. A great product idea means little if the underlying system cannot support growth. Consequently, founders who prepare early gain a real advantage. Understanding common red flags helps you address issues before they threaten your funding timeline.

Technical due diligence typically involves a mix of interviews, automated code analysis, and hands-on review by experienced engineers. Investors want to understand not just what your product does today, but whether it can support the growth projections in your pitch deck. A mismatch between your technical reality and your growth story can quickly raise doubts, even if every other part of your business looks strong.

Red Flag 1: Poor Code Documentation of VC

Investors expect to see clear documentation. Without it, technical reviewers struggle to understand how your system works. This slows down the entire due diligence process and raises immediate concerns.

The fix: Document your architecture, key workflows, and API structures. Keep documentation updated as your product evolves. Clear documentation signals a mature, well-managed engineering team. Consider assigning ownership of documentation to specific team members, so it does not fall through the cracks as your roadmap shifts.

Red Flag 2: High Technical Debt

Technical debt accumulates when teams prioritize speed over code quality. While some debt is normal, excessive debt raises red flags. It suggests future scalability problems and higher maintenance costs.

The fix: Conduct regular code reviews and refactoring sprints. Track technical debt using a simple internal system. Show investors that you actively manage and reduce debt over time. Many founders find it helpful to dedicate a fixed percentage of each sprint specifically to debt reduction, rather than treating it as an afterthought.

Red Flag 3: Lack of Automated Testing

Manual testing alone cannot keep up with a growing codebase. Investors often ask about test coverage during VC due diligence. Low or missing automated tests suggest higher risk of bugs and downtime.

The fix: Implement unit, integration, and end-to-end tests. Aim for solid coverage across critical features. Automated testing also speeds up future development, which investors appreciate. It also reduces the chance of production incidents during a high-visibility growth period, when your reputation with customers and investors matters most.

Red Flag 4: Weak Security Practices

Security gaps are a serious concern for any investor. This includes poor access controls, unencrypted data, or outdated dependencies. A single vulnerability can damage trust and delay funding significantly.

The fix: Perform regular security audits. Update dependencies consistently. Implement strong authentication and data encryption practices. Document your security protocols clearly for investor review. If your product handles sensitive customer data, consider pursuing relevant compliance certifications early, since investors in regulated industries often ask about them directly.

Red Flag 5: Single Points of Failure

If your system relies heavily on one server, one engineer, or one vendor, this creates risk. Investors want to see resilience built into your architecture. Single points of failure suggest fragile infrastructure.

The fix: Build redundancy into critical systems. Avoid over-reliance on any single team member for core knowledge. Cross-train your engineering team and document key processes thoroughly. Investors often ask what would happen if a key engineer left tomorrow, so having a clear answer builds confidence.

Red Flag 6: Scalability Concerns

Some codebases work fine at small scale but struggle under growth. Investors want evidence that your architecture can handle rapid user growth. Poor database design or inefficient code often signals future scaling problems.

The fix: Stress test your systems before scaling rapidly. Optimize database queries and consider scalable infrastructure solutions early. Show a clear plan for handling increased demand. Presenting load testing results during due diligence can turn this red flag into a genuine strength.

Red Flag 7: Messy or Inconsistent Codebase Structure

A disorganized codebase slows down new developers and increases error rates. Investors view this as a sign of weak engineering discipline. It can also indicate rushed development without proper planning.

The fix: Establish clear coding standards across your team. Use consistent naming conventions and folder structures. Regularly review code quality to maintain consistency as your team grows. Automated linting tools can help enforce these standards without adding extra manual review burden on your senior engineers.

How to Prepare for VC Due Diligence Successfully

Preparation is the key to passing technical due diligence smoothly. Start by conducting an internal audit before investors request one. Identify weak areas and address them proactively. This builds investor confidence and speeds up the funding process.

Additionally, involve your engineering leadership early in fundraising conversations. They can help answer technical questions with clarity and confidence. This reduces friction and demonstrates strong internal alignment. Investors notice when a founder and their technical lead speak with one voice, and it builds trust quickly.

Prepare your engineering team for the tone of these conversations as well. Technical due diligence can feel like an audit, which sometimes puts engineers on the defensive. Set expectations ahead of time that this is a normal part of fundraising, not a personal critique. A calm, collaborative team usually leaves a stronger impression on investors than one that seems rattled by tough questions.

Finally, consider working with outside experts who specialize in due diligence preparation. An objective review often catches issues your internal team might miss. This extra layer of preparation can make a meaningful difference during high-stakes funding rounds.

It also helps to create a simple technical summary document for investors. This should outline your architecture, security practices, testing approach, and scalability plans in plain language. Having this ready in advance saves time during the fundraising process and shows investors that your team is organized and confident. Many founders underestimate how much a well-prepared technical narrative can speed up closing a round.
How Do Founders Pass VC Code Reviews

Conclusion

VC due diligence can feel intimidating, especially for first-time founders. However, understanding common architecture and codebase red flags puts you in control. By addressing these issues early, you protect your funding timeline and build stronger investor trust.

Do not wait until investors raise concerns. Get ahead of the process now. A little preparation now can save weeks of back-and-forth later, and it signals to investors that your team takes engineering discipline seriously. Download the VC Due Diligence Checklist with Ouriken Consulting, and walk into your next funding round fully prepared.

Frequently Asked Questions

1. What is VC due diligence in simple terms?

It is the process investors use to evaluate your business, including financials, market position, and technical infrastructure, before finalizing funding.

2. Why does technical due diligence matter for startups?

Investors want confidence that your product can scale reliably. Technical due diligence helps them assess risk before committing capital.

3. How early should founders prepare for VC due diligence?

Ideally, founders should prepare months before fundraising begins. Early preparation reduces surprises and builds stronger investor confidence.

4. Can technical red flags actually stop a funding round?

Yes, significant red flags can delay or completely freeze funding, especially if investors view them as high risk.

5. Should startups hire outside help for due diligence prep?

Many founders benefit from outside expertise. An objective review often uncovers issues that internal teams may overlook.
Also Read:

How Financial Regulations in India Shape Fintech Growth?

How Do You Build a Compliance Strategy? Ultimate Guide

How Do You Build a Compliance Strategy?

How Do You Build a Compliance Strategy? Ultimate Guide

Compliance Automation: Using AI to Stay Ahead of Regulations

Regulations change constantly. New rules appear across finance, data privacy, and payments every year. Keeping up manually drains time and increases risk. This is where compliance automation becomes valuable. AI now helps businesses track, interpret, and apply regulatory changes faster than ever before.

This guide explains how AI-powered compliance automation works. It also shows practical steps for adopting it, even without a large legal or compliance team. Whether you run a fintech startup or a growing enterprise, these strategies apply directly to your business.

Why Traditional Compliance Methods Fall Short

Traditional compliance relies heavily on manual review. Teams read updates, interpret language, and adjust policies by hand. This process is slow. It is also prone to human error.

Furthermore, regulatory bodies release updates frequently and without much warning. A single missed update can lead to costly penalties. Small teams often struggle to monitor every relevant regulation across multiple regions.

As businesses expand into new markets, compliance complexity multiplies. Different countries enforce different rules. Consequently, manual tracking becomes nearly impossible at scale. This is exactly where compliance automation proves its value.

The Real Cost of Non-Compliance

Non-compliance costs more than fines. It damages trust, delays product launches, and increases legal exposure. Additionally, repeated violations can trigger stricter regulatory scrutiny going forward.

Many businesses underestimate these hidden costs. They focus only on avoiding direct penalties. However, reputational damage often outlasts any single fine. Proactive compliance protects both finances and brand reputation.

Customers and partners also notice compliance failures. A public violation can slow down partnership deals or investor conversations for months. Building a reliable compliance record, therefore, supports growth well beyond the regulatory department.

How AI Powers Compliance Automation

AI-driven compliance tools scan regulatory updates continuously. They flag changes relevant to your industry. Moreover, they can map new rules directly against your existing policies.

This process, once handled by large legal teams, now runs in the background. Machine learning models learn to recognize patterns across regulatory language. As a result, they can highlight risks faster than manual review ever could.

Real-Time Regulatory Monitoring

Real-time monitoring tools track changes from government agencies, financial regulators, and industry bodies. When something shifts, the system alerts your compliance team immediately.

This speed matters. Early awareness allows businesses to adjust policies before violations occur. In contrast, delayed awareness often leads to reactive scrambling and last-minute fixes.

Many platforms also let teams customize alert priority. High-risk regulatory changes trigger immediate notifications, while minor updates get grouped into weekly summaries. This filtering keeps teams focused on what truly matters.

Automated Policy Mapping

Beyond monitoring, AI tools can map regulations to internal policies automatically. They identify gaps between current practices and new requirements. Consequently, compliance teams spend less time searching and more time acting.

This mapping process also creates useful documentation. Auditors appreciate clear records showing how policies evolved alongside regulatory changes.

Why Manual Tracking No Longer Scales

Manual tracking worked when regulations changed slowly. That era has ended. Regulators now update rules more frequently, and enforcement has grown stricter across most industries.

A single compliance officer cannot realistically read every bulletin, guidance note, and amendment. Furthermore, cross-border businesses face multiplied complexity, since each region publishes its own updates on its own schedule. Automation closes this gap by working continuously in the background.

Building a Compliance Automation Strategy

Adopting compliance automation does not require a complete system overhaul. A phased approach works best for most businesses.

Step 1: Audit Your Current Compliance Process

Start by reviewing how compliance currently works. Identify manual bottlenecks. Note where delays or errors happen most often. This audit reveals where automation adds the most value.

Step 2: Choose the Right AI Compliance Tools

Not every tool fits every business. Look for platforms built for your specific industry, whether that is payments, healthcare, or general data privacy. Additionally, check integration options with your existing systems.

Trial periods help here. Test how well a tool handles real regulatory scenarios before committing long term. This hands-on testing prevents costly mismatches later.

Step 3: Train Staff on New Workflows

Automation works best alongside informed staff. Teams still need to understand alerts and act on them appropriately. Therefore, short training sessions should accompany any new tool rollout.

Encourage compliance staff to treat AI as a support system, not a replacement. Human judgment remains essential for complex regulatory decisions.

Step 4: Monitor and Refine Continuously

No automation system works perfectly from day one. Review alerts regularly. Adjust filters to reduce noise and improve accuracy. Over time, the system becomes more precise and more useful.

Building Better Audit Trails

Automated systems naturally create detailed logs of every action taken. This includes which regulation triggered an alert and how the team responded. Auditors value this level of detail highly.

Additionally, clear audit trails reduce the time needed for external reviews. Instead of reconstructing history manually, compliance teams simply export existing records. This efficiency saves both time and legal expense during audits.

Compliance Automation in the Payments Industry

Payment companies face some of the strictest regulatory environments. Rules around fraud prevention, data security, and cross-border transactions shift often. AI-powered compliance tools help payment businesses stay ahead of these changes.

For example, automated systems can flag suspicious transaction patterns instantly. They can also update fraud detection rules as new regulations emerge. Similarly, they help maintain accurate audit trails required by financial regulators.

This proactive approach reduces both regulatory risk and operational strain. Teams no longer chase every update manually. Instead, they focus on strategic decisions while automation handles routine monitoring.

Reducing Risk Without Increasing Headcount

Many payment businesses cannot afford large compliance teams. AI-powered automation closes this gap effectively. It allows small teams to manage complex regulatory environments confidently.

Finally, this efficiency creates room for growth. Businesses can expand into new markets without proportionally expanding their compliance staff.

Common Challenges in Compliance Automation

Adoption is not always smooth. Some businesses face resistance from staff accustomed to manual processes. Others struggle with poor data quality, which limits automation accuracy.

However, these challenges are manageable. Clear communication about benefits reduces resistance. Meanwhile, cleaning up data before automation improves results significantly. Addressing these issues early prevents frustration later.

Overcoming Integration Hurdles

Some businesses worry that new tools will not connect with existing systems. This concern is valid but often overstated. Most modern compliance platforms offer integrations with common accounting, CRM, and payment systems.

Before purchasing, confirm integration compatibility during the trial period. Ask vendors for case studies from similar businesses. This due diligence prevents costly surprises after implementation begins.

Keeping Humans in the Loop

Automation should support decision-making, not replace it entirely. Complex or unusual cases still need human judgment. Therefore, design workflows where AI flags issues and humans make final calls on ambiguous situations.

This balance protects your business from both over-reliance on automation and unnecessary manual workload. It also builds trust in the system among staff and leadership alike.

How Do You Build a Compliance Strategy?

Conclusion

Compliance automation transforms how businesses manage regulatory risk. AI-powered tools monitor changes, map policies, and reduce manual workload significantly. Small and mid-sized businesses, especially in payments and finance, benefit enormously from this shift.

Start with a clear audit. Choose tools suited to your industry. Train your team and refine your process over time. This structured approach keeps your business ahead of regulations rather than reacting to them.

Businesses that adopt compliance automation early gain a lasting advantage. They spend less time firefighting and more time growing. That shift alone justifies the investment for most organizations.

Ready to strengthen your compliance strategy even further? Build your authority with Digital Payment Guru and lead your industry with confidence.

Frequently Asked Questions

1. What is compliance automation? Compliance automation uses AI and software tools to monitor regulations, flag risks, and update policies with less manual effort.

2. How does AI help with regulatory compliance? AI scans regulatory updates continuously, maps them against internal policies, and highlights gaps that need attention.

3. Is compliance automation only for large companies? No. Many affordable tools exist for small and mid-sized businesses, especially in the payments and fintech space.

4. Can AI completely replace compliance teams? No. AI supports compliance teams by handling monitoring and documentation. Human judgment remains essential for complex decisions.

5. How quickly can a business implement compliance automation? Many businesses see initial results within a few weeks. Full integration typically takes a few months, depending on complexity.

Also Read:

How Do You Balance Data Mobility & Safety? Ultimate Guide

How Financial Regulations in India Shape Fintech Growth?

Payment Challenges

Payment Challenges: A Complete Guide for Indian Businesses

Indian businesses are growing fast. Many now sell products and services across borders. However, expanding internationally brings a new set of hurdles. Cross-border payments often top that list. From currency conversion to compliance rules, payment challenges can slow global growth.

This article explains the biggest payment challenges Indian businesses face abroad. We will also share practical tips to solve them. Whether you run a startup or an established export business, this guide will help you plan smarter.

Currency Conversion and Exchange Rate Risk

One of the first payment challenges Indian businesses face is currency conversion. Selling in dollars, euros, or pounds means dealing with constantly shifting exchange rates. A sale that looks profitable today might shrink in value tomorrow.

Exchange rate risk affects both incoming and outgoing payments. For example, an Indian exporter invoicing in US dollars may receive less rupee value if the dollar weakens. Similarly, businesses paying overseas vendors face higher costs when the rupee falls.

To manage this risk, many companies use forward contracts. These lock in an exchange rate for a future date. Others use multi-currency accounts to hold funds in different currencies. This reduces the need for frequent conversion.

Additionally, working with the right payment partner matters. Some providers charge hidden markups on currency conversion. Businesses should always compare the real exchange rate against the rate offered. Otherwise, hidden fees can quietly eat into profit margins.

Pricing strategy also plays a role in managing this risk. Some businesses price their products in the customer’s local currency. Others price everything in Indian rupees and let the customer’s bank handle conversion. Each approach has trade-offs, so businesses should test what works best for their market.

Cash flow planning matters too. A sudden currency swing can affect budgets and profit forecasts. Finance teams should review exchange rate trends regularly. This helps them adjust pricing or hedging strategies before losses grow too large.

Payment Challenges

Cross-Border Transaction Fees and Delays

International payments often come with high fees. Traditional banks may charge for wire transfers, currency conversion, and receiving funds. These charges add up quickly, especially for smaller transactions.

Delays are another common problem. A wire transfer can take three to five business days to clear. Meanwhile, the business waits to access its own money. This delay can strain cash flow, particularly for small and medium enterprises.

Furthermore, intermediary banks sometimes take a cut during international transfers. This practice, known as correspondent banking, can reduce the final amount received. Businesses are often surprised when the amount received is lower than expected.

Modern payment platforms are helping solve these problems. Digital-first providers offer faster transfers with clearer fee structures. Some settle payments within a single day. As a result, more Indian businesses are shifting away from traditional banking channels for cross-border payments.

Small businesses feel these fees the most. A flat wire transfer fee might seem small on a large deal. However, that same fee can wipe out most of the profit on a small transaction. Therefore, businesses handling many small international payments need low-cost solutions more than ever.

Batch processing is one way to cut costs. Instead of sending many small payments separately, some businesses group them into fewer, larger transfers. This reduces the total number of fees paid. It also simplifies bookkeeping and reconciliation for finance teams.

Regulatory Compliance and RBI Guidelines

India has strict rules around foreign exchange. The Reserve Bank of India, or RBI, regulates how money moves in and out of the country. Businesses must follow the Foreign Exchange Management Act, known as FEMA, when receiving international payments.

This means every export or import transaction needs proper documentation. Businesses must report payments correctly and within specific timelines. Missing these requirements can lead to penalties or delayed transactions.

Additionally, businesses expanding into new countries must understand local regulations too. Tax rules, invoicing standards, and payment reporting vary widely by country. For instance, the European Union has different VAT requirements than the United States has for sales tax.

Therefore, compliance can quickly become complex for growing businesses. Many companies hire compliance specialists or use software that automates regulatory reporting. This reduces manual errors and keeps international payments running smoothly.

Staying updated on RBI circulars is also important. Rules around foreign remittances change from time to time. A business that stays informed avoids unpleasant surprises during audits or bank reviews.

Working with an authorized dealer bank also helps. These banks specialize in handling foreign currency transactions correctly. They can guide businesses through documentation requirements like invoices, shipping bills, and foreign inward remittance certificates. Getting this paperwork right the first time saves considerable time later.

Small mistakes in documentation can cause big delays. A missing invoice number or an incorrect currency code can hold up a payment for days. Therefore, businesses should build a simple checklist for every international transaction. This small habit prevents most common compliance headaches.

Choosing the Right Payment Infrastructure

Selecting the right payment infrastructure is critical for international growth. Many Indian businesses start with basic bank transfers. However, as transaction volume grows, this approach becomes inefficient.

Payment gateways built for cross-border commerce offer better solutions. These platforms support multiple currencies, local payment methods, and faster settlement times. They also often include built-in compliance checks, which reduces regulatory risk.

Local payment preferences matter too. Customers in different countries prefer different payment methods. For example, customers in Europe often use bank transfers or digital wallets. Meanwhile, customers in the United States frequently use credit cards. A business that ignores these preferences may lose sales.

Security is another important factor. International transactions face a higher risk of fraud. Businesses should choose payment providers with strong fraud detection and encryption standards. This protects both the business and its customers.

Finally, scalability matters as the business grows. A payment system that works for ten international customers may fail for ten thousand. Choosing a flexible, scalable platform early saves time and money later. Businesses should also test their payment systems regularly to catch issues before they affect real customers.

Integration is another practical concern. A payment system should connect easily with existing accounting and inventory tools. Manual data entry between systems wastes time and increases the chance of errors. Look for providers that offer ready-made integrations or a well-documented API.

Customer support quality also deserves attention. When a payment fails at 2 a.m. local time in another country, quick support matters. Businesses should choose providers with reliable, responsive support teams. This becomes especially important during the first few months of international expansion, when issues are most likely to surface.

Conclusion

Expanding internationally offers huge opportunities for Indian businesses. However, payment challenges can slow this growth if not addressed early. Currency risk, transaction fees, compliance rules, and infrastructure choices all play a role.

By understanding these challenges, businesses can plan more effectively. Choosing the right payment partner, staying compliant with RBI guidelines, and using modern payment infrastructure can make global expansion much smoother.

As global trade continues to grow, Indian businesses that solve these payment challenges early will have a real advantage. Preparing now means fewer surprises later, and a stronger foundation for long-term international success.

Start with a simple audit of your current payment process. Identify where fees are highest and where delays happen most often. Then, address those pain points one at a time. This focused approach turns a confusing global payment setup into a reliable growth engine.

Frequently Asked Questions

1. What are the biggest payment challenges Indian businesses face internationally?

The biggest payment challenges include currency conversion risk, high transaction fees, payment delays, and complex regulatory compliance under RBI and FEMA rules.

2. How can businesses reduce currency conversion losses?

Businesses can use forward contracts, multi-currency accounts, and payment providers that offer transparent exchange rates instead of hidden markups.

3. Do Indian businesses need RBI approval for every international payment?

Not every transaction needs separate approval, but businesses must follow FEMA guidelines and report transactions correctly to stay compliant.

4. Why do international payments take longer than domestic ones?

International payments often pass through multiple banks, known as correspondent banks. Each step can add processing time and fees.

5. What should businesses look for in a cross-border payment provider?

Look for transparent pricing, fast settlement times, strong fraud protection, multi-currency support, and built-in compliance features.

Also Read:

Why Shoppers Abandon Mobile Carts, and How to Fix It

Complete Guide to Measure AI ROI for Beginners

How to Stop Payment Latency From Hurting Revenue

How to Stop Payment Latency From Hurting Revenue

Every second counts in financial transactions. Slow payments frustrate customers, delay cash flow, and drive revenue losses. Reducing payment latency is no longer just a technical concern. It is a core business strategy. Companies that process payments faster gain a clear advantage. They close more sales, keep more customers, and manage cash more effectively. This guide explains what payment latency is, why it matters, and what businesses can do about it.

What Is Payment Latency and Why Does It Matter?

Payment latency refers to the time delay between when a payment is initiated and when it is confirmed or settled. In simple terms, it is the wait time in a transaction. This delay can happen at multiple points in the payment process.

For consumers, latency means waiting for a payment to go through. For businesses, it means waiting for funds to appear in their accounts. Additionally, long wait times at checkout can cause customers to abandon their purchases entirely.

Studies show that even minor delays in payment processing affect conversion rates. A one-second delay in checkout can reduce conversions by up to 7 percent. Therefore, payment speed directly ties to revenue performance. Businesses that ignore latency risks are quietly losing money.

How to Stop Payment Latency From Hurting Revenue

How Payment Latency Affects Customer Experience

Customer experience is shaped by convenience and speed. When payments are fast and seamless, customers feel confident. When payments are slow or fail, frustration sets in quickly.

Slow checkouts are one of the top reasons for cart abandonment in e-commerce. Customers expect instant results. If a payment takes too long to process, they may assume something went wrong. As a result, they cancel the transaction or go elsewhere.

Loyalty is also affected. A customer who experiences repeated payment delays is unlikely to return. In contrast, businesses that offer fast, frictionless payment experiences see higher repeat purchase rates. Furthermore, positive payment experiences drive word-of-mouth referrals, which are among the most valuable forms of marketing.

Mobile payments have raised expectations even higher. Users expect tap-to-pay to work instantly. Any lag feels like a system failure. Consequently, reducing latency in mobile payment channels is now a priority for businesses serving digital-first customers.

The Revenue Cost of Slow Payment Processing

Payment latency has a direct and measurable impact on revenue. First, it causes transaction failures. When processing takes too long, session timeouts occur. Customers are forced to re-enter payment details, and many do not bother.

Second, delayed settlement affects cash flow. When funds take days to appear in a business account, that business cannot invest or operate as efficiently. Small businesses are especially vulnerable. Slow settlement can mean delayed payroll, missed supplier payments, or missed investment opportunities.

Third, high latency increases the cost of payment operations. When transactions fail or require manual review, staff time and resources are consumed. Moreover, failed transactions often lead to customer service calls, increasing operational costs further.

Real-time payment systems solve many of these problems. They settle transactions in seconds rather than days. Businesses gain access to funds immediately, which improves their financial agility. Similarly, customers receive instant confirmation, which builds trust and encourages repeat business.

Technology Solutions for Reducing Payment Latency

Several modern technologies help businesses reduce payment latency significantly. Understanding these options helps companies choose the right approach for their needs.

Real-Time Gross Settlement systems, or RTGS, allow large-value payments to be settled instantly. Many central banks now offer real-time payment rails that businesses can access through their banking partners. These systems eliminate the batch processing delays common in traditional banking.

Application Programming Interfaces, or APIs, also play a key role. Payment APIs connect merchants directly to payment networks, reducing intermediary steps. Fewer intermediaries mean fewer points of delay. Additionally, API-based payment systems are easier to update and optimize.

Tokenization speeds up recurring payments. It replaces sensitive card data with a unique identifier. When a returning customer pays, the system uses the stored token instead of asking for card details again. Consequently, checkout is faster and more secure.

Edge computing brings data processing closer to the end user. Instead of sending payment data to a central server far away, edge computing processes it locally. This dramatically reduces the time it takes to complete a transaction.

The Role of Fintech in Payment Speed

Fintech companies are pushing the boundaries of what is possible in payment processing. They build solutions specifically designed to eliminate friction and reduce latency. Many traditional banks have partnered with fintechs to modernize their payment infrastructure.

Buy Now Pay Later platforms, digital wallets, and instant bank transfers are all fintech innovations that prioritize speed. Furthermore, blockchain-based payment systems offer near-instant cross-border settlement without the traditional three-to-five day wait.

For merchants, choosing the right payment processor is critical. Not all processors are equal in speed or reliability. Some prioritize throughput and real-time settlement. Others are built for high transaction volumes but sacrifice speed. Therefore, businesses should evaluate processors based on their specific revenue and cash flow needs.

Payment orchestration platforms are another emerging solution. They route transactions through the best available payment gateway based on speed, cost, and success rate. This reduces latency without requiring businesses to manage multiple payment integrations themselves.

Best Practices to Reduce Payment Latency

Reducing payment latency requires both technology and process improvements. Here are the most effective strategies businesses use today.

First, upgrade payment infrastructure. Legacy systems are often the biggest source of latency. Moving to modern, cloud-based payment platforms reduces delays significantly. Additionally, cloud systems are more scalable and easier to maintain.

Second, minimize payment steps. Every extra step in the checkout process adds time and increases drop-off risk. Streamline the payment flow by reducing required fields and offering one-click payment options for returning customers.

Third, use intelligent payment routing. Route transactions through the fastest and most reliable gateway available. Payment orchestration tools do this automatically. As a result, merchants see higher approval rates and lower failure rates.

Fourth, monitor transaction performance continuously. Use analytics to track payment processing times, failure rates, and bottlenecks. When issues appear, address them immediately. Furthermore, regular performance audits help businesses stay ahead of latency problems before they affect revenue.

Fifth, offer multiple payment methods. Different payment methods have different processing speeds. Giving customers options ensures they can choose the fastest path to completion.

Conclusion

Payment speed is a revenue driver, not just a technical metric. Reducing payment latency improves customer experience, boosts conversion rates, and strengthens cash flow. The technology to achieve this is widely available and increasingly affordable. Businesses that invest in faster payment systems gain a real competitive edge. The cost of inaction is clear: slower payments mean fewer completed transactions, frustrated customers, and lost revenue. Act now to make payment speed a strategic priority.

Frequently Asked Questions

  1. What causes payment latency in businesses?
    Payment latency is caused by factors such as legacy payment systems, multiple intermediaries in the transaction chain, network delays, batch processing schedules, and insufficient payment infrastructure.
  2. How does payment latency affect e-commerce revenue?
    Slow payment processing leads to cart abandonment, transaction failures, and poor customer experience, all of which directly reduce e-commerce sales and long-term customer retention.
  3. What is real-time payment processing?
    Real-time payment processing refers to transaction systems that initiate, authorize, and settle payments within seconds, giving both businesses and customers instant confirmation of completed transfers.
  4. Which technologies best reduce payment latency?
    Real-time payment rails, payment APIs, tokenization, edge computing, and payment orchestration platforms are among the most effective technologies for reducing payment processing delays.
  5. How can small businesses reduce payment latency on a limited budget?
    Small businesses can start by choosing a modern payment processor with fast settlement times, simplifying their checkout process, and using digital wallets or mobile payment options that are built for speed.

Read More:

Conversion Rate Secrets Hidden in Payment Methods

Which Checkout Type Converts Better for Online Stores

Payment UX Audit Checklist for Better Results

Conversion Rate Secrets Hidden in Payment Methods

Conversion Rate Secrets Hidden in Payment Methods

The checkout page is where purchases happen or fall apart. Many businesses invest heavily in marketing and website design. Yet they overlook one of the most critical conversion factors: payment methods.

The way customers pay has a direct impact on whether they complete a purchase. Offering the right payment options reduces friction and builds trust. The wrong options drive customers away at the last moment.

This blog explores how payment methods influence conversion rates across different industries and what businesses can do about it.

Conversion Rate Secrets Hidden in Payment Methods

The Psychology Behind Payment Preferences

Customers are creatures of habit. They prefer to pay in ways they already trust and understand. Introducing unfamiliar checkout experiences creates hesitation.

Studies consistently show that cart abandonment rates spike when preferred payment options are unavailable. Globally, around 70 percent of online shopping carts are abandoned. Payment-related issues account for a significant portion of this.

Trust plays a huge role in payment psychology. Familiar logos like Visa, Mastercard, PayPal, and Apple Pay signal security instantly. Customers feel safer completing transactions when they recognize the payment tools.

Furthermore, perceived risk drops when customers use payment methods that offer buyer protection. PayPal and credit cards offer dispute resolution. This reassurance pushes hesitant buyers to complete their orders.

In contrast, unfamiliar or overly complex payment processes increase perceived risk. Customers may question whether the site is legitimate. As a result, they abandon the cart rather than take the chance.

Payment Methods and Conversion Rates by Industry

Different industries have very different payment preferences. Understanding these differences helps businesses align their checkout experience with customer expectations.

In ecommerce and retail, credit cards and digital wallets dominate. Platforms that offer one-click checkout through Apple Pay or Google Pay see significant conversion lifts. The speed and convenience match the impulse-driven nature of online shopping.

Buy Now Pay Later options like Klarna and Afterpay have transformed retail conversions. Customers who cannot afford full upfront costs can split payments over time. This approach dramatically increases average order value and reduces checkout abandonment.

In the travel industry, payment flexibility is essential. Large booking amounts create hesitation. Airlines and hotels that offer installment payments or travel-specific credit card options see better conversion rates.

For subscription businesses, recurring billing options and stored payment credentials are critical. Frictionless renewal processes reduce churn and keep conversion rates high over time.

Additionally, B2B transactions often require invoicing, bank transfers, or purchase order options. B2B buyers rarely use personal credit cards for large purchases. Businesses that offer ACH transfers and invoice-based billing convert more enterprise clients.

Healthcare payments present unique challenges. Patients are sensitive about costs and privacy. Providers that offer flexible payment plans and transparent billing convert patients from interest to treatment more effectively.

Mobile Payments and Checkout Conversion Rates

Mobile commerce continues to grow rapidly. More than 60 percent of ecommerce traffic now comes from mobile devices. However, mobile conversion rates still lag behind desktop in many industries.

The gap exists largely because of payment friction. Typing credit card numbers on small screens is tedious and error-prone. Customers give up when the process feels too difficult.

Mobile wallets solve this problem. Apple Pay, Google Pay, and Samsung Pay allow customers to complete purchases with a single tap. Consequently, businesses that enable these options see measurable improvement in mobile conversion rates.

Moreover, biometric authentication through fingerprint or face recognition adds both speed and security. Customers trust the process more because it feels modern and protected.

Progressive web apps and optimized checkout flows also contribute. Reducing the number of steps to complete a payment lowers drop-off rates. Each extra click or form field represents a potential exit point.

Therefore, mobile payment optimization is not optional. It is essential for any business that wants to capture the growing mobile shopping audience.

How Payment Friction Damages Conversion Rates

Payment friction is any obstacle that slows down or complicates the checkout process. It is one of the leading causes of conversion loss across all industries.

Common sources of payment friction include requiring account creation before checkout, limited payment options, slow payment processing pages, unclear security signals, and complicated form layouts.

Guest checkout options remove one of the largest barriers. Forcing customers to create an account before paying results in significant drop-off. Similarly, long forms with many required fields increase frustration.

Security indicators matter enormously. SSL certificates, padlock icons, and recognizable payment logos reassure customers. Without these signals, trust deteriorates quickly.

Processing speed also affects conversion. If a payment page takes more than three seconds to load, many customers leave. Furthermore, payment declines without clear explanations cause frustration and lost sales.

Localization is another overlooked factor. Customers in different countries prefer different payment methods. Offering only Western options in markets where local digital wallets dominate means losing those customers entirely.

Strategies to Optimize Payment Methods for Higher Conversions

Optimizing your payment strategy is one of the fastest ways to improve conversion rates without increasing ad spend.

Start by analyzing your current cart abandonment data. Identify the payment step where most customers exit. This pinpoints where friction exists.

Next, audit the payment options you currently offer. Compare them against the preferences of your target audience. Add missing options and remove rarely used ones to simplify the experience.

Consider offering a variety of payment methods including credit and debit cards, digital wallets, Buy Now Pay Later services, and bank transfers. Giving customers choice increases the likelihood they find an option they trust.

Test your mobile checkout experience thoroughly. Use real devices rather than desktop emulators. Identify where the process feels clunky or slow.

Additionally, display trust signals prominently throughout the checkout flow. Payment logos, security badges, and money-back guarantees all contribute to checkout confidence.

Finally, run A/B tests on your checkout page layout. Small changes to button placement, form design, and payment method ordering can produce meaningful conversion improvements.

Conclusion

Payment methods have a direct, measurable influence on conversion rates across every industry. The right options reduce friction, build trust, and match customer expectations.

Businesses that treat payment strategy as a core part of their customer experience gain a real competitive advantage. Those that ignore it lose customers at the final and most important step.

Review your current checkout experience today. Identify gaps in payment options. Make targeted improvements and measure the results carefully.

The investment is small. The conversion impact can be significant.

Frequently Asked Questions

1. Why do payment methods affect conversion rates?

Customers abandon purchases when their preferred payment option is unavailable or when the checkout process feels complicated or untrustworthy. Offering familiar, easy-to-use payment options reduces friction and increases completed transactions.

2. Which payment methods have the highest conversion impact in ecommerce?

Digital wallets like Apple Pay and Google Pay consistently show high conversion rates due to their speed and simplicity. Buy Now Pay Later options also boost conversions, especially for higher-priced items.

3. How does mobile checkout affect payment conversions?

Mobile devices make typing card details difficult. Businesses that enable one-tap mobile wallet payments see significantly better conversion rates on mobile compared to those relying on manual card entry forms.

4. What is payment friction and how do I reduce it?

Payment friction includes anything that slows or complicates checkout: forced account creation, limited payment options, slow pages, and unclear security signals. Reducing these barriers directly improves conversion rates.

5. Should I offer different payment methods for different countries?

Yes. Payment preferences vary widely by region. Offering locally preferred options like UPI in India, iDEAL in the Netherlands, or Alipay in China is essential for converting international customers effectively.

Read More:

Which Checkout Type Converts Better for Online Stores

Payment UX Audit Checklist for Better Results

Why Psychology of Payments Changes Conversions: Full Guide

UPI Complete Guide

UPI Complete Guide: Choosing the Right Payment App

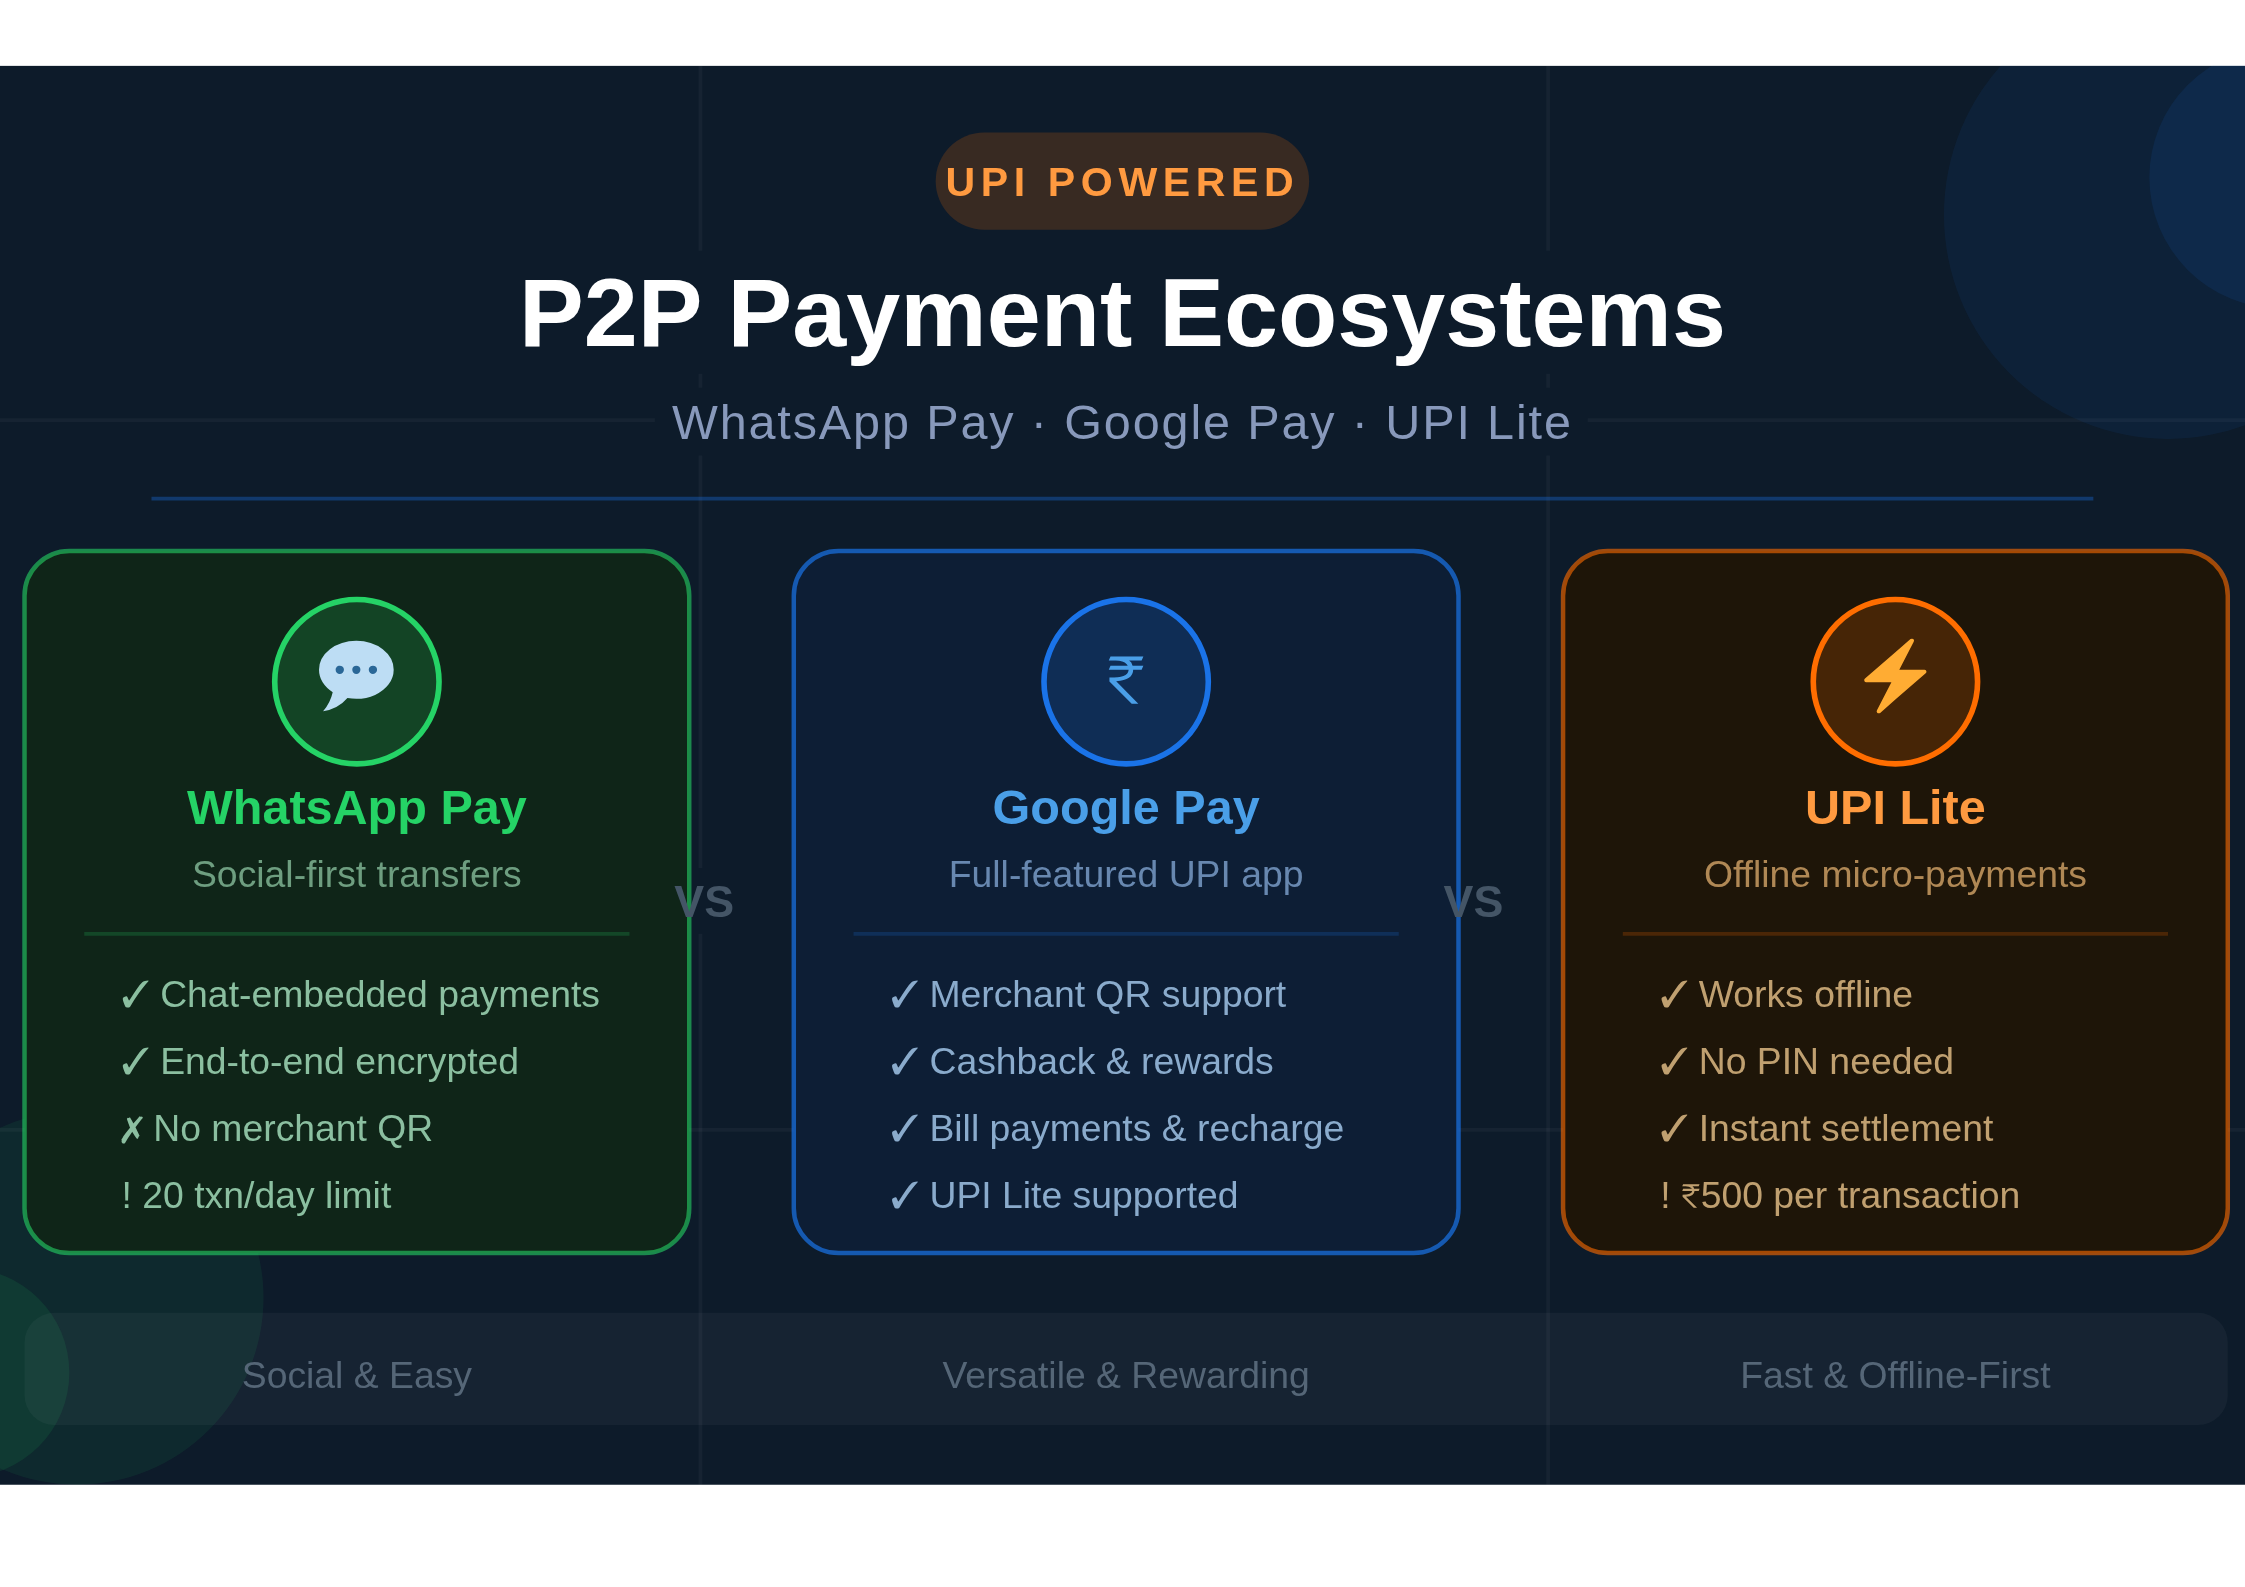
Digital payments in India have gone from a novelty to a necessity. Today, millions of people send money to friends, pay shopkeepers, and split bills — all within seconds, right from their phones. Three platforms stand at the center of this shift: WhatsApp Pay, Google Pay, and UPI Lite. Each one brings something different to the table. So, which one actually deserves a spot on your home screen?

In this blog, we break down these three P2P payment ecosystems side by side. Whether you care about speed, security, offline access, or just ease of use — this guide covers it all.

UPI Complete Guide

What Is a P2P Payment Ecosystem?

Peer-to-peer (P2P) payments allow users to transfer money directly from one bank account to another — no middleman, no waiting, no paperwork. In India, the Unified Payments Interface (UPI) powers most of these transactions. It is built and regulated by the National Payments Corporation of India (NPCI).

Therefore, apps like WhatsApp Pay and Google Pay do not move money on their own. Instead, they ride on top of the UPI infrastructure. UPI Lite, however, is a distinct layer that handles smaller, low-value transactions differently. Understanding this difference is key to choosing the right tool.

Google Pay: The Power Player

Google Pay (formerly Tez) launched in India in 2017. It quickly became one of the most downloaded UPI apps in the country. Even today, it holds a massive market share — and for good reason.

Key Features

Google Pay supports multiple UPI IDs and bank accounts. Users can link up to four bank accounts at once. Consequently, switching between accounts during a payment is easy. The app also supports bill payments, mobile recharges, and merchant QR code scanning.

Moreover, Google Pay uses a layered security model. Every transaction requires a UPI PIN. The app also features a “Safe” area that hides your payment history and account details behind an extra lock. This gives cautious users an added sense of control.

Additionally, the Nearby feature lets users discover and pay nearby businesses quickly. The rewards program — with scratch cards and cashback offers — has long been a crowd-pleaser. Furthermore, Google Pay integrates neatly with other Google services like Gmail and Google Assistant.

Limitations

On the downside, Google Pay requires internet access for every transaction. It also does not support in-app chat or social features. For users who want a more all-in-one experience, this can feel limiting.

WhatsApp Pay: The Social Payment Shortcut

WhatsApp Pay entered the Indian market after a long regulatory battle. Launched fully in 2020, it is now available to over 500 million WhatsApp users in India. The core idea is simple — pay someone directly inside a chat window.

Key Features

WhatsApp Pay is deeply embedded in the messaging experience. To send money, you simply open a chat, tap the attachment icon, and select Payment. As a result, paying someone feels as natural as sending a sticker or a voice note.

The platform supports all major Indian banks and uses UPI for fund transfers. Notably, it also stores transaction history within the chat thread — so you always know who paid whom and when. This makes it especially useful for splitting expenses among friends or family.

From a security standpoint, WhatsApp Pay is compliant with NPCI’s data localization norms. It uses end-to-end encryption for messages and a separate UPI PIN for payments. Nevertheless, some privacy advocates remain cautious about Meta’s data practices.

Limitations

WhatsApp Pay currently caps total UPI transactions at 20 per day, which is lower than Google Pay. It also lacks support for merchant QR codes at the moment. Similarly, advanced features like scheduled payments or bill splitting tools are absent. Still, for casual money transfers within a social circle, it is hard to beat.

UPI Lite: The Offline Game-Changer

UPI Lite is not exactly an app — it is a feature within UPI-enabled apps. Launched by NPCI in 2022, it addresses one of the biggest pain points of digital payments in India: poor network connectivity.

How It Works

UPI Lite works by pre-loading a small amount of money — up to ₹2,000 — into an on-device wallet. From there, you can make payments of up to ₹500 per transaction without needing internet access or a UPI PIN. Each transaction settles instantly on the device, and bank reconciliation happens later in the background.

Consequently, UPI Lite is perfect for small, everyday purchases — a chai at a roadside stall, a newspaper, an auto-rickshaw fare. Because it skips the usual server verification step, transactions process much faster than standard UPI payments.

Availability

Currently, UPI Lite is supported within Google Pay, Paytm, and several bank apps. WhatsApp Pay does not yet offer UPI Lite support, which is a notable gap. However, NPCI plans to expand compatibility across more platforms in the near future.

Limitations

The wallet cap of ₹2,000 limits its use for higher-value transactions. Additionally, users must manually top up the wallet, which can be a minor inconvenience. That said, for micro-transactions in low-connectivity areas, UPI Lite is a genuine breakthrough.

Head-to-Head Comparison

Here is a quick snapshot of how the three platforms stack up against each other:

Feature Google Pay WhatsApp Pay UPI Lite
UPI Support ✅ Full ✅ Full ✅ Lite Only
Offline Payments ❌ No ❌ No ✅ Yes
Social Integration ❌ Limited ✅ Strong ❌ None
Merchant QR ✅ Yes ❌ No ✅ Yes
Transaction Limit ₹1 Lakh/day ₹1 Lakh/day ₹500/txn
Daily Txn Count Unlimited 20 per day Unlimited
PIN Required ✅ Yes ✅ Yes ❌ No
Cashback/Rewards ✅ Yes ❌ Limited ❌ No

Security: How Safe Is Your Money?

Security is a top concern for any digital payment user — and rightfully so. Fortunately, all three platforms operate under RBI and NPCI guidelines, which means they follow strict data handling and fraud prevention standards.

Google Pay uses device-level security, including fingerprint and face recognition. WhatsApp Pay benefits from end-to-end encryption at the messaging layer. UPI Lite, meanwhile, removes the PIN requirement for small transactions — which speeds things up but also shifts responsibility to the user. Therefore, always keep your phone locked when not in use.

Regardless of which app you use, never share your UPI PIN with anyone. Be cautious of collect requests from unknown contacts. And always verify the recipient’s name before hitting confirm.

Which One Should You Use?

The best P2P payment app depends entirely on your lifestyle and needs. Here is a simple breakdown:

Choose Google Pay  if you want a full-featured UPI app with cashback rewards, bill payments, and merchant support. It is the most versatile option overall.

Choose WhatsApp Pay  if you frequently transfer money to friends and family who are already on WhatsApp. The conversational payment flow is smooth and social.

Use UPI Lite  if you make lots of small, everyday payments and live in an area with spotty internet. It is the fastest and most friction-free option for micro-transactions.

In practice, many users rely on more than one. For example, you might use UPI Lite for buying street food, Google Pay for utility bills, and WhatsApp Pay to split dinner with friends. There is no rule that says you must pick just one.

The Future of P2P Payments in India

India’s digital payment sector is growing at a breakneck pace. UPI processed over 13 billion transactions in a single month in 2024. As a result, competition among payment apps is intensifying. Going forward, expect to see smarter AI-driven fraud detection, expanded UPI Lite limits, and deeper integration with e-commerce platforms.

WhatsApp Pay is likely to roll out merchant payment features as Meta expands its Commerce ecosystem in India. Similarly, Google Pay is investing heavily in credit products and BNPL (Buy Now Pay Later) integrations. Meanwhile, NPCI is working on UPI One World — a version designed for foreign visitors to India.

Ultimately, the winner of this race will not be determined by features alone. Trust, simplicity, and network reach will decide which app becomes the default choice for the next billion users.

Final Thoughts

P2P payments are no longer just a convenience — they are the backbone of everyday financial life in India. WhatsApp Pay brings payments into conversations. Google Pay brings rewards and versatility. UPI Lite brings speed and offline access to places that were previously left out. Each platform has carved out its own niche. Together, they are reshaping how a billion people think about money. So go ahead — try all three, see what fits, and take full advantage of India’s world-class digital payments infrastructure.

Read More:

Everything You Need to Know About Payment Gateway Before Launching Your Subscription Box

Regulatory Sandboxes for Fintechs: Opportunities & Risks in India

How Offline payments Secure the Local Economy?

National Payment Sovereignty

How Does National Payment Sovereignty Protect Your Money: Full Guide

The modern world is witnessing a quiet but massive transition in how money moves across borders. For decades, global trade relied on a single, centralized network. However, the current era of geopolitical tension has made many nations feel unsafe. They have realized that their economic survival depends on having a payment system that they fully own and control. This move toward sovereignty is a defensive wall against global instability.

National Payment Sovereignty

The Problem: The Hidden Risks of Financial Dependence

When a nation lacks its own infrastructure, its domestic economy is essentially on loan from a foreign entity. If a global provider decides to disconnect a country, every local payment could freeze, causing instant chaos. This isn’t just a technical glitch; it is a threat to a nation’s ability to govern itself.

Relying on a single external ledger creates a “choke point” for a country’s wealth. Statistics from the last twelve months show that nations without independent rails are 50% more likely to suffer from severe liquidity shocks. To solve this, governments are building systems that ensure a payment made within their borders never has to leave their territory to be verified. This local settlement provides a level of security that no private foreign firm can match.

The Solution: Building the New Digital Infrastructure

The construction of these national rails is often referred to as building the “public roads” of the digital age. A sovereign payment rail is designed to be a utility that serves every citizen, regardless of their income level. Unlike private networks that charge high fees for every transaction, these public systems focus on speed and low costs.

Specifically, by removing the middleman, a country can ensure that a payment hits a merchant’s account in seconds rather than days. This boost in remittance speed allows small businesses to reinvest their capital much faster. Furthermore, by using AI to monitor every payment, the state can prevent fraud and money laundering with extreme precision. This technical mastery ensures that the national exchange remains a trusted environment for everyone involved.

The Future: A World of Interlinked Sovereignty

Building a local rail does not mean cutting ties with the world. Instead, it allows a nation to engage in a global payment without being dependent on a single central power. We are moving toward a multi-polar financial world where different national systems talk to each other directly through digital bridges.

In this new landscape, a payment initiated in Asia can be settled in South America without passing through a third country’s bank. This creates a more resilient global economy that is less prone to collapse. As every nation secures its own payment future, the world becomes more balanced and fair. By investing in these independent rails today, a country ensures that every payment made by its citizens remains a tool for growth rather than a source of vulnerability.

FAQs

Q1: Why is a domestic payment system better than a global one?

Ans. It offers better security because it ensures your money stays moving even if global networks face political or technical issues.

Q2: How does this help the average shopper?

Ans. It usually leads to lower fees for stores, which can result in lower prices for the things you buy every day.

Q3: Is my data safer on a national payment rail?

Ans. Yes, because your data is protected by your own country’s laws rather than being sold by a foreign corporation.

Q4: Will I still be able to send money abroad?

Ans. Absolutely. Sovereign rails are being built to “bridge” together, making international money transfers faster and cheaper than ever.

Q5: When will these new systems be ready?

Ans. Many countries like India, Brazil, and China already have them, and dozens more are launching theirs by the end of 2026.

READ MORE

How Does UPI vs QRIS Double Your Local Sales Today?

10 Ways QRIS Will Change How You Pay in Asia

Financial Fragmentation in a Multipolar World: Payment Guide

UPI vs QRIS

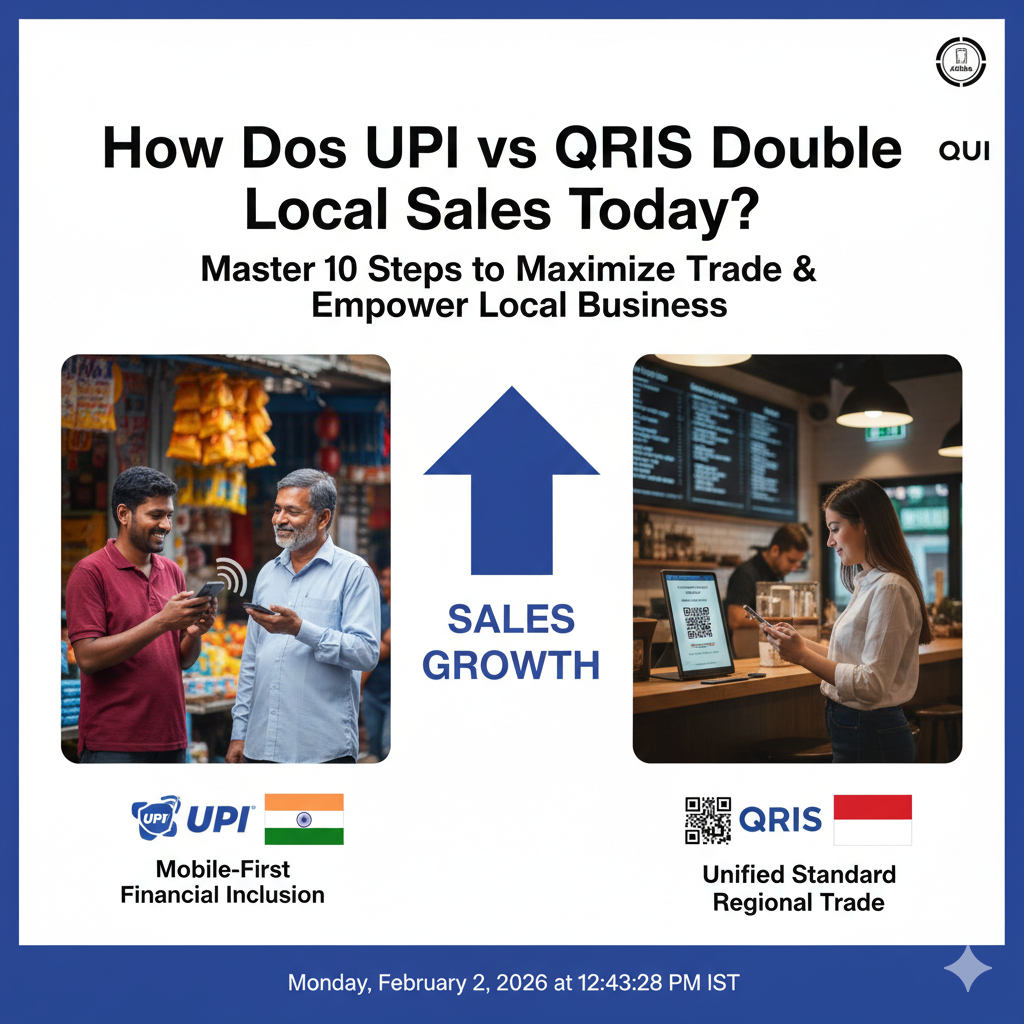
How Does UPI vs QRIS Double Your Local Sales Today?

The Problem with Global Payment Monopolies

I’ve heard it a thousand times. A nation relies only on one foreign credit card firm. And yet, their local shops pay high fees. Usually, that is just a polite way of saying the country has lost its own power. Also, old bank moves take a long time. They involve too many middle men. If you build a new market on old tracks, you are building a ghost town.

In fact, a system where local tracks handle 80% of deals is worth much more. Furthermore, the biggest cost in 2026 is the lack of links between close nations. This happens when people must carry cash or pay high fees. This path creates a big gap. Because of this, users want a fast and easy way to pay.

The solution lies in a smart way to keep your money power. This turns a national rule into a solid sales tool. This isn’t just a tech shift. Instead, it is a big plan. This helps every person pay in a safe way. Once you use these rules, you will see your local market grow.

UPI vs QRIS

1. UPI: The Best Way to Join the Bank

If you aren’t looking at the UPI growth data, you are flying blind. Specifically, India’s UPI has won more of the market for three months in a row. You need to know why this tool works so well. For example, was it the low cost or the ease of use? Smart leaders use the UPI path to see how to reach far away areas. Then, they make mobile plans for their own folks.

Moreover, smart plans allow for a steady gain in the market. This is because they focus on a good user path. By using a top-tier plan, you help your local banks win. This leads to steady gains. It sounds simple. However, most lands are too busy guessing to look at the UPI success.

2. QRIS: Linking Asian Shops Through Scans

The move to regional QR tools is happening faster than we thought. While old tools are slow, QRIS adds cross-border links through one rule. These rules use logic to link many bank nets. These rules act like a smart helper for regional trade.

However, one-country tools are not enough for a big change. The most top-tier stage is a system for many lands. These nets handle tasks like live money swaps. These tools help many banks work as one. Consequently, they act as a smart brain for the whole Asian area.

3. Digital Euro: Keeping Europe’s Money Power

To build smart bank tools, you should not have to glue poor parts together. The Digital Euro aims to use one public coin. Specifically, this uses Europe’s strength to give safe answers to market moves. This means a person can travel with their full data ready to go.

Additionally, think of a case where your phone wallet knows your local spot. It uses safe data to help you buy things fast. This base ensures that your responses to global stress stay strong. Therefore, it stops the friction that slows down your best shops. It helps them finish big deals with fewer errors.

4. The 80/20 Rule for National Payments

If your land spends all its time on foreign nets, you have no time for local growth. You must follow an 80/20 rule. Thus, use local tracks to handle 80% of daily buys. This includes food or bus rides. This leaves the 20% of big global moves to top-tier firms.

Using fast moves helps shops stay on track without cash. AI can even set up fast replies based on simple talk. This allows your shops to work in a flow. They do not have to switch between many tools. This leads to much faster growth.

5. How to Track Your Money Success

If your bank talks about total sales but not local ownership, you need a new plan. Those are vanity marks that hide a weak spot. You can have many deals but no real power in the bank. To know if you are winning, you must track the “Dirty Four”:

  • Local Ratio: First, how many of your deals stay on your own tracks?
  • Shop Cost: Next, what is the total fee for every single scan?
  • Fast Speed: Then, for every coin paid, how fast does it reach the bank?
  • User Trust: Finally, when phone use grows, does your poor group get help?

Conclusion

How to win the money power race? It shifts from a secret to a system when you pick your goals well. You must set clear goals for the bank. Also, track gains with care using local data. Repeat this for 90 days. Then, growth becomes steady. This helps you spend your budget with trust.


Key Takeaways

  • First, payment sovereignty helps a nation control its own money because it removes the need for foreign tools.
  • Therefore, systems like UPI and QRIS serve as a bridge for trade and peace.
  • Specifically, the Digital Euro wants to give a public way to pay across all of Europe.
  • Furthermore, the QRIS model is growing fast to link Asian markets through easy scans.
  • Consequently, these tools allow small shops to take international money while they boost local sales.
  • In fact, India’s UPI has seen huge growth by making mobile phones the main way to join the bank.
  • For instance, having one set of rules helps lower the cost of every deal for the user.
  • Thus, using fast settlement stops the need for slow and very pricey old bank wires.
  • In addition, using live exchange rates builds quick trust when you travel to other lands.
  • Finally, keeping data local keeps your money safe and follows all your own laws.

FAQs

Q1: Can small lands afford their own pay tools?

Ans. Yes, tools like QRIS offer low-cost rules that work well for everyone.

Q2: How long before a new tool sees real growth?

Ans. Most systems see real gains and more users within 60 to 90 days of the start.

Q3: Is it better to focus on home use or foreign links?

Ans. Good local tracks work much better than relying on others in every test.

Q4: Will a Digital Euro take away my cash?

Ans. No, but it will act like a safe digital helper for all your phone buys.

Q5: What is the biggest risk for a big pay net?

Ans. Errors or bad data silos can be very bad, so make sure your tool has good backups.

Read More:

10 Ways QRIS Will Change How You Pay in Asia

Financial Fragmentation in a Multipolar World: Payment Guide

 HSBC’s Warning: The End of Globalization & Payments

FIEO BriskPe partnership

How to use FIEO BriskPe partnership for global sales

You must stay ahead of the game if you want to sell your goods to the world today. Therefore, you should learn about the FIEO BriskPe partnership and how it helps exporters. Truly, many Indian firms lose a lot of money to slow banks and hidden fees. Consequently, you can grow your global sales by using this new digital payment bridge in 2026.

Many people think that international payments must always be slow and very complex. But, the reality is that FIEO and BriskPe are making the process very fast and simple. Always remember, a smooth payment path is a strong signal for any search engine. This ensures that your brand stays modern and your global buyers stay very happy. This approach requires you to understand the power of this new strategic alliance. It helps you build a much more competitive business for the long term. It makes your daily international trade feel much more secure and very effective.

FIEO BriskPe partnership

Why This Partnership is a Win for MSMEs

First, you must understand who is behind this big shift in Indian trade. Why did the Federation of Indian Export Organisations (FIEO) pick BriskPe as a partner? Clearly, MSMEs need a way to receive money without the heavy burden of high costs. Therefore, this partnership aims to empower small and rural exporters in 2026.

The Core Benefits for Indian Exporters

Here are several reasons why this collaboration is a game-changer for you:

  • Lower Transaction Fees: You pay much less than traditional bank wire charges.
  • Faster Settlements: Money often reaches your local bank account within 24 hours.
  • Transparent Pricing: You see the exact exchange rate with no hidden deductions today.
  • Automated Compliance: The platform handles your e-FIRA and e-BRC documents fast.
  • Global Reach: You can collect payments in many currencies from all over the world.
  • Specialized Support: Get expert help with your unique export payment challenges.
  • Search Engine Value: Fast and reliable trade helps your site earn more trust.

Truly, this partnership is about giving small firms the same tools as big banks. But, you must also see how it simplifies your daily paperwork and compliance. This keeps your business running smoothly and prevents any sudden legal delays. It creates a very professional and high standard for your global trade operations.


How BriskPe Simplifies Your Cross-Border Cash Flow

So, how does this new digital system actually handle your global sales money? Truly, it uses a unified platform to link your bank to international buyers. Consequently, you should imagine a fast digital lane that bypasses old banking hurdles. It acts as a direct link for your B2B, B2C, and C2B payments in 2026.

The Tools That Empower Your Business

Here is how the BriskPe platform works to help you manage your money:

  1. Unified Dashboard: See all your global collections in one single, easy view.
  2. Local Virtual Accounts: Get dedicated accounts in countries like the US or UK.
  3. Instant KYC: Sign up and get your account approved in a very short time.
  4. Real-Time Tracking: Watch your money move from the buyer to your bank today.
  5. Secure Gateways: Use top-tier encryption to protect every single dollar you earn.
  6. Easy Invoicing: Send professional bills to your clients in their own currency.
  7. Trust Rankings: Using compliant tools helps you keep a high search engine rank.

Furthermore, this improves your search engine performance by showing your site is up to date. It makes your company look very tech-savvy and ready for 2026 growth. This ensures that your valuable time goes to making goods instead of chasing bank clerks. It creates a very fast and clear path for your professional global success.


Accessing Export Benefits with FIEO and BriskPe

The third phase involves using the partnership to unlock even more growth perks. Clearly, being a part of FIEO gives you access to many government schemes and events. Therefore, you should use the BriskPe link to strengthen your overall export strategy.

Perks for FIEO Members Using BriskPe

Firstly, enjoy special rates and “Preferential Entry” to global trade fairs and meets. This allows you to meet new buyers without spending a fortune on travel in 2026. Secondly, use the automated e-BRC tools to claim your government export incentives fast.

Furthermore, join training sessions to learn about the latest digital payment trends. Also, use transition words in your buyer emails to explain your new fast payment link. Lastly, remember that a strong FIEO profile helps your search engine authority and trust. Truly, this alliance is the best way to scale your business across borders. It allows you to stay compliant while you reach for a bigger slice of the global market. This is why many Indian merchants are joining this digital wave right now.


Setting Up Your Global Payment Success

The fourth phase is where you take the first step to join this new trade era. Clearly, you must prepare your business records before you start your digital journey. Therefore, you must follow a few simple steps to get your BriskPe account ready today.

Steps to Start Your Fast Export Payments

Firstly, visit the FIEO or BriskPe website to learn about the registration process. This helps you gather all your documents like your PAN and IEC code in 2026. Secondly, link your existing Indian bank account to the BriskPe dashboard for easy transfers.

Furthermore, share your new virtual account details with your international clients right away. Also, use your data to track your savings on every single global transaction. Lastly, check your search engine ranking to see if trade volume helps your web traffic. Truly, a smart setup is a journey that leads to a much stronger brand. It turns a complex task into a series of smart, secure wins for your whole team. This ensures your business stays strong while others face high fees and slow cash flows.


Leading the Future of Indian Exports

Finalizing your plan requires you to stay updated on new trade policies and tech. It needs you to review your payment costs and update your site every single year. Clearly, winning in global trade is a team effort for your brand in 2026. Therefore, follow these simple tips to keep your export business fresh and very fast.

Simple Tips for Lifelong Export Success

Firstly, attend the FIEO knowledge sessions to learn about new digital trade tools. This helps you stay one step ahead of any global market shifts or new rules today. Secondly, encourage your buyers to use the direct payment link for better speed and safety.

Furthermore, use transition words in your export guides to keep them very clear and helpful. Also, remind your team that fast payments help the company earn more search engine trust. Lastly, check your search engine data to see if your global reach helps your web traffic grow. Truly, a fast path is a journey that leads to a much better brand in 2026. It builds a path of innovation that lets your whole team grow very fast. This secures your future in the digital world for a long time.


Frequently Asked Questions (FAQs)

Q1: What is the main goal of the FIEO–BriskPe partnership?

It aims to raise awareness about digital tools that make cross-border payments faster and cheaper for Indian exporters.

Q2: How does BriskPe help with export documentation?

The platform automates the issuance of critical documents like e-FIRA and e-BRC to save you time.

Q3: Is BriskPe safe for my international transactions?

Yes, it is an RBI-authorized platform that uses high-level security to protect your money.

Q4: Do I need to be a FIEO member to use BriskPe?

While anyone can use BriskPe, FIEO members often get extra perks and easier access to trade events.

Q5: Can I receive payments in USD through this system?

Yes, you can collect money in many currencies like USD, GBP, and EUR with very low fees.

Also Read: Best ways PayPal + UPI integration saves you money

PayPal + UPI

Best ways PayPal + UPI integration saves you money

You must watch how the world of digital money is merging today. Therefore, you should learn about PayPal and UPI integration and its global impact. Truly, sending money across borders used to be a very slow process. Consequently, you can enjoy a future where international cash moves as fast as a text.

Many people think that global banks will always charge very high fees. But, the reality is that new tech links are making payments much cheaper. Always remember, a fast payment path is a strong signal for any search engine. This ensures that your brand stays modern and your global customers stay very happy. This approach requires you to understand how these two giants work together. It helps you build a much more agile sales plan for the long term. It makes your daily international business feel much more secure and very effective.

PayPal + UPI

Why This Integration is a Massive Deal

First, you must understand the scale of these two payment systems in 2026. Why is a link between PayPal and UPI such a big win for everyone? Clearly, PayPal dominates global trade while UPI is the king of instant cash in India. Therefore, linking them creates a bridge for billions of people to trade.

The Benefits of Linking PayPal with UPI

Here are several reasons why this link is a game-changer for you:

  • Speed: You get your international money in seconds instead of many days.
  • Simplicity: You can use your mobile phone to pay global sellers instantly.
  • Lower Cost: The integration removes many middle-man fees for every transfer.
  • Security: You get the protection of PayPal with the ease of a UPI scan.
  • Reach: Indian freelancers can now sell to the whole world much easier.
  • Transparency: You see the exact exchange rate before you click send today.
  • Search Engine Value: Faster checkouts improve your site’s organic trust score.

Truly, this link is about making the world feel like one single market. But, you must also see how this helps small creators grow their reach. This keeps your business competitive and prevents any loss of global sales. It creates a very professional and high standard for your digital store.


How the New Payment Bridge Works

So, how does the money actually travel from a US bank to an Indian app? Truly, the system uses smart digital codes to swap currencies in real-time. Consequently, you should imagine a fast lane for cash that never hits a red light. It acts as a direct link for seamless trade between different nations in 2026.

The Technology of Instant Global Cash

Here is how PayPal and UPI talk to each other right now:

  1. Unified Interface: PayPal adds a UPI option directly inside its mobile app.
  2. Real-Time Forex: The system picks the best exchange rate in a split second.
  3. Virtual IDs: You use your simple UPI handle to receive global payments.
  4. Instant Alerts: Both the sender and receiver get a message the moment it clears.
  5. Encrypted Paths: Top-tier security protects your bank data during the swap.
  6. Auto-Settlement: The money lands in your local bank account without extra steps.
  7. Trust Rankings: Using modern payment links helps you keep a high search rank.

Furthermore, this improves your search engine performance by showing your site is up to date. It makes your company look very tech-savvy and ready for 2026 growth. This ensures that your valuable time is not spent chasing missing wire transfers. It creates a very fast and clear path for your professional global success.


Impact on Freelancers and E-commerce

The third phase involves looking at who gains the most from this new tech. Clearly, small business owners and digital workers will see a huge benefit today. Therefore, you should update your payment settings to include these new options.

Growing Your Brand with Better Payments

Firstly, a freelancer in India can now accept a payment from London instantly. This allows you to take on more work without worrying about high bank fees. Secondly, e-commerce stores can offer “Scan and Pay” to their international buyers in 2026.

Furthermore, you can pay for global software or tools using your local UPI balance. Also, use transition words in your invoices to keep them very clear for clients. Lastly, remember that a smooth payment flow helps your search engine authority and trust. Truly, this integration is the best tool for anyone working across borders. It allows you to focus on your craft while the money flows automatically. This is why top digital nomads are so excited about this new era.


Setting Up Your Global Payment Shield

The fourth phase is where you ensure your new payment links are safe. Clearly, you must protect your hard-earned money from digital thieves in 2026. Therefore, you must use strong security habits with your PayPal and UPI accounts.

Staying Safe in the World of Instant Money

Firstly, turn on two-step verification for both your PayPal and your banking app. This helps you stop any unauthorized access to your funds right away. Secondly, never share your UPI PIN or your PayPal password with anyone.

Furthermore, only send money to people or brands that you truly trust online. Also, use your data to track every transaction and report any errors fast. Lastly, check your search engine ranking to see if site safety helps your traffic. Truly, a safe payment path is a journey that leads to a much stronger brand. It turns a complex task into a series of smart, secure wins for your team. This ensures your business stays strong while others face digital risks.


Leading the Global Payment Wave

Finalizing your plan requires you to stay ahead of new fintech trends. It needs you to review your payment options and update your site every year. Clearly, being a leader in payments is a team effort in 2026. Therefore, follow these simple tips to keep your brand fresh and very fast.

Simple Tips for International Payment Success

Firstly, display the PayPal and UPI logos clearly on your checkout page. This helps your customers feel safe and ready to buy from you today. Secondly, offer a small discount for users who try the new instant payment path.

Furthermore, use transition words in your customer emails to explain the new speed. Also, remind your team that fast payments help the company earn more trust. Lastly, check your search engine data to see if speed helps your web traffic grow. Truly, a fast path is a journey that leads to a much better brand in 2026. It builds a path of innovation that lets your whole team grow very fast. This secures your future in the digital world for a long time.


Frequently Asked Questions (FAQs)

Q1: Can I use UPI to send money to a US PayPal account?

Yes, the 2026 integration allows you to initiate payments via UPI to global PayPal users.

Q2: Are the fees lower than a standard bank wire?

Typically, yes, as the digital link removes several layers of traditional banking costs.

Q3: How fast does the money arrive in my account?

Most transactions through this bridge happen in real-time or within a few minutes.

Q4: Do I need a special app for this integration?

No, you just need the updated version of the PayPal app and a valid UPI ID.

Q5: Does offering UPI and PayPal help my SEO?

Yes, providing trusted and fast payment options improves user signals that search engines value.

Also Read: How to profit from Project Nexus 2026 opportunities